Comparing Structured Investment Products
Comparing Structured Investment Products
Structured products are not a single asset class — they are a family of custom-built instruments that package bonds and derivatives into very different risk and return profiles. Comparing a capital-protected note against a worst-of reverse convertible or a 3x leveraged certificate by headline coupon alone is like comparing a savings bond to a venture investment by interest rate. This article lays out a practical framework for comparing the main types of structured investment products, grouped by the risk categories used across the market.
The Risk Spectrum: Four Families of Products
Virtually every structured product falls somewhere on a spectrum that runs from capital preservation to aggressive leverage. A useful way to organise the universe is into four families:
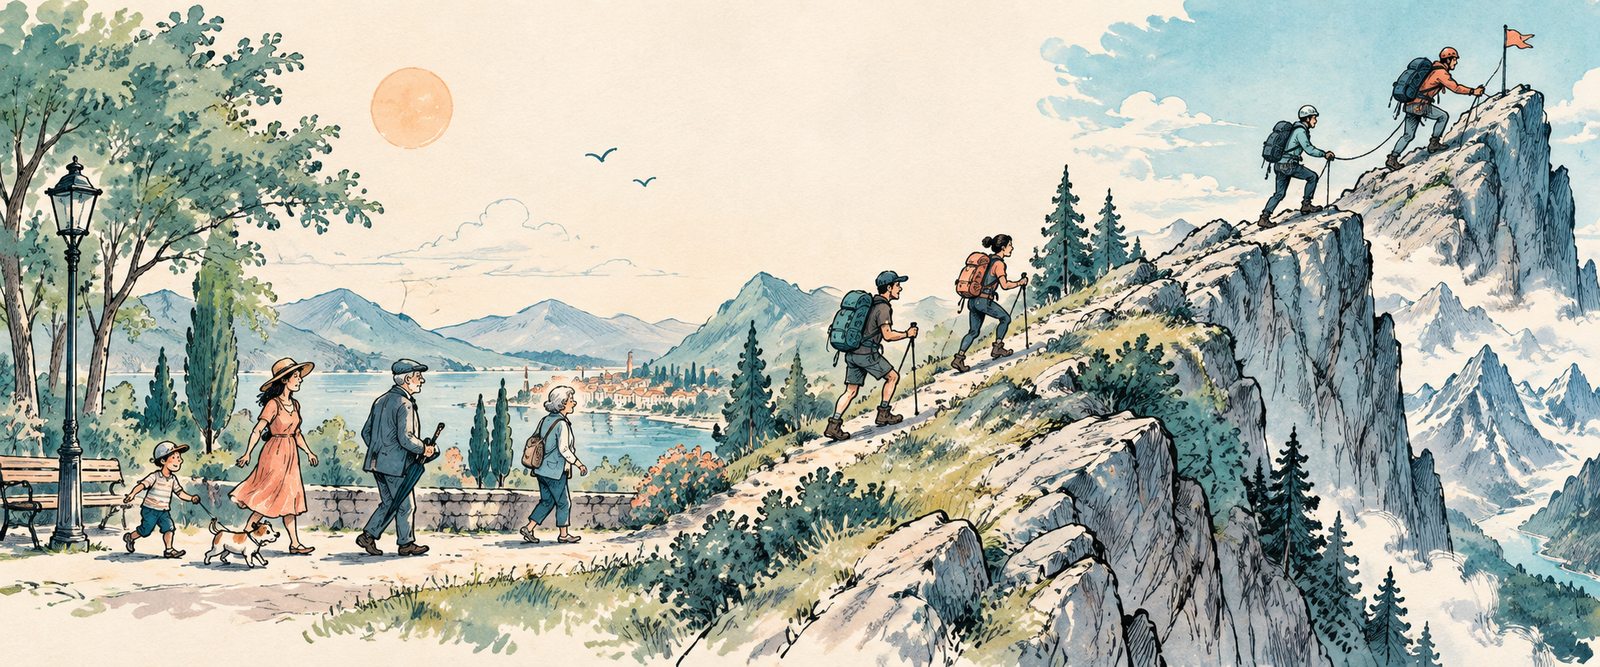
Moving along this spectrum generally means higher potential returns — but also less downside protection, more conditional features, and payoff profiles that are harder to reason about without simulation. The right comparison question is not "which product pays the highest coupon?" but "which payoff shape fits my market view, risk budget and time horizon?"
- Conservative — capital-preserving: principal protected notes and capital guarantees
- Moderate — income-oriented: reverse convertibles, autocall income notes and range accruals
- Aggressive — directional and leveraged: twin-win notes, leveraged certificates and outperformers
- Sophisticated — multi-asset and exotic: basket-linked payoffs, hybrid structures and exotic underlyings
Family 1: Capital-Protected Products (Conservative)
These products sit at the safest end of the spectrum. The issuer constructs them from a zero-coupon bond plus a call option, so a defined portion of principal is returned at maturity even if the underlying falls.
Principal protected notes (PPNs) come in three main variants:
Capital guarantees differ in who backs the promise and how much is guaranteed:
The key comparison points within this family are the level of protection, the participation rate, any return cap, and whether the guarantee is issuer credit or a separate insurance wrapper.
- Fixed coupon variants pay a fixed interest rate plus full principal at maturity — for example, a 5-year note paying 3% p.a. referenced to the S&P 500. The protection is conditional on holding to maturity and on the issuer remaining solvent.
- Participation variants give 50–100% of the underlying's gains, sometimes capped — for example 80% participation in NASDAQ with a 25% return cap. You trade upside for safety.
- Autocallable variants redeem early if the underlying hits a trigger on observation dates — for example a 3-year note with a 110% trigger and an 8% coupon if called. Early redemption usually means reinvesting into a lower-rate environment.
- 100% guarantees are backed by the issuer or an insurer for the full notional, which tightens the return potential because less premium is left for the option sleeve.
- Partial guarantees (80–95%) leave a 5–20% first-loss buffer in exchange for a larger option sleeve — for example a 90% guarantee with 120% participation in gold.
Family 2: Income-Oriented Products (Moderate)
Income products exchange full capital protection for above-market coupons. They are the most widely distributed structured products — and the source of most investor disappointment, because the coupon is paid in exchange for writing an option against your capital.
Reverse convertibles pay an elevated coupon and repay principal unless the underlying falls below a knock-in barrier:
Autocall income notes add early-redemption triggers to the coupon:
Range accruals pay based on how long the underlying stays inside a corridor:
The sketch above captures the essential bargain of income products: the coins keep falling as long as the branch holds. The branch is the barrier — invisible on a good day, and the single point on which the entire income stream rests.
- Single-reference notes link to one stock — for example a 6-month note on AAPL with a 70% barrier and a 12% annualized coupon. If AAPL closes below 70% of strike at maturity, you receive shares worth less than your investment.
- Worst-of / multi-reference notes tie the outcome to the weakest performer in a basket. Coupons are higher, but you add correlation risk: when markets fall, basket constituents tend to fall together.
- Phoenix-style notes pay conditional coupons only while the underlying sits above a coupon barrier — for example 10% p.a. while the S&P 500 stays above 80% of strike. If a coupon condition is missed, that coupon is lost.
- Memory-style notes accumulate missed coupons and pay them upon recovery. The headline coupon is lower, but the income stream is far more reliable.
- Digital (binary) accruals pay a fixed daily coupon while the asset remains in the range — for example 10% p.a. for every day EUR/USD trades between 1.05 and 1.15.
- Variable-rate accruals pay different rates depending on the zone inside the corridor, with the highest rate near the centre.
Family 3: Directional and Leveraged Products (Aggressive)
These products amplify market exposure rather than dampening it. There is no capital protection — the structure exists to increase sensitivity to the underlying's direction.
Within this family, compare the leverage factor, whether returns are measured daily or at maturity, the financing spread embedded in the swap, and — for outperformers — exactly which upside is being sold away.
- Twin-win notes with a loss floor participate in both rises and falls of the underlying while capping the loss — for example a −10% floor built as a zero-premium collar. These suit investors expecting a big move in either direction.
- Twin-win notes without a loss floor offer 150–200% participation with full principal at risk. The leveraged upside is real, but so is the downside.
- Bull leveraged certificates deliver 2x–3x the daily return of the underlying via synthetic swaps. Daily rebalancing introduces volatility drag: in choppy, trendless markets the certificate underperforms a naive multiple of the index return.
- Bear certificates profit when the asset falls, with theoretically unlimited loss on sharp rallies — the mirror image of a bull certificate, and equally unforgiving.
- Index trackers replicate an index's total return, including dividends, via a swap.
- Outperformance certificates add an option overlay such as covered calls to a tracker, trading away part of the upside for yield or a downside buffer.
Family 4: Multi-Asset and Exotic Structures (Sophisticated)
The most complex layer of the market combines multiple underlyings or non-standard risk factors. These products can be powerful portfolio tools, but their payoffs depend on correlation and path behaviour that even experienced investors struggle to estimate intuitively.
Basket-linked payoffs:
Hybrid and cross-asset structures:
Exotic-underlying instruments:
- Worst-of baskets pay based on the weakest performer — cheap to build, generous coupons, and the most concentrated risk.
- Best-of baskets pay based on the strongest performer — they benefit from low correlation between constituents but are costlier, so participation is lower.
- Rainbow baskets apply custom weightings to ranked performers and almost never have a secondary market; exiting early usually requires an issuer buyback at the issuer's price.
- Multi-asset class notes combine equities, commodities, rates and FX in a single payoff — with correlation risk that explodes precisely in stress scenarios when diversification is needed most.
- Insurance-linked notes (such as catastrophe bonds) pay coupons that vanish, or see principal written down, when a defined event triggers.
- Volatility-linked notes reference VIX futures or variance swaps and suffer contango roll decay in calm markets — a persistent headwind that is invisible in the term sheet.
- Inflation-indexed notes link returns to CPI with a deflation floor and an inflation cap, which suits pension mandates with inflation-linked liabilities.
- Commodity-indexed notes track oil, metals or agriculture, sometimes using Asian averaging (averaging prices over time reduces volatility and cost), seasonal rolls or downside buffers.
Side-by-Side: How the Families Compare
Because payoffs are conditional, a structured comparison across dimensions matters more than any single number:
- Capital protection: protected notes return 90–100% of principal at maturity; reverse convertibles protect only above the barrier; leveraged certificates and worst-of structures offer none.
- Income profile: Phoenix and memory autocalls and range accruals are income-first; participation notes and trackers are growth-first; twin-wins are volatility-first.
- Upside potential: participation notes cap it (e.g. 25% cap), outperformers trade it for yield, leveraged certificates multiply it — and the downside in the same proportion.
- Barrier proximity risk: the closer the barrier to the current price, the higher the coupon and the higher the probability of taking delivery of depressed shares.
- Liquidity: PPNs and large-issue autocalls have active secondary markets; rainbow baskets and exotic-underlying notes often have none before maturity.
- Transparency of risk: payoff diagrams of protected and leveraged products are easy to draw; conditional coupons and worst-of baskets require scenario analysis or Monte Carlo simulation to understand.
How to Actually Compare Products: Look at Distributions, Not Coupons
The single most common mistake is comparing headline coupons across product types. A 10% coupon on a Phoenix autocall with an 80% barrier is a completely different instrument from a 10% coupon on a 90%-protected participation note. What matters is the full distribution of outcomes.
A rigorous comparison looks at four dimensions of that distribution:
This is why simulation has become the standard comparison tool: a 50,000-path Monte Carlo run against the actual term sheet parameters shows the distribution, not the marketing page. Token Engine's SP Evaluator does exactly this — upload any term sheet and receive an independent report of expected returns, loss probabilities and risk metrics.
- Expected annualized return — the probability-weighted outcome across all scenarios, which is almost always below the headline coupon.
- Probability of loss — how often the structure ends below the initial investment; for aggressive income notes this can run from 10% to 25% even with double-digit coupons.
- Value at risk (VaR) — the loss in the worst 1% of scenarios, which reveals the left tail that a barrier breach leaves unprotected.
- Scenario behaviour — what happens in a flat market, a slow grind lower, a sharp crash, and a strong rally. Different structures "win" in each.
Common Comparison Mistakes
- Comparing coupons across different barrier levels — a 12% coupon with a 70% barrier carries far more risk than a 9% coupon with a 60% barrier; the coupon compensates for the difference.
- Ignoring autocall probability — early redemption caps total income and forces reinvestment; a product that is called after one year is not comparable to one running to maturity.
- Treating protection as absolute — principal protection holds at maturity only, is void if you sell early, and depends entirely on issuer solvency.
- Overlooking worst-of correlation — basket constituents correlate strongly in crashes, so the "diversified" worst-of behaves like its single worst asset exactly when it matters.
- Forgetting volatility drag — a 3x daily-rebalanced certificate underperforms 3x the index return in choppy markets; the tracking difference compounds.
- Judging by the best case — the headline coupon or participation rate is the best scenario, not the expected outcome.
The Bottom Line
Structured products span the entire risk spectrum, from instruments that guarantee principal to instruments that can lose more than the underlying itself. The four-family framework — conservative, income-oriented, aggressive and sophisticated — is the right starting point for any comparison, because it forces you to compare like with like before looking at numbers. Within a family, compare protection levels, barrier distances, participation rates, caps, and the full return distribution rather than the headline coupon.
Try the free SP Evaluator → Upload any structured product term sheet and get an independent, simulation-based report of its risk and return profile — so your next comparison is based on data, not marketing.