13.40% p.a. Multi Barrier Reverse Convertible (Callable)
Worst-of Alcon · Kühne + Nagel · Logitech — ISIN CH1607594129 — CHF
Headline Simulation Results
| Metric | Value |
|---|---|
| Expected annualized return | +7.69% |
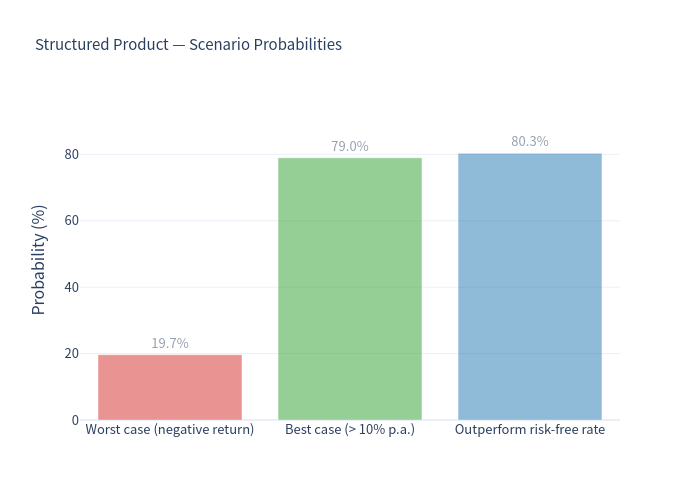
| Probability of a negative return | 19.69% |
| 99% confidence VaR (1-year) | −25.44% |
| Expected total return over the (variable) holding period | +8.56% |
| Expected holding period | ≈ 15.9 months (1.33 years) |
| Best possible annualized return (coupon cap) | ≈ +13.40% |
Basic Product Information
What it is. A yield-enhancement note (Swiss SSPA type 1230) issued by Leonteq Securities AG, quoted in CHF with a CHF 1,000 denomination. It pays a fixed coupon of 13.40% p.a., distributed quarterly (CHF 33.50 per CHF 1,000 = 3.35 index points per quarter, 7 coupons in total if held to the final date).
How it works — plain language
- You get paid the coupon no matter what — the quarterly coupon is paid "in any case" for as long as the note is alive, even if the shares fall.
-
You only lose capital if the shares fall a long way. Each of the three shares has a
barrier at 59% of its starting level, monitored continuously during the whole term (~21 months).
- If no share ever trades at or below 59% → you get your full capital (100) back at maturity, plus all coupons.
- If the barrier is breached and the worst-performing share finishes below its starting level → you receive that worst share (physically) instead of cash, i.e. you bear the full downside of the weakest name.
- If the barrier is breached but the worst share still finishes at or above its starting level → you get your full capital back.
- The issuer may call the note early. On any of five quarterly observation dates the issuer can redeem at par plus the coupon due — after which no further coupons are paid.
Key structural facts. Worst-of basket (downside driven by the weakest of Alcon, Kühne + Nagel and Logitech); barrier 59% (continuous); strike 100%; upside is capped (no equity participation); issuer-callable; single currency CHF (no FX/quanto); issuer credit exposure to Leonteq (Fitch BBB−).
Key Statistics — Structured Product vs Underlying
Benchmark = equally-weighted basket of the three shares (the same three names, no worst-of). Underlying figures are total returns (dividends added).
| Metric | Structured Product | Underlying (Basket + Div) | Underlying (Price only) |
|---|---|---|---|
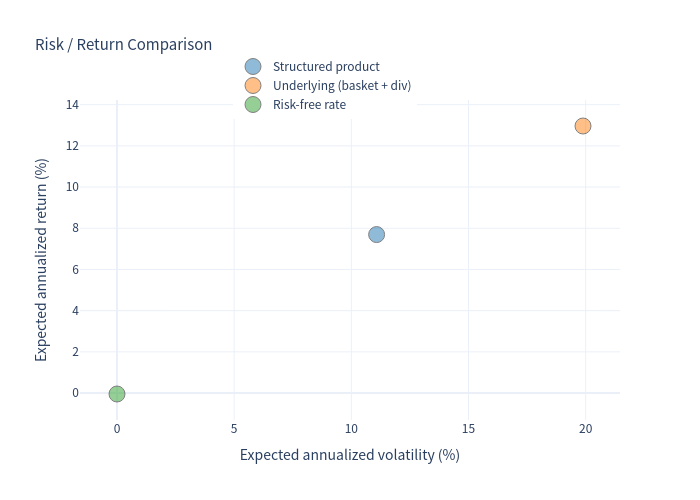
| Expected annualized return | +7.69% | +12.96% | +11.39% |
| Expected annualized volatility | 11.08% | 19.89% | 19.89% |
| Probability of loss | 19.69% | 28.30% | 31.58% |
| 99% VaR (1-year) | −25.44% | −20.84% | −22.41% |
Simulation Charts
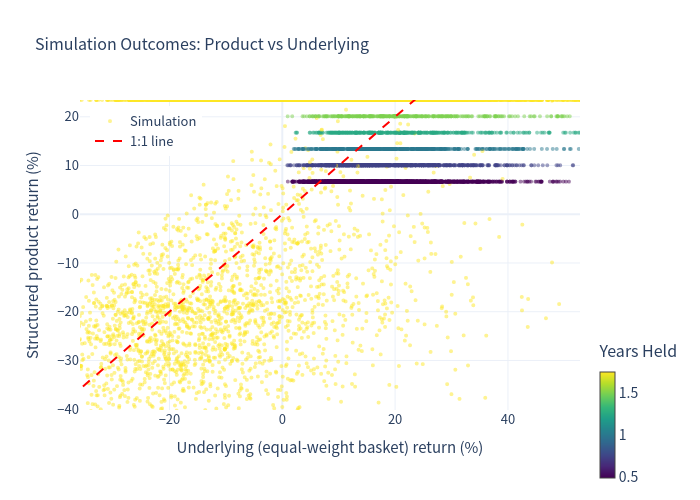
Outcome scatter — product vs underlying
The horizontal "shelf" at +10% / +23.45% shows the capped upside (coupons dominate). Points dropping steeply below the 1:1 line are barrier-breach paths where the investor absorbs the worst-of downside.
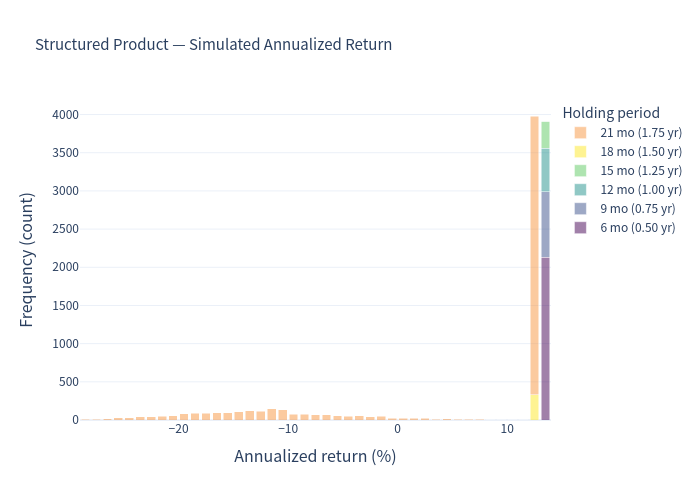
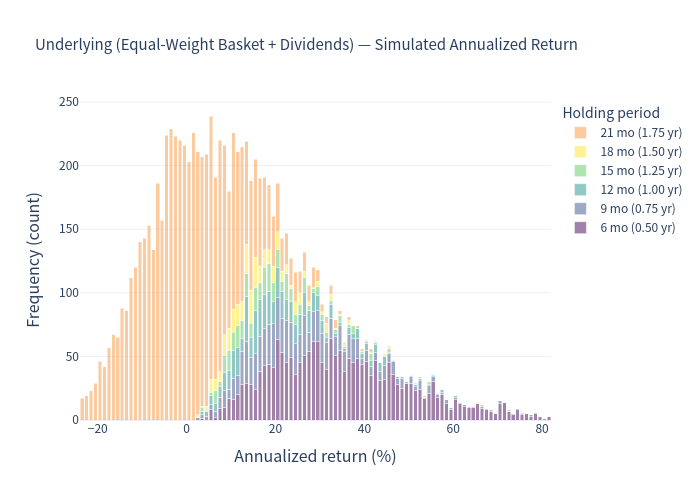
Annualized-return histograms
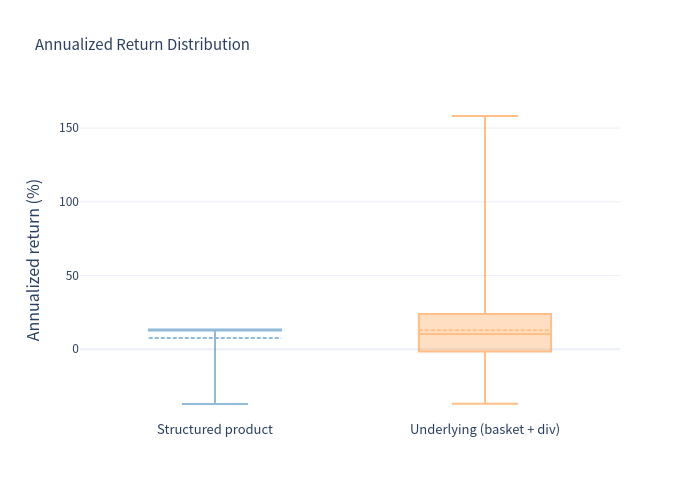
Colours indicate how long the note was held. The product's return concentrates in a narrow positive band (coupon-driven) with a thin left tail; the underlying's distribution is far wider and heavier-tailed. Note that ~21% of paths are redeemed after only 6 months, so their annualized figures are amplified by the linear-annualization for sub-12-month holding periods — these should be read together with the (small) total return and short holding period.
Risk / return map
The note sits materially to the left (lower volatility) of the underlying basket and well above the risk-free rate.
Return distribution box plot
Scenario probabilities
Holding-period and coupon-count distributions
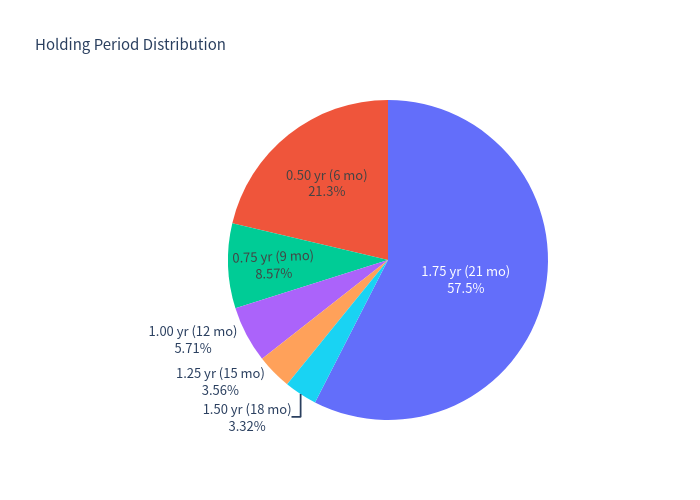
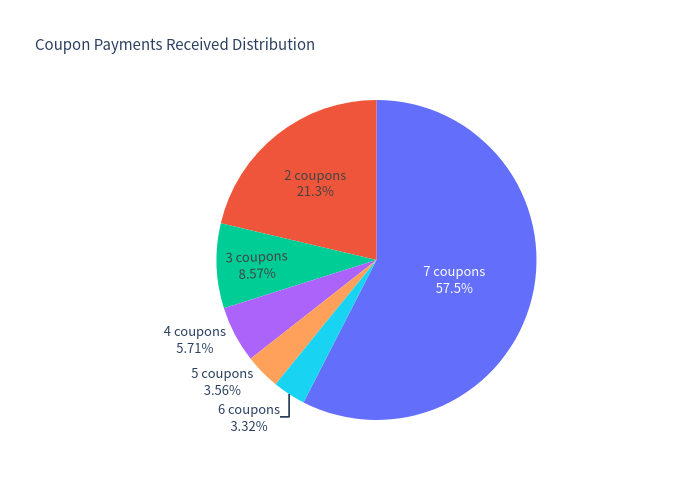
The note is called early in ~42% of paths (most often at the first observation date, 21.3% of all paths) and runs the full 21 months in ~58% of paths. The coupon-count distribution mirrors this.
Investment Commentary
Risks to be aware of
- Upside is fully capped at the coupon — the investor gives up all equity upside above ~13.4% p.a.
- Worst-of exposure: the downside is driven by the weakest of three shares, so a single bad name can trigger losses; the barrier is more easily breached than for a single-name note.
- Issuer call truncates the coupon stream — early redemption in ~42% of paths limits realised income and shortens the average holding period to ~1.3 years (vs the 2-year maximum).
- Fat left tail: the worst 1% of scenarios lose more than ~40%, and the 99% VaR (−25.4%) is worse than the underlying basket's (−20.8%) because a single breached barrier forces the investor to buy the worst performer at par.
- Issuer credit risk (Leonteq, BBB−).
Figures are simulated, not guarantees. This analysis is for information only and is not investment advice.
Strengths