Morgan Stanley SX5E Market-Linked Certificates of Deposit due February 4, 2030
Headline Simulation Results
Based on 10,000 Monte-Carlo simulations of the EURO STOXX 50 (SX5E) index over the 4-year term (observation date January 30, 2030):
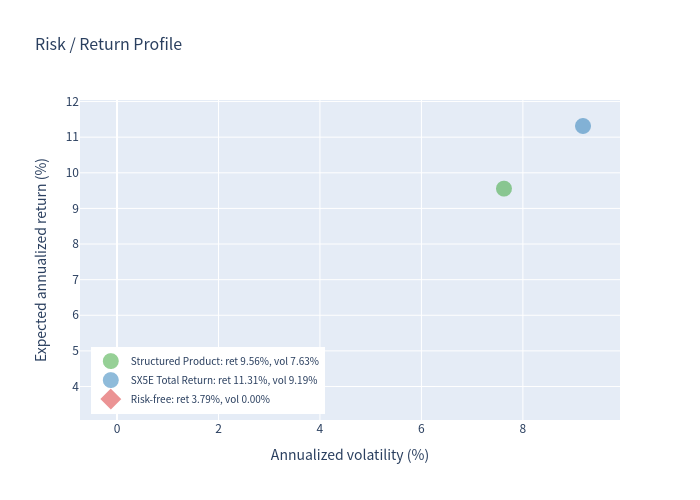
Product (vs. 11.31% for SX5E total return)
Product (vs. 11.11% for SX5E total return)
Product (vs. -11.34% for SX5E total return)
| Metric (annualized) | Structured Product | SX5E Total Return |
|---|---|---|
| Expected annualized return | 9.56% | 11.31% |
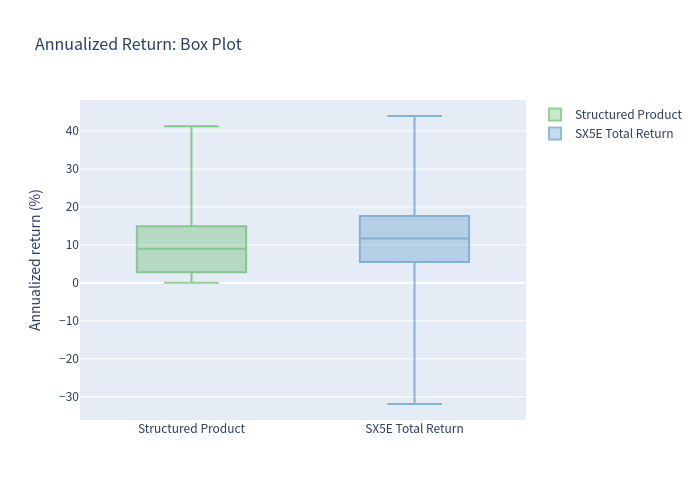
| Probability of negative return | 0.00% | 11.11% |
| 99% confidence VaR (1 year) | 0.00% | -11.34% |
- The product is fully principal protected, so simulated annualized returns are never negative; the downside “worst case” is a flat 0.00% (deposit returned in full).
- Expected total return over the full 4-year holding period: 48.36% for the product vs 55.89% for the SX5E total return.
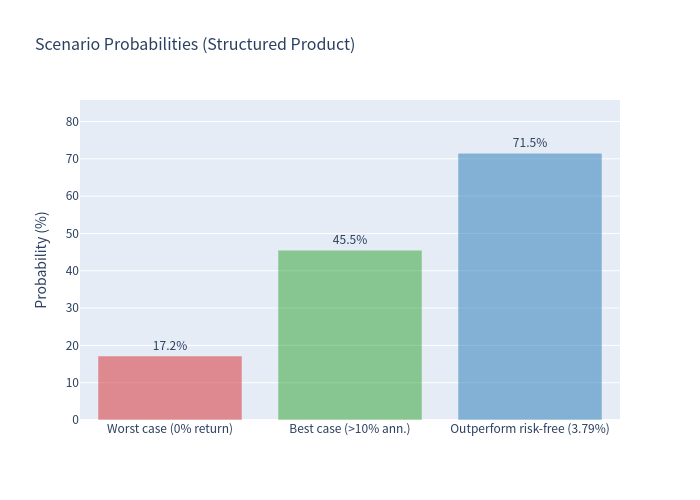
- Probability of beating the risk-free rate (3.79%): 71.47%.
Basic Product Information
- Issuer: Morgan Stanley Bank, N.A. (CUSIP 61779EBL3), USD-denominated certificates of deposit.
- Underlying: EURO STOXX 50® Index (SX5E), a single equity index in EUR; payoff tracks the index level (no separate FX/quanto adjustment).
- Term: ~4.0 years (pricing January 30, 2026 → observation January 30, 2030 → maturity February 4, 2030). Single observation at maturity.
- Participation rate: 100% (the illustrated payoff table uses 100%; disclosed range 100%–110%). Base case used here = 100%.
- Coupons: none — the CDs do not pay interest.
- Upside: uncapped.
How it works (plain language)
You deposit $1,000. At maturity, look at how much the EURO STOXX 50 has moved since the start date:
- If the index is up, you receive your $1,000 back plus 100% of the index gain (e.g., index +20% → $1,200).
- If the index is flat or down, you simply receive your $1,000 back — the deposit is protected, and you do not participate in losses.
There are no periodic coupons and no early redemption; the note is designed to be held to maturity. Effectively the CD is a principal-protected structure whose upside is a 4-year at-the-money call on the EURO STOXX 50.
Key Statistics (Simulated)
| Metric | Structured Product | SX5E Total Return |
|---|---|---|
| Expected annualized return | 9.56% | 11.31% |
| Expected annualized volatility | 7.63% | 9.19% |
| Probability of loss | 0.00% | 11.11% |
| 99% VaR (1 year) | 0.00% | -11.34% |
- Risk-free rate (1-year average US 1-Year Treasury): 3.79%.
- Expected holding period: 4.00 years in 100% of simulations (always held to maturity).
- Probability of an annualized return above 10%: 45.52%.
- Probability the investor simply gets the deposit back (index down at maturity): 17.15%.
Charts
Simulated 4-year outcomes: product vs. underlying
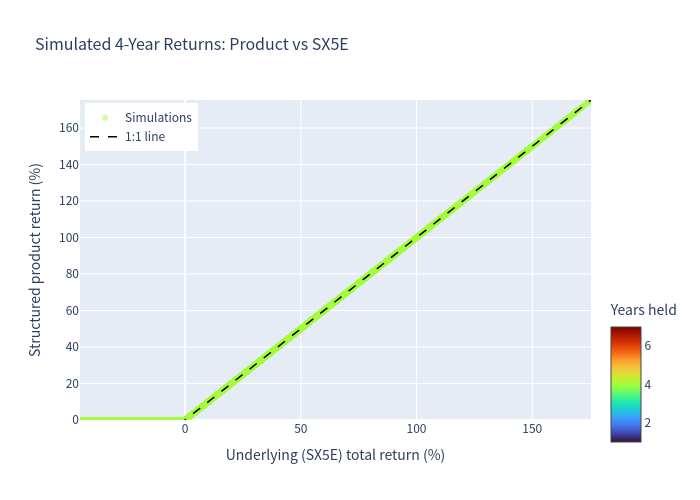
Points above the 1:1 line are scenarios where the index falls: the principal-protected payoff returns 0% while the index total return is negative. When the index rises, the product tracks the index price return but sits slightly below the 1:1 line, because index dividends are not passed through to the investor.
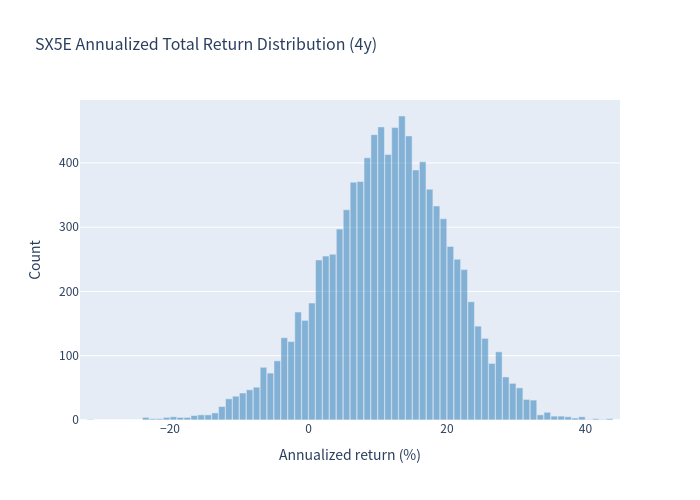
Distribution of annualized returns — SX5E total return
Distribution of annualized returns — structured product
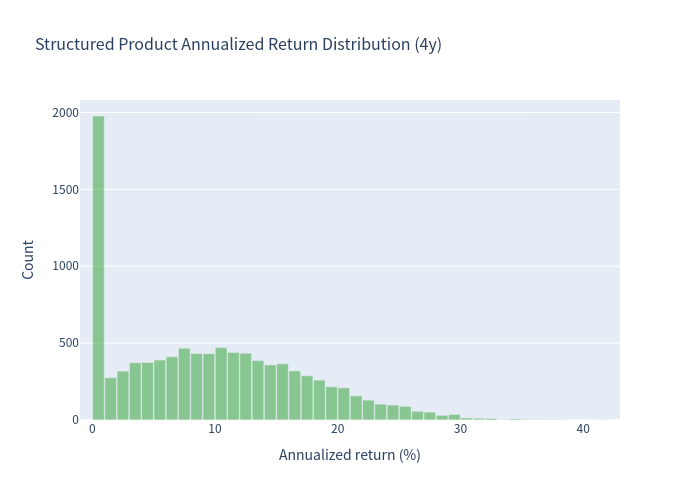
The product's distribution is truncated at 0% (a large mass of ~17% of scenarios where the index finishes down and the deposit is simply returned), with a right tail that mirrors the index upside.
Risk / Return profile
Box plot comparison
Scenario probabilities
Investment Commentary
Strengths
- Full principal protection at the deposit amount (subject to issuer credit risk and FDIC limits): the simulated probability of a negative nominal return is 0.00%.
- Uncapped, 100% upside participation in the EURO STOXX 50 — a meaningful equity exposure that broad market deposits do not offer.
- A high likelihood (71.47%) of out-performing the risk-free rate over the term.
Considerations
- No periodic income: the structure pays no coupons, so there is no cash flow before maturity.
- Opportunity cost vs. the index: because dividends are not passed through (SX5E is a price-only index) and the deposit is not interest-bearing, the expected annualized return (9.56%) sits below the index total return (11.31%). The estimated value at issue ($970.50 per $1,000 CD) reflects built-in costs.
- Illiquidity / hold-to-maturity design: the CDs are not trading instruments and cannot be withdrawn early (other than on death/incompetence).
- Credit risk of the issuer applies to amounts above FDIC insurance limits.
This analysis is based on Monte-Carlo simulation of market data and does not constitute investment advice or a suitability assessment.