Structured Product Evaluator | info@tokenengine.ai
Structured Product Evaluation
15.60% p.a. Multi Barrier Reverse Convertible (Callable) on RWE, Shell & Siemens Energy
ISIN CH1593789543 | Settlement: EUR | Worst-of barrier reverse convertible | Issuer-callable
Headline Simulation Results
Based on 10,000 Monte-Carlo simulations over the product's life (final fixing 24/09/2027).
Underlying: 13.20%
Underlying: 31.19%
Underlying: -29.08%
Underlying: 23.13%
| Metric | Structured Product | Underlying (equal-weight basket, total return) |
|---|---|---|
| Expected annualized return | 12.84% | 13.20% |
| Expected annualized volatility | 11.55% | 23.13% |
| Probability of a negative return | 5.54% | 31.19% |
| 99% confidence VaR (1 year) | -40.19% | -29.08% |
| Median annualized return | 15.60% | — |
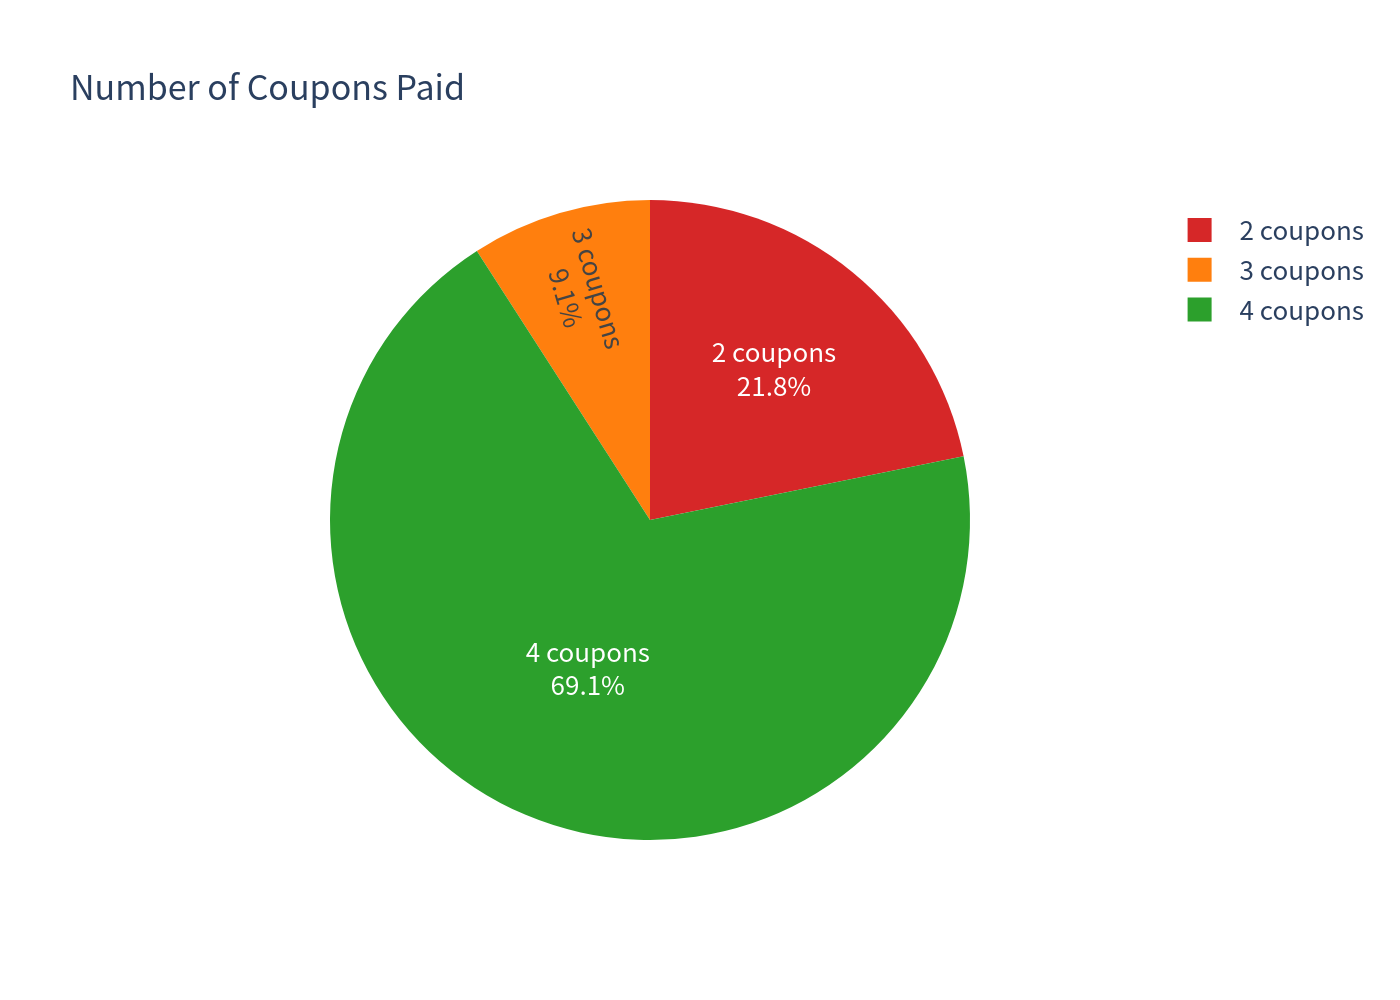
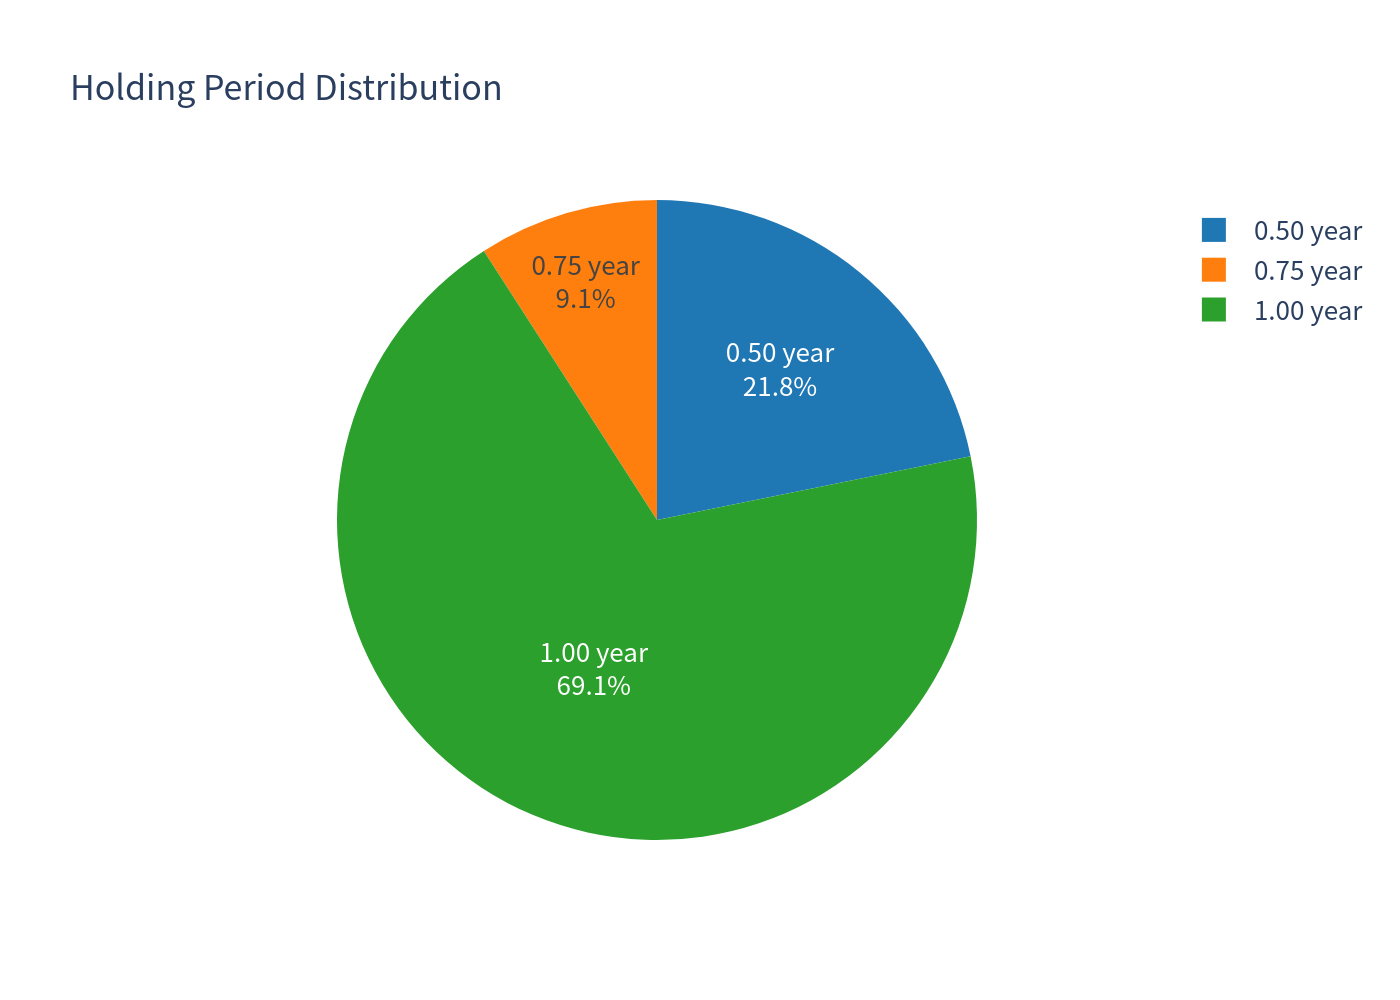
- Expected holding period: 10.42 months (69.09% of paths run to maturity; 21.81% are called at month 6; 9.10% are called at month 9).
- Expected total return over the realized holding period: 10.78%.
- Probability of outperforming the risk-free rate (2.01%): 94.46%.
- Probability the product beats the underlying basket's total return: 53.37%.
Product Overview
What it is. A one-year, euro-denominated note that pays a fixed 15.60% p.a. coupon (four quarterly payments of EUR 39.00 per EUR 1,000, i.e. 3.90 index points each on a 100 notional), in all cases, regardless of how the three underlying shares perform. The coupon is provided by combining a small interest component (3.02% p.a.) with a large option-premium component (12.58% p.a.).
How it works (plain language)
- Coupon (unconditional): you receive 3.90 points each quarter (~15.60% per year) whether or not the shares fall and whether or not the note is called early.
- Three shares, worst-of: the redemption looks at RWE AG, Shell PLC and Siemens Energy AG. The relevant measure is the worst-performing of the three (its final level divided by its starting level).
- Barrier (55%): if any one of the three shares trades at or below 55% of its starting level at any time during the year, the capital protection is lost (continuous observation). The barrier affects only the redemption of principal, never the coupon.
- No barrier breach: you get your denomination (100) back at maturity, plus the coupons.
- Barrier breached: at maturity, if the worst share is below its starting level you receive that worst share (worth less than par); if the worst share is at or above its starting level you still get 100 back.
- Issuer call: the issuer may redeem early on two dates (month 6 and month 9). If it does, you receive 100 plus the coupon for that date and nothing more.
- Upside is capped: the maximum you can ever receive is par (100) plus coupons — you do not participate if the shares rally.
Underlyings: RWE AG (German utility), Shell PLC (energy major), Siemens Energy AG (energy-technology). All quoted in EUR; no FX/quanto exposure.
Simulation Outcomes
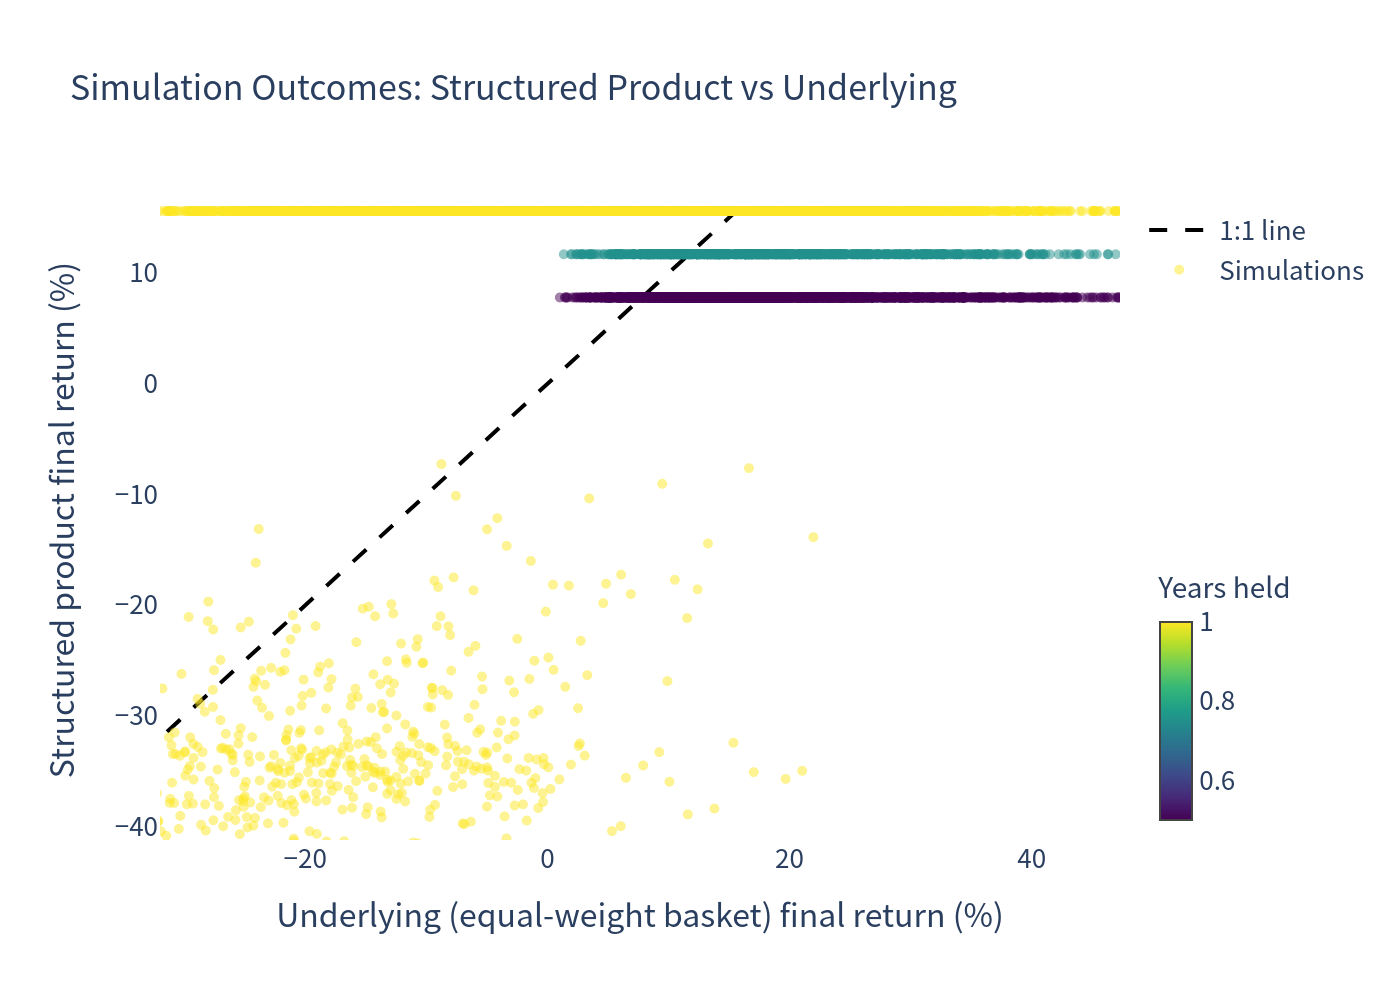
The scatter below plots each simulation's final return of the structured product against the final return of the underlying basket. Most outcomes sit flat at +15.60% (the fixed coupon) regardless of the basket, while a small cluster shows the loss tail.
Return Distributions
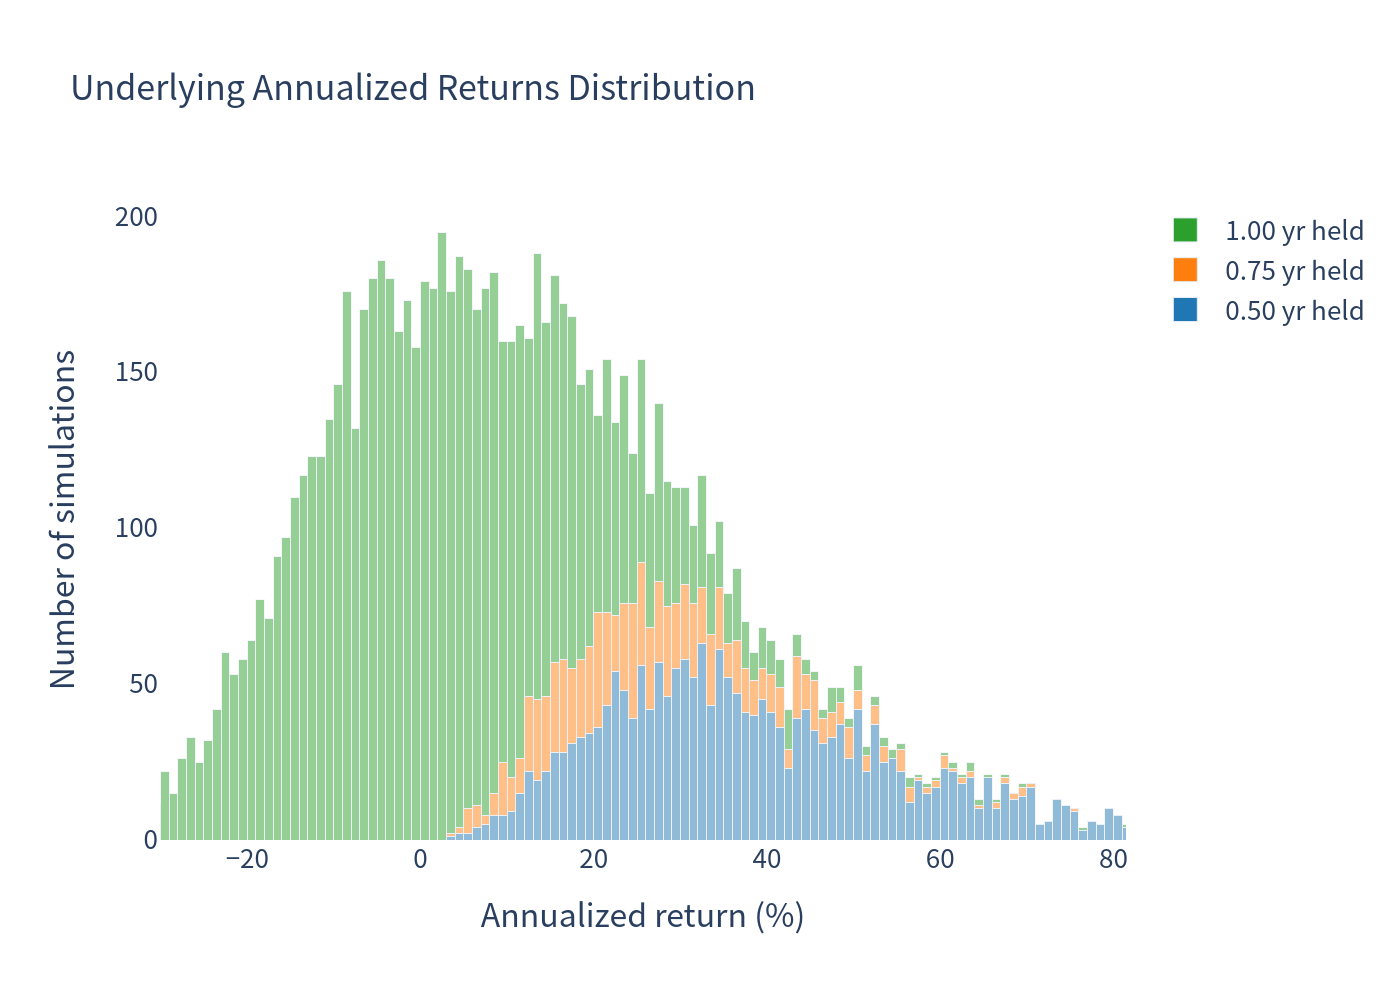
Annualized returns for the underlying basket (stacked by holding period), 1% bins:
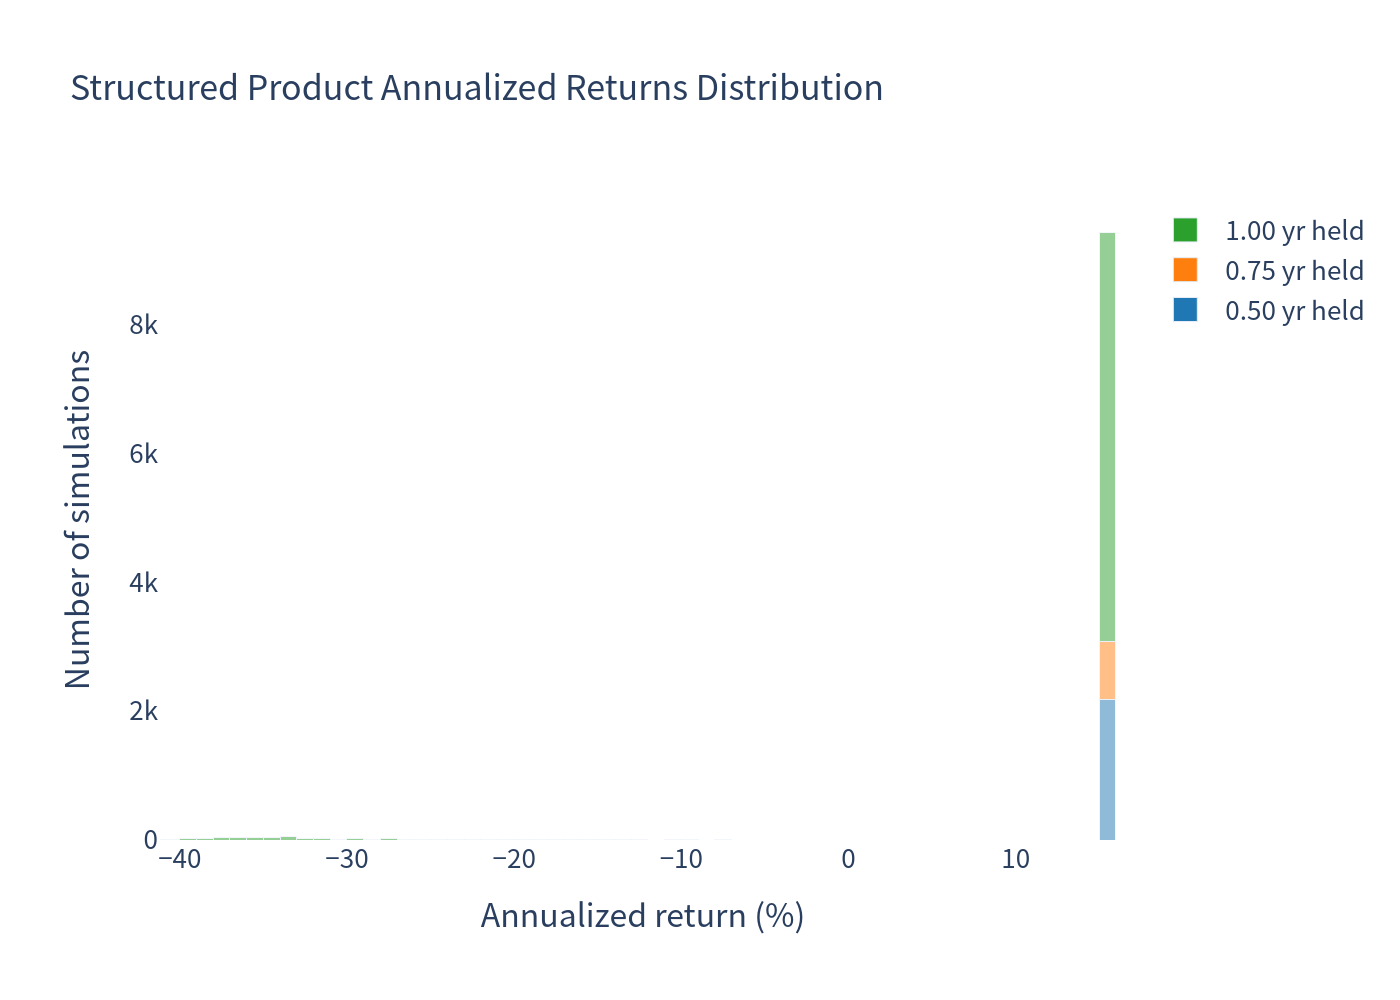
Annualized returns for the structured product (stacked by holding period), 1% bins — note the dominant spike at +15.60% and the negative tail:
Number of coupons paid — the product pays 2, 3 or 4 coupons depending on the holding period:
Holding period — how long the note remains outstanding:
Scenario Probabilities
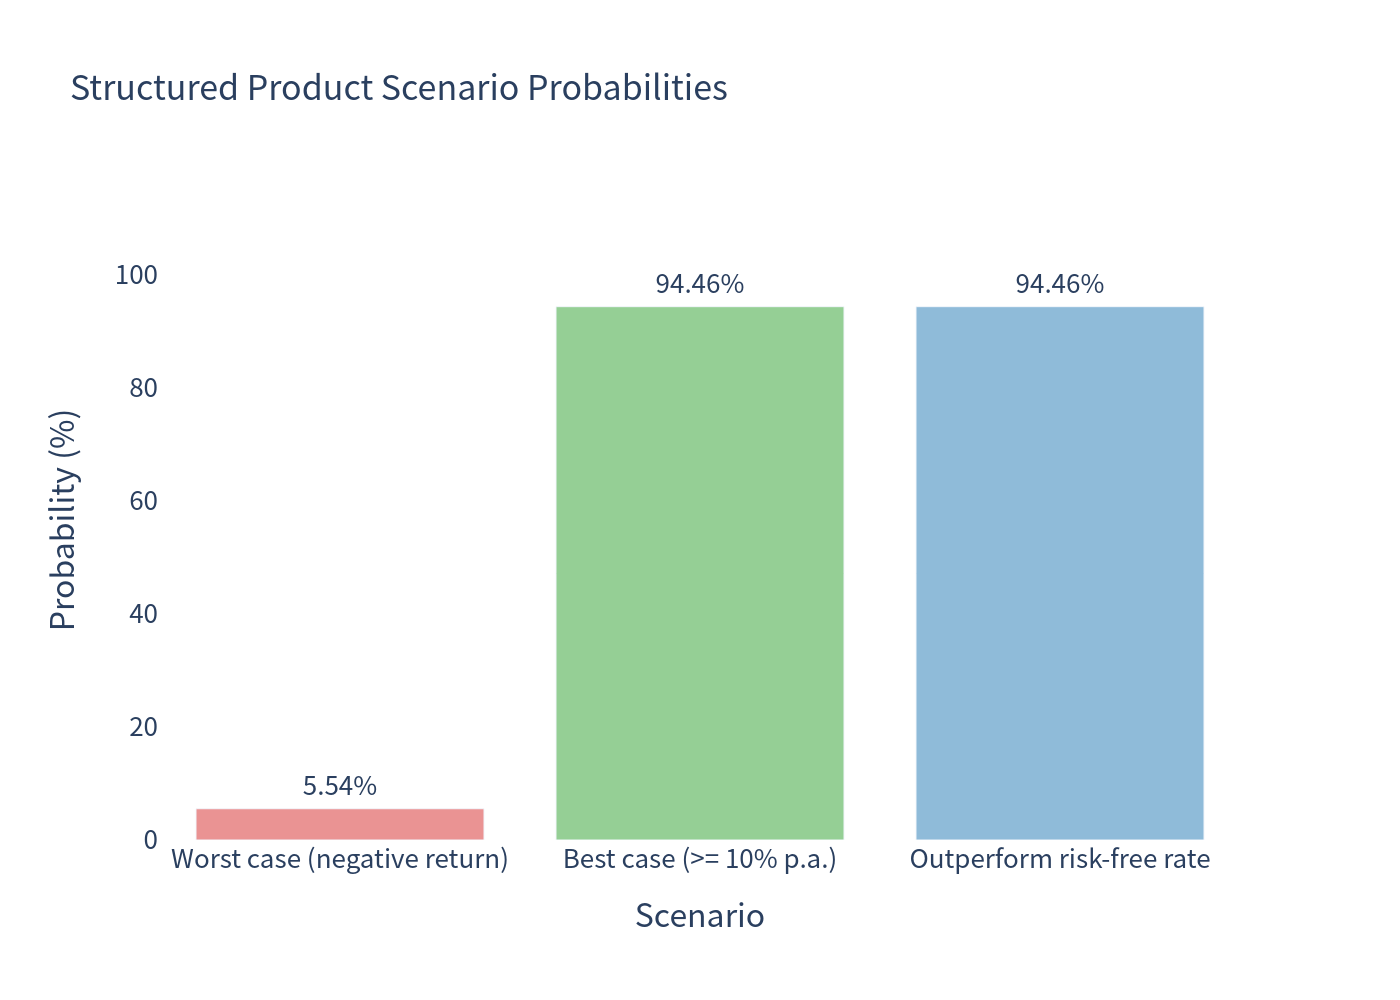
- Worst case (negative return): 5.54% — the 55% barrier is breached and the worst share finishes far enough below its starting level that the redemption value plus the coupons falls below par (in every simulated loss path the worst share ended well below its strike).
- Best case (annualized return ≥ 10%): 94.46% — the fixed coupon is earned in full (15.60% p.a.).
- Outperform the risk-free rate: 94.46%.
Risk / Return Profile
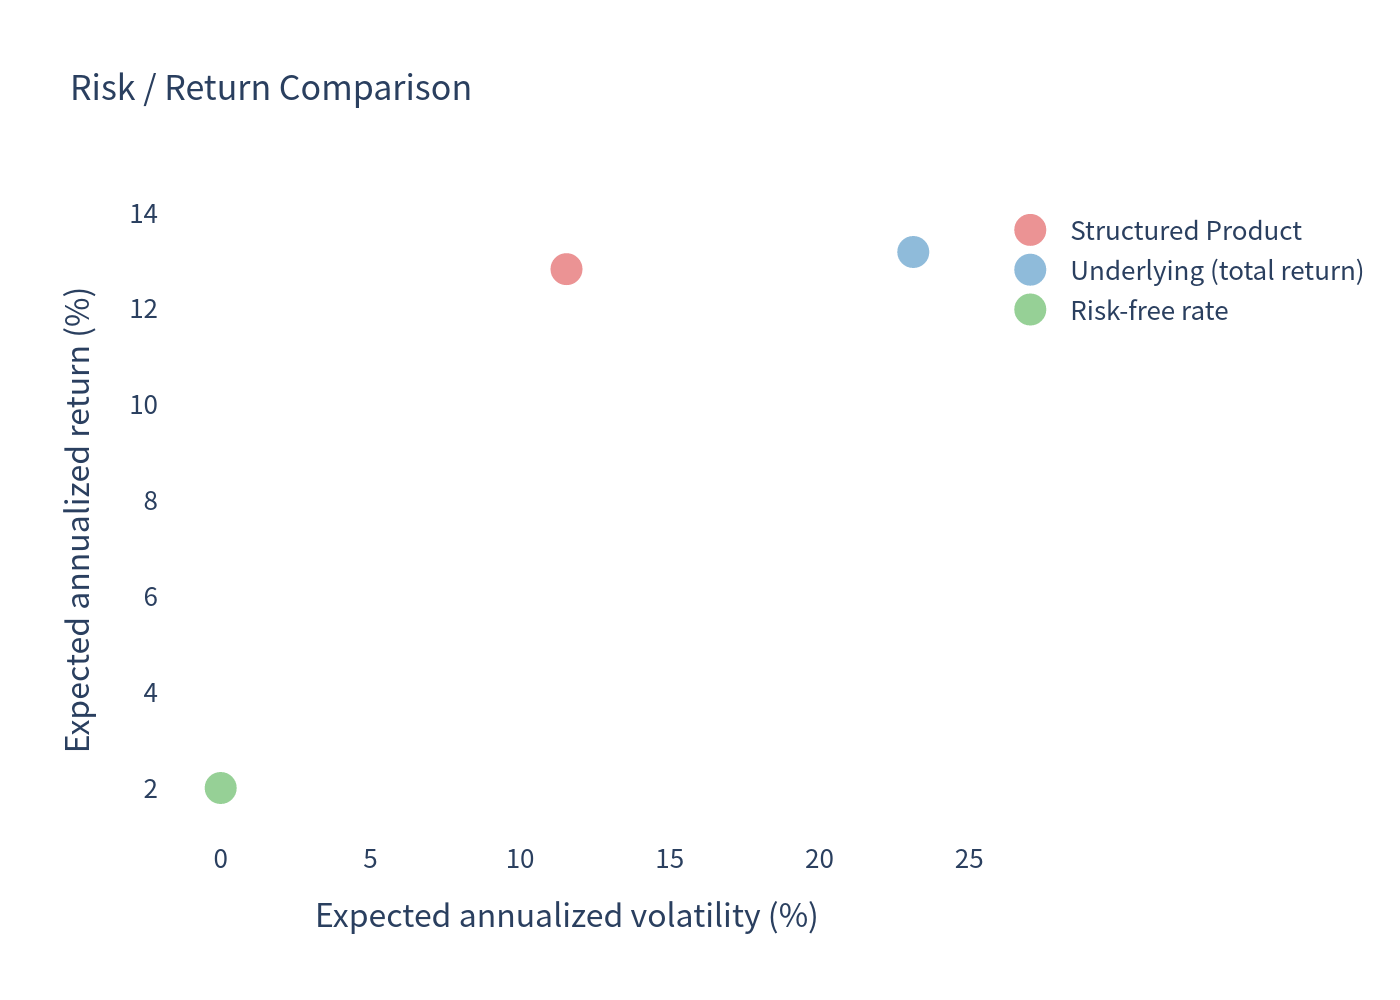
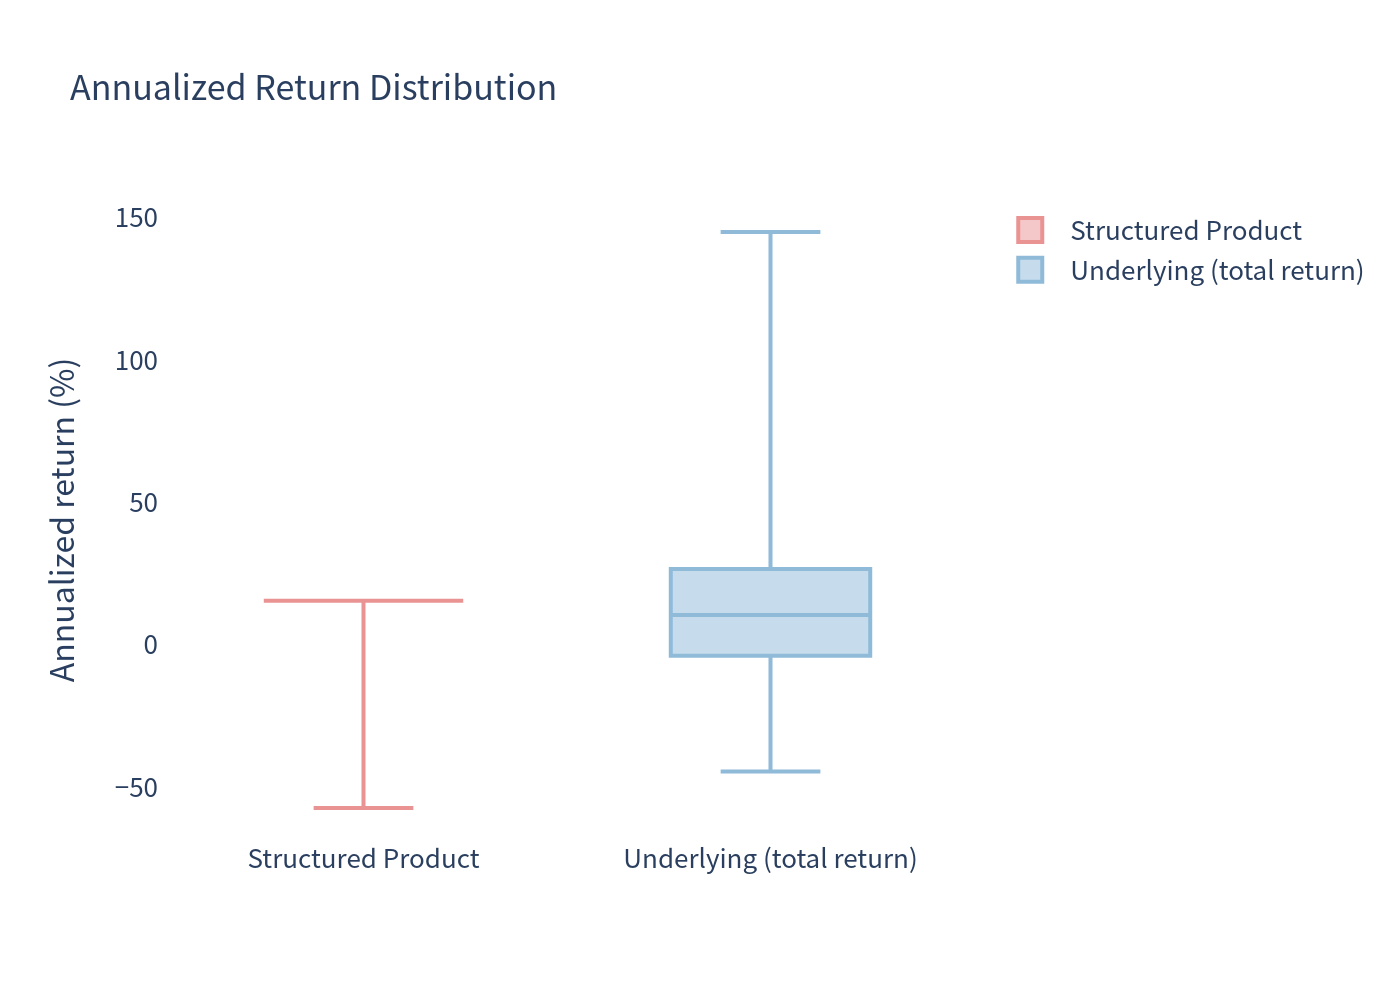
The structured product offers a similar expected annualized return to the underlying basket (12.84% vs 13.20%) but with roughly half the volatility (11.55% vs 23.13%) and a far lower probability of loss (5.54% vs 31.19%). This improved "average" profile is bought by sacrificing all upside and accepting a fat left tail: the 99% VaR is -40.19% versus -29.08% for the basket.
Investment Commentary
Potential positives
- High fixed income: the 15.60% p.a. coupon is paid unconditionally and is earned in the large majority of scenarios (94.46% of simulations produce a +15.60% annualized return).
- Conditional protection cushion: the barrier sits at 55% (a 45% drop from inception) and applies continuously, so moderate declines in the shares still return par.
- Low probability of loss: only 5.54% of paths end below par, vs 31.19% for the underlying basket.
- No FX exposure: all underlyings and the settlement currency are EUR.
- Lower realized volatility of the note relative to its underlyings.
Key risks to be aware of
- Capped upside with full downside: you never earn more than par plus coupons, yet a barrier breach with the worst share below strike delivers that share — potentially a large capital loss. In loss scenarios the average redemption value was ≈ 50 of notional (≈ 66 including the coupons received).
- Worst-of exposure: the barrier can be triggered (and the loss driven) by any single share. Three shares, three chances to breach.
- Issuer call caps the good scenarios: early redemption occurs mainly when the shares rise, truncating the favourable paths (30.91% of paths called).
- Issuer credit risk: repayment depends on the issuer (Leonteq Securities AG, Guernsey Branch; Fitch BBB-).
- Fat left tail: the 99% VaR (-40.19%) is worse than the underlying's, consistent with a short-volatility, yield-enhancement payoff.
Summary
The product is a classic yield-enhancement structure: it converts the volatility of three European energy/utility shares into a high, narrowly-variable coupon while truncating upside. Simulated expected annualized return is 12.84% with a 5.54% probability of loss and a 1-year 99% VaR of -40.19%. The headline risk is the worst-of barrier: rare, but severe.