Morgan Stanley Contingent Income Auto-Callable Securities due February 4, 2031
CUSIP 61780AJV8 — Single-Underlier Autocallable Note
Headline Simulation Results
| Metric | Value |
|---|---|
| Expected annualized return | 13.59% |
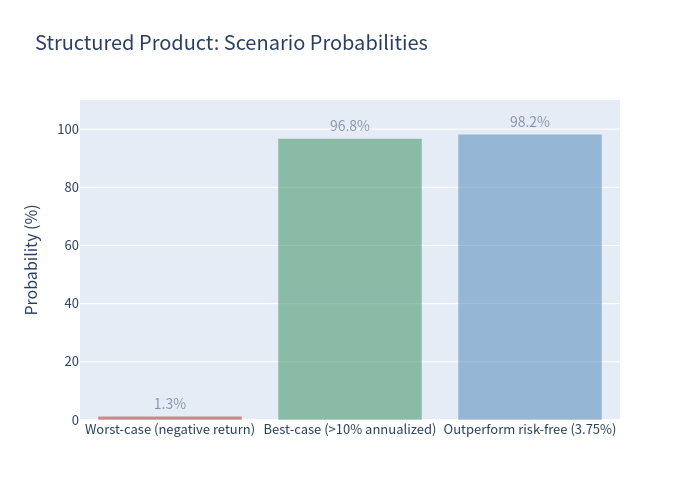
| Probability of negative return | 1.28% |
| 99% confidence VaR (1-year) | -2.74% |
| Expected holding period | ~1.09 years (13.03 months) |
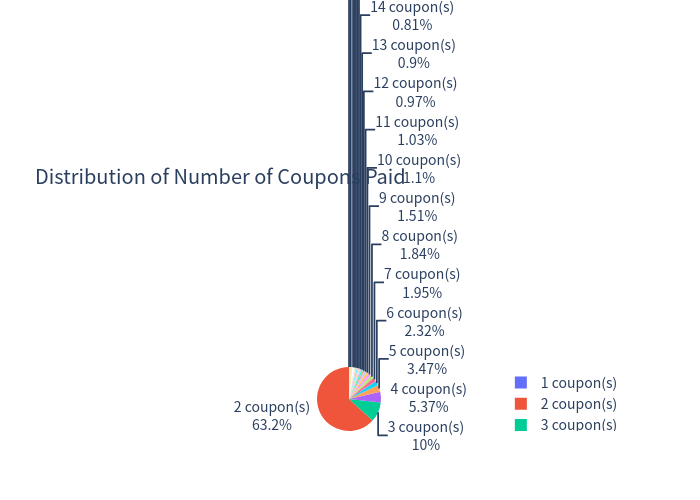
| Probability of early autocall | 94.57% |
| Expected total return over realized holding period | 13.54% |
| Outperformance vs risk-free rate (3.75%) | 98.24% |
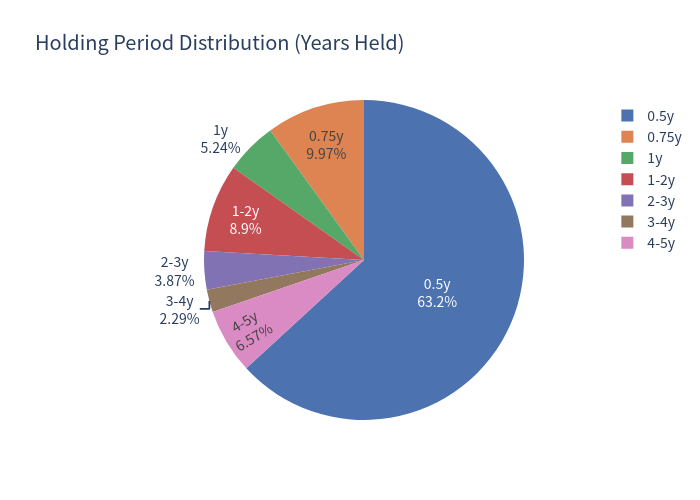
The note is a high-coupon, short-dated-in-practice structure: because the autocall trigger sits at 100% of the initial level and is tested quarterly beginning at month 6, roughly 95% of simulated paths are called away early — most of them at the very first call date (6 months). The headline annualized return and the very low realized volatility both reflect this frequent, fast redemption.
Basic Product Information
- Type: Contingent Income Auto-Callable Securities (a “yield-enhancement autocallable note”).
- Issuer / Guarantor: Morgan Stanley Finance LLC / Morgan Stanley.
- Underlier: S&P U.S. Equity Momentum 40% VT 4% Decrement Index (a leveraged, volatility-targeted (40%) US equity momentum index with a 4% per-annum decrement).
- Contingent coupon: 13.75%–14.75% per annum (midpoint 14.25% used here), paid quarterly only if the underlier closes at or above 60% of its initial level on the observation date.
- Automatic early redemption: Quarterly, beginning after 6 months, if the underlier closes at or above 100% of its initial level; investors then receive par plus the period coupon and no further payments.
- Downside / barrier: 60% of initial level. If the final level is at or above 60%, par is returned; if it closes below 60%, the investor takes a full 1-to-1 loss of the downside.
- Upside: Capped — investors never participate in any appreciation of the underlier.
- Term: 5 years to February 4, 2031 (final observation January 30, 2031).
How It Works (in plain terms)
Think of the note as a coupon-paying bond with an embedded downside put that you (the investor) have sold:
- Every quarter you have a chance to earn a coupon of ~3.56 points (on a 100 base) — but only if the index has not fallen more than 40% from its starting level.
- Every quarter starting at month 6, if the index is back at or above its starting level, the note is called away and you get your principal (100) back plus that quarter’s coupon. You simply lose the coupons you would have earned later.
- At maturity, if the note was never called: you get par (100) as long as the index is at or above 60% of its start. If the index is below 60%, your principal is reduced one-for-one with the index — e.g. an index down 60% returns only 40.
- Because the index is capped for you, any strong rally earns you nothing beyond the coupons — upside is fully given away.
Key Statistics
| Metric | Structured Product | Underlying (Total Return) | Risk-Free Rate |
|---|---|---|---|
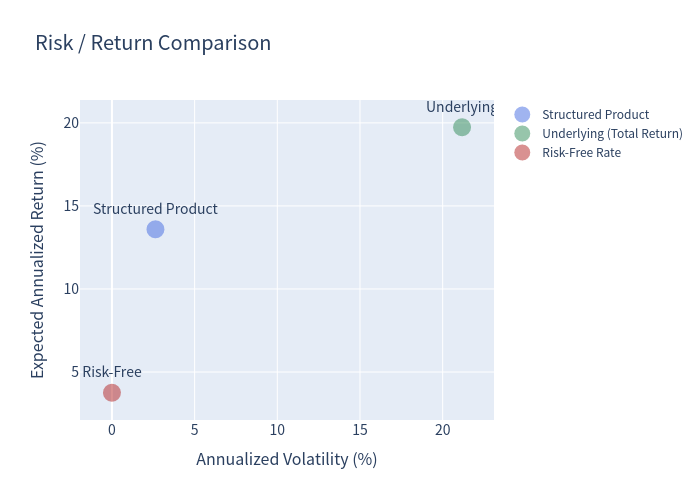
| Expected annualized return | 13.59% | 19.74% | 3.75% |
| Expected annualized volatility | 2.63% | 21.17% | 0.00% |
| Probability of loss | 1.28% | 5.07% | — |
| 99% confidence VaR (1 year) | -2.74% | -11.62% | — |
Charts
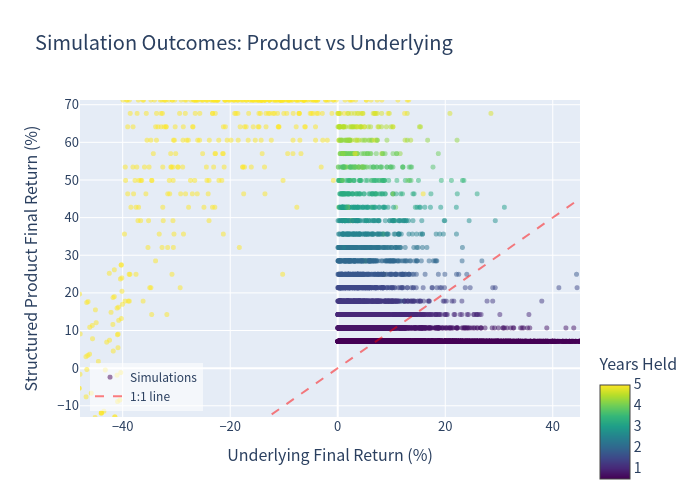
Simulation Outcomes — Product vs Underlying
Points below the dashed 1:1 line are the cost of the capped upside and the barrier; points above reflect the coupon pickup. Short holding periods (dark dots) cluster at modest, positive outcomes — the typical fast-autocall case.
Annualized Return Histograms
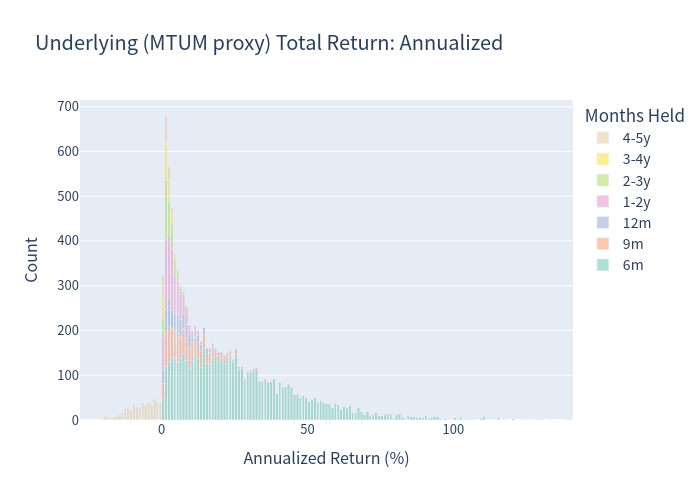
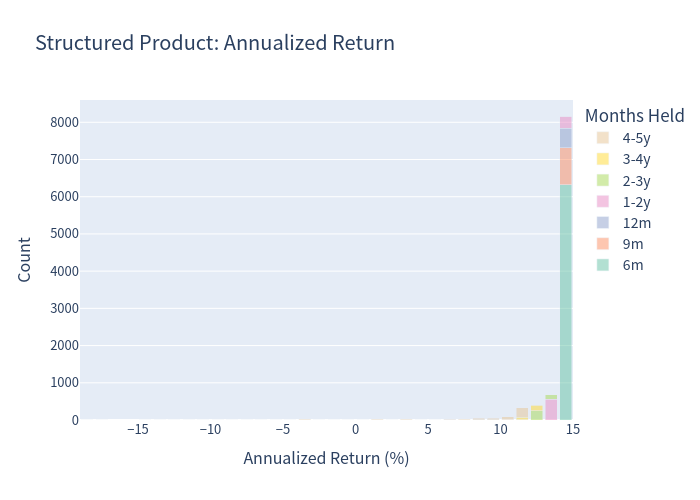
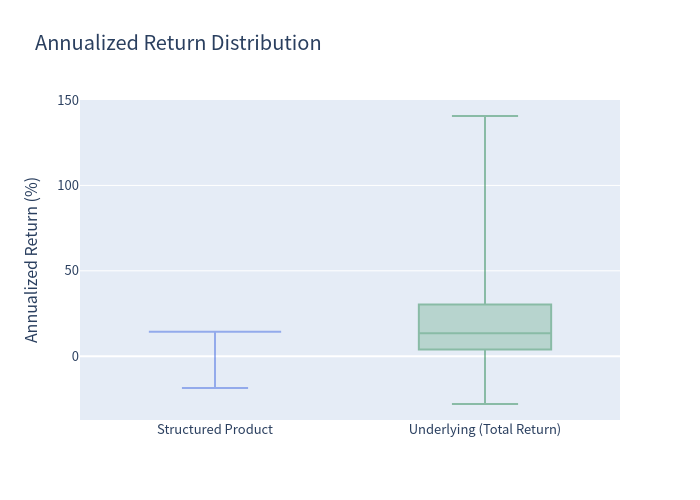
The product’s annualized return is tightly clustered in a narrow, high band (driven by short holding periods), whereas the underlying spans a wide range with a genuine left tail.
Risk / Return Comparison
Annualized Return Distribution (Box Plot)
Scenario Probabilities
Holding Period and Coupon Distributions
Investment Commentary
Attractive features
- Large headline coupon spread (~14.25% p.a.) versus the ~3.75% risk-free rate — the note earns roughly 10 points of spread if it keeps paying.
- Short effective duration in the base case: ~95% of paths are called early and ~63% redeem at the very first call date (month 6), so capital is typically returned quickly and reinvestment/credit exposure is brief.
- Soft downside cushion: as long as the underlier finishes at or above 60% of its start, principal is returned in full, and the coupon continues to be paid whenever the index is above 60%.
- Conditional (not guaranteed) income means coupons stop only when the market has already fallen hard (below 60%).
Points to weigh
- The upside is entirely capped — you give away all appreciation above 100% and only receive coupons.
- Principal is at risk below 60%: a full 1-to-1 downside means an index down 60% returns only 40, and down 100% returns 0.
- Autocall asymmetry: the note is most likely to be redeemed just when the market is strong, forcing reinvestment at the (likely lower) prevailing coupon, while it lingers longest precisely when the market has fallen.
- Concentration / leverage risk: the single underlier is a leveraged, volatility-targeted momentum index with a 4% decrement that drags performance in both up and down markets, and only a short track record.
- Return framing: because ~63% of paths redeem at 6 months, annualized figures are inflated by the linear annualization of short-horizon returns. Interpret the 13.54% expected total return over a ~13-month average holding period together with the headline annualized number.