Multi Barrier Reverse Convertible on ABB, Nestlé, Novartis, Roche
9.70% p.a. Coupon · Worst-of 4 names · Callable · CHF · Maturity 28/06/2028
Headline Simulation Results
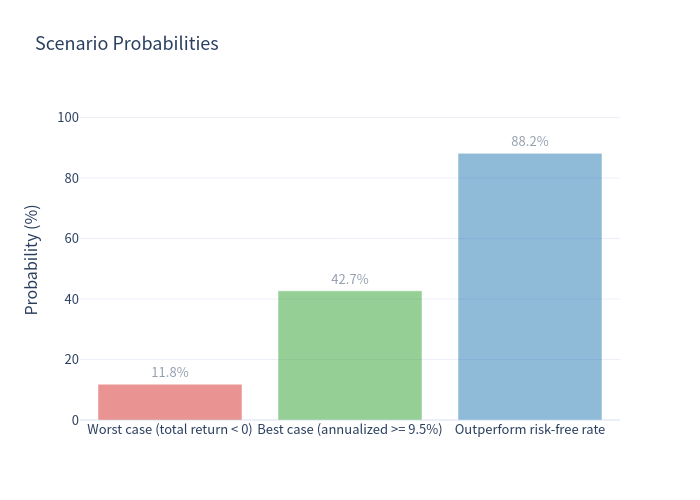
The note pays a fixed 9.70% p.a. coupon as long as it is outstanding, in exchange for accepting worst-of downside exposure with a 59% protective barrier. Over 10,000 simulated scenarios the strategy produced a positive total return in about 88% of paths, but the loss tail is meaningfully deeper than simply holding the underlying basket.
Scenario Probabilities
How It Works (plain language)
- Income first. You receive CHF 24.25 per CHF 1,000 (2.425 index points on a 100 notional) every quarter, regardless of how the four Swiss stocks (ABB, Nestlé, Novartis, Roche) perform.
- Conditional capital protection. Each share has a barrier at 59% of its starting level, watched continuously for the whole life of the note. If no share ever touches its barrier, you get your 100% back at maturity, plus all coupons.
- Worst-of downside. If any share touches its 59% barrier (a "barrier event"), the protection disappears and your redemption is driven by the worst-performing of the four names. At maturity, if that worst name is below its starting level, you receive its depreciated value (a capital loss); if it is back above its start, you still get par.
- Capped upside. You can never receive more than par plus the fixed coupons — gains beyond the coupon are given up.
- Issuer call. The issuer may call the note early on any of five quarterly dates, redeeming at par plus the then-current coupon.
Key Statistics (10,000-path simulation)
| Metric | Structured Product | Underlying (EW basket, total return) |
|---|---|---|
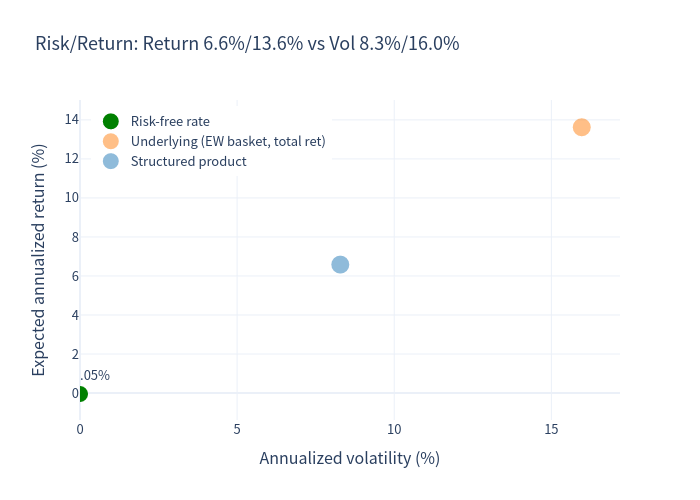
| Expected annualized return | 6.58% | 13.62% |
| Expected annualized volatility | 8.28% | 15.97% |
| Probability of loss | 11.83% | 20.64% |
| 99% VaR (1 year) | -23.88% | -15.74% |
| Risk-free rate (CHF, 1-yr avg) | -0.05% | -0.05% |
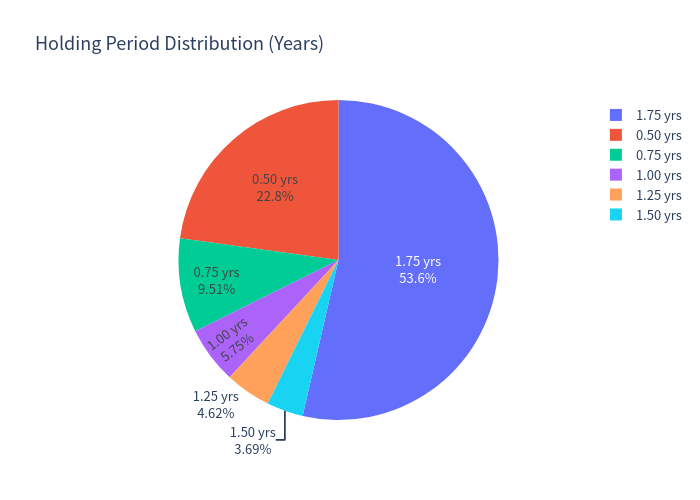
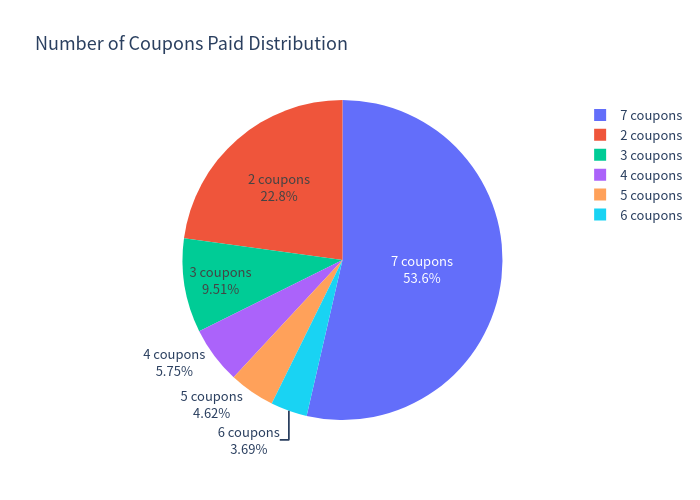
Holding & income profile: expected holding period 15.53 months (~1.29 years); expected total return over the realized holding period 7.57%; expected number of coupons paid 5.18. The note was called early in ~46% of paths (fully or partially offsetting a barrier breach), and a barrier event occurred in ~12% of paths. About 88% of outcomes returned par-plus-coupons (no capital loss).
Note: because ~32% of paths terminate before 12 months (early call), those per-path returns are annualized on a linear basis and can look inflated; they should be read together with the short holding period.
Simulation Charts
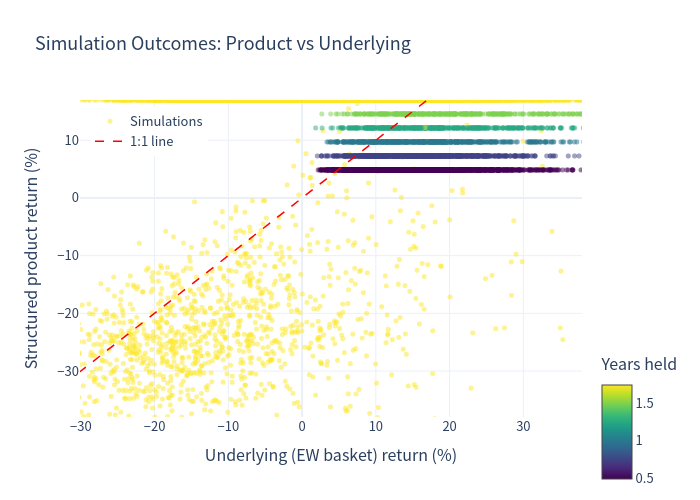
Outcome Scatter — Product vs Underlying
Each point is one simulation; the colour is the holding period in years, and the dashed line is 1:1.
Return Distributions
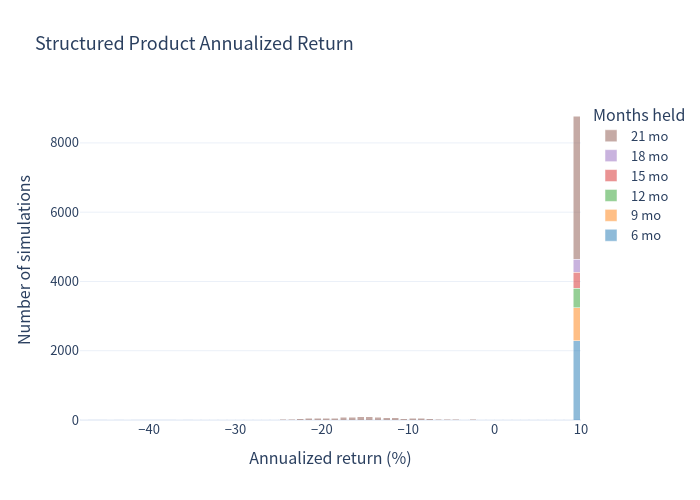
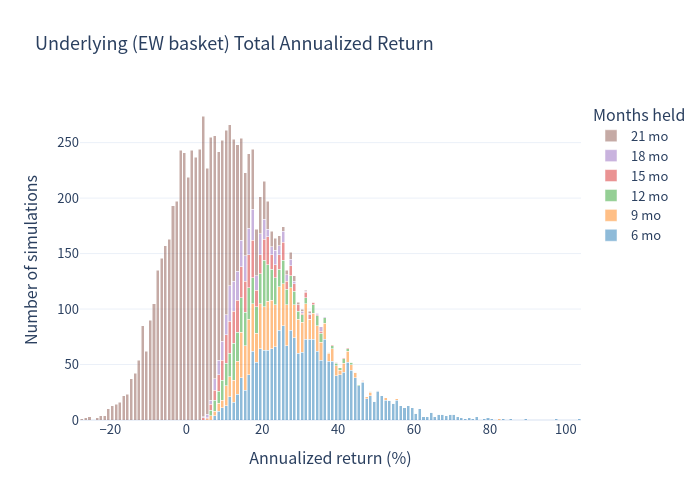
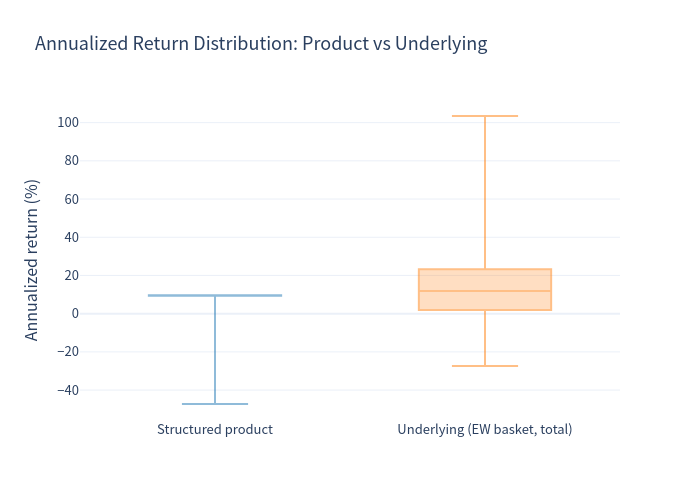
The structured product's annualized returns cluster tightly around the coupon cap (~9.7%), with a thin left tail from barrier breaches. The underlying basket spreads over a much wider range.
Risk vs Return
The note offers a lower expected return than the underlying but at roughly half the volatility.
Annualized Return Box Plot
Holding Period and Coupons
Investment Commentary
Strengths
- High, unconditional income: a 9.70% p.a. coupon paid every quarter, independent of market direction, while the note is alive.
- Meaningful downside buffer: the 59% barrier provides a 41% cushion on each name before the protection is lost — a relatively low barrier for a worst-of structure.
- Attractive risk-adjusted profile vs. the basket: roughly half the volatility of the equally weighted basket (8.28% vs 15.97%) with a materially lower probability of loss (11.83% vs 20.64%).
- Short maximum tenor (~21 months) and frequent early-call opportunities limit long-term market exposure.
Considerations
- Worst-of exposure: because the barrier and redemption look at the weakest of four names, breach probability is higher than for a single-name structure, and losses can exceed those of the basket (99% VaR -23.88% vs -15.74%).
- Continuous barrier: the barrier is observed at any time, so intraday/intramonth breaches count even if the share recovers.
- Capped upside & call risk: returns are limited to par plus coupons, and early redemption forces reinvestment at prevailing (potentially lower) rates.
- Issuer credit risk: repayment depends on the issuer's ability to pay.
Simulation-based estimates; figures are model outputs and not guarantees of future performance.