Market-Linked Notes on the EURO STOXX 50® Index — Investment Analysis
Headline Simulation Results
| Metric | Structured Product |
|---|---|
| Expected Annualized Return | 10.47% |
| Probability of Negative Return | 0.00% |
| 99% Confidence VaR (1 year) | 0.00% |
| Expected Total Return (over 4 years) | 54.15% |
The note is fully principal-protected at maturity: across 10,000 simulated paths, an investor who holds to maturity never loses principal. The downside is floored at 0% (return of the $1,000 stated principal), while the upside is leveraged by a participation rate.
Note on the two return figures. Expected Annualized Return (10.47%) is the average of each path's compound annual growth rate (CAGR). Expected Total Return (54.15%) is the average of each path's cumulative 4-year return. These are two different aggregation measures and are not required to satisfy (1 + 10.47%)⁴ − 1 = 48.9%; the gap reflects the well-known difference between the mean of a compounded series and the compounding of a mean (volatility drag).
Note on VaR. The 99% 1-year VaR of 0.00% is measured on held-to-maturity annualized returns, consistent with the product's principal protection (which applies at the maturity/observation date). It does not account for the risk of selling early in the secondary market, where the note may trade below principal. See the commentary for liquidity considerations.
Basic Product Information
What it is: A 4-year, non-interest-bearing note that guarantees the return of principal at maturity and offers leveraged exposure to the upside of the EURO STOXX 50® Index.
How it works (in plain terms)
- If the index rises over the 4 years, you receive your $1,000 principal plus 112% of the index's gain. For example, a 5% index gain pays $1,056 (105.6% of principal).
- If the index is flat or falls, you simply get your $1,000 principal back — no loss. "Under no circumstances will the payment at maturity be less than the stated principal amount."
- No coupon / interest is paid at any time; the entire return comes at maturity, based only on the index closing level on the observation date (Sept 30, 2030).
- No early redemption, no barrier, and no knock-in features exist.
Key assumption: The participation rate is quoted at 112%–117% and is fixed on the pricing date. This analysis uses 112% (the rate used in the issuer's own hypothetical examples). A rate of 117% would modestly increase returns.
Key Statistics (Annualized)
| Metric | Structured Product | EURO STOXX 50 (Total Return) |
|---|---|---|
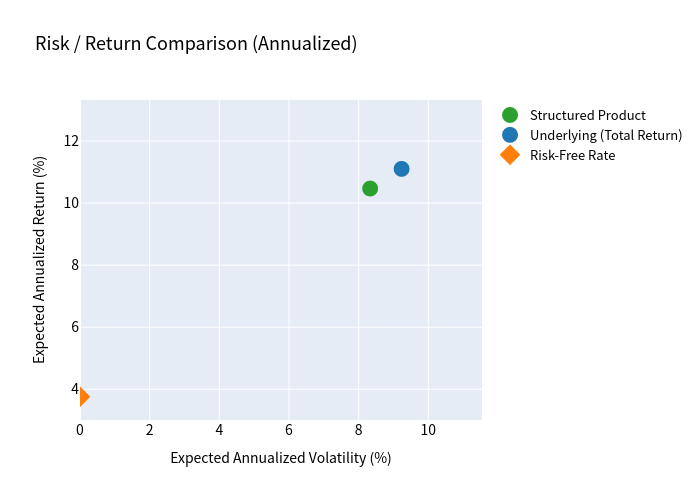
| Expected Annualized Return | 10.47% | 11.10% |
| Expected Annualized Volatility | 8.33% | 9.23% |
| Probability of Loss | 0.00% | 11.50% |
| 99% Confidence VaR (1 year) | 0.00% | −11.88% |
Risk-free rate used: 3.76% (1-year average 1Y U.S. T-bill). Underlying total return assumes a 2.51% dividend yield. Holding period is deterministic at 48 months.
The structured product delivers a comparable expected return to the underlying total return (10.47% vs 11.10%) but with lower volatility and zero principal loss (held to maturity) — the classic profile of a principal-protected note, which trades some upside participation and dividends for downside protection.
Charts
Simulation Outcomes vs Underlying
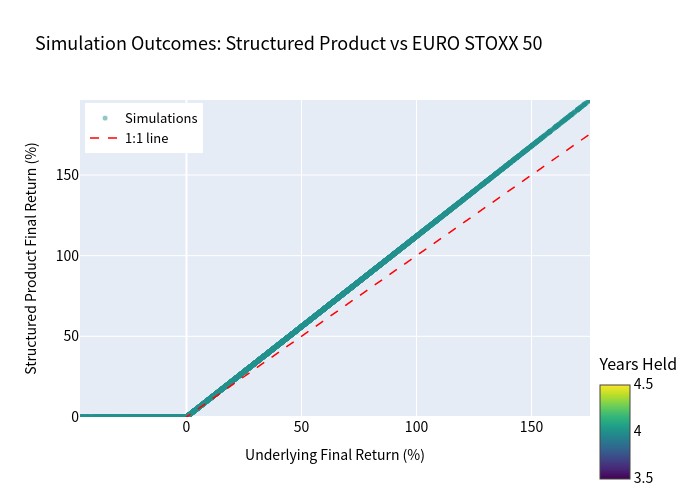
Each point is one simulation. The product sits on or above the 1:1 line: in every path it either matches or beats the underlying's price move because of the 1.12× upside leverage, and it never goes below 0%.
Underlying Annualized Return Distribution
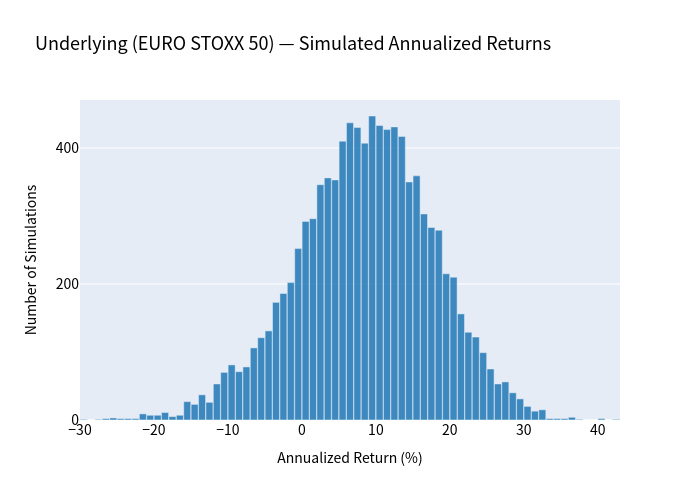
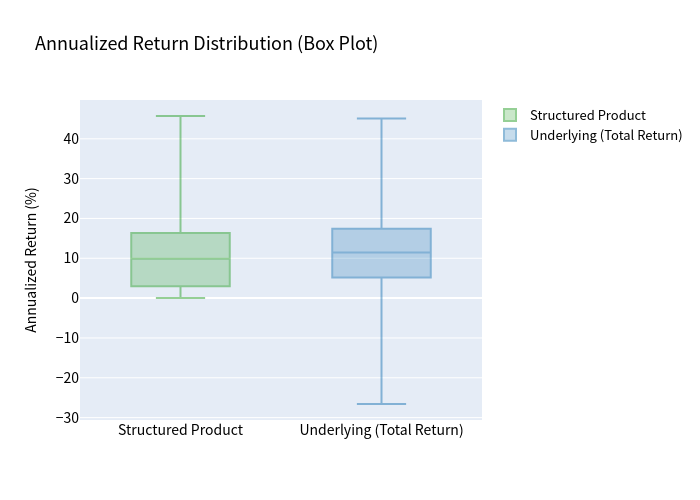
EURO STOXX 50 annualized returns are widely dispersed, with a visible left tail (losses).
Structured Product Annualized Return Distribution
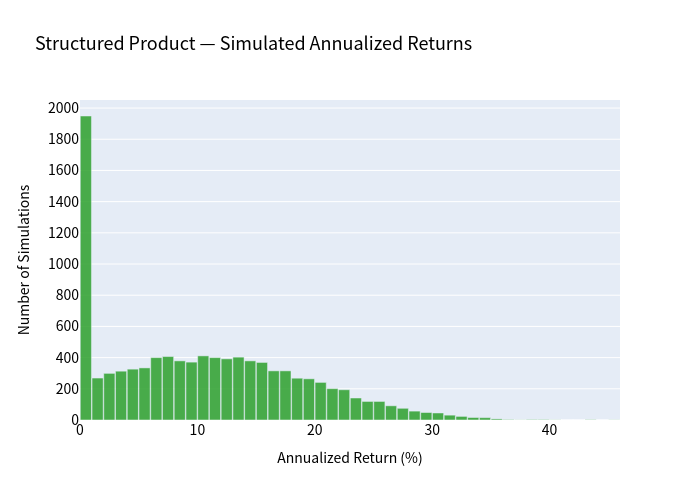
The product's return distribution is truncated at 0% — all negative outcomes are absorbed into a single spike at 0%, while the right side is amplified by the 112% participation.
Scenario Probabilities
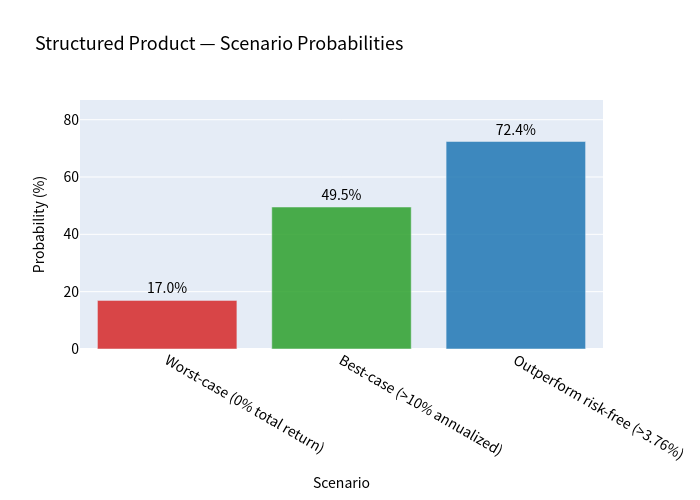
- Worst case (0% total return): 16.96% of paths finish flat or down (return of principal only).
- Best case (>10% annualized): 49.53% of paths.
- Outperform the risk-free rate (3.76%): 72.39% of paths.
Risk / Return Comparison
The product plots above the risk-free rate with moderate volatility, and achieves a slightly better risk-adjusted position than the underlying total return (lower volatility for a similar return).
Annualized Return Distribution (Box Plot)
Investment Commentary
Pros
- Full principal protection: Put-at-par behavior at maturity means the maximum loss is 0% — attractive for capital-preservation mandates.
- Leveraged upside: The 112% participation rate captures more than a full unit of index upside, and there is no cap on the return.
- Favorable asymmetry: Approximately 72% of simulated paths beat the risk-free rate, and roughly half deliver a double-digit annualized return.
- Credit exposure is to Morgan Stanley (guarantor), an investment-grade institution.
Cons / Considerations
- No income: The note pays no coupon, so in a flat or declining market the investor earns 0% and receives no compensation for time or inflation.
- Opportunity cost vs. total return: The expected return (10.47%) is slightly below the underlying's total return including dividends (11.10%) — the cost of the principal guarantee.
- All-or-nothing on the observation date: The return depends solely on the index level on Sept 30, 2030, not on any interim high, so a late sell-off can eliminate accumulated gains.
- No liquidity / early-sale risk: The notes will not be listed, and principal protection applies only at maturity; secondary-market pricing may be at a discount and the 0% VaR does not cover early sale.
- Credit risk: Payments depend on the issuer's/guarantor's ability to pay.
Summary
A 4-year, fully principal-protected, uncapped market-linked note on the EURO STOXX 50® Index with 112% upside participation. Simulated expected annualized return of 10.47% with 0% probability of loss and 0% one-year 99% VaR (held to maturity), versus 11.10% expected and −11.88% 99% VaR for the index total return. The structure sacrifices a modest amount of expected return (and all dividends) in exchange for complete downside protection at maturity and leveraged upside.