Morgan Stanley Jump Notes with Auto-Callable Feature due November 1, 2033
Simulation-Based Evaluation
Headline Simulation Results
| Metric | Result |
|---|---|
| Expected annualized return | 11.82% |
| Probability of a negative return | 0.00% (fully principal protected) |
| 99% confidence VaR (1 year) | 0.00% |
| Expected total return over the realized holding period | 17.20% |
| Expected holding period | ≈ 1.62 years (19.4 months) |
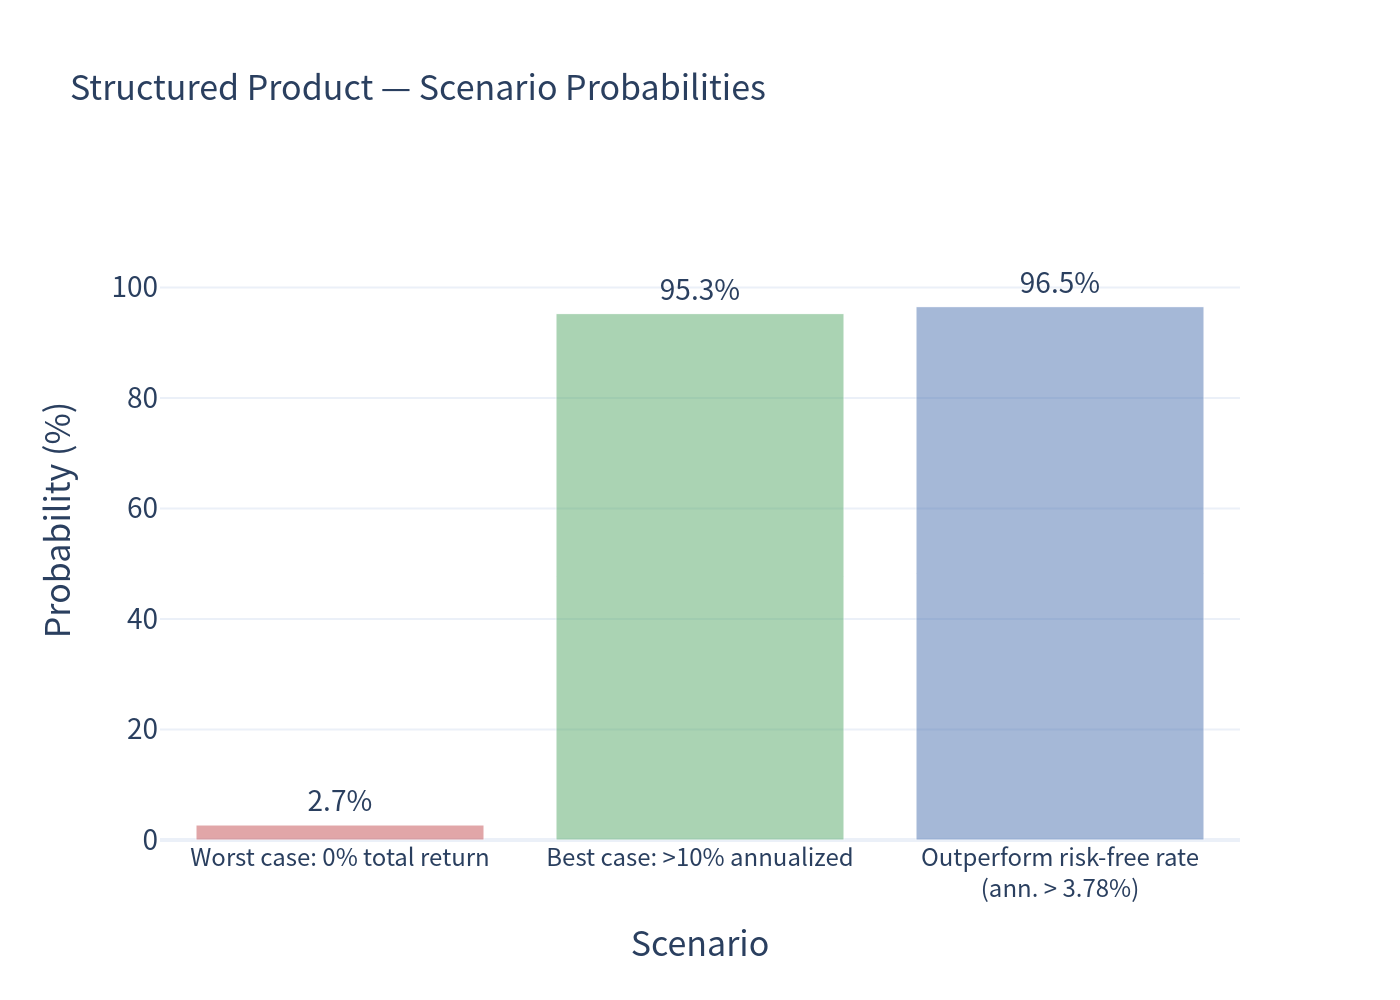
| Probability of outperforming the risk-free rate (3.78%) | 96.53% |
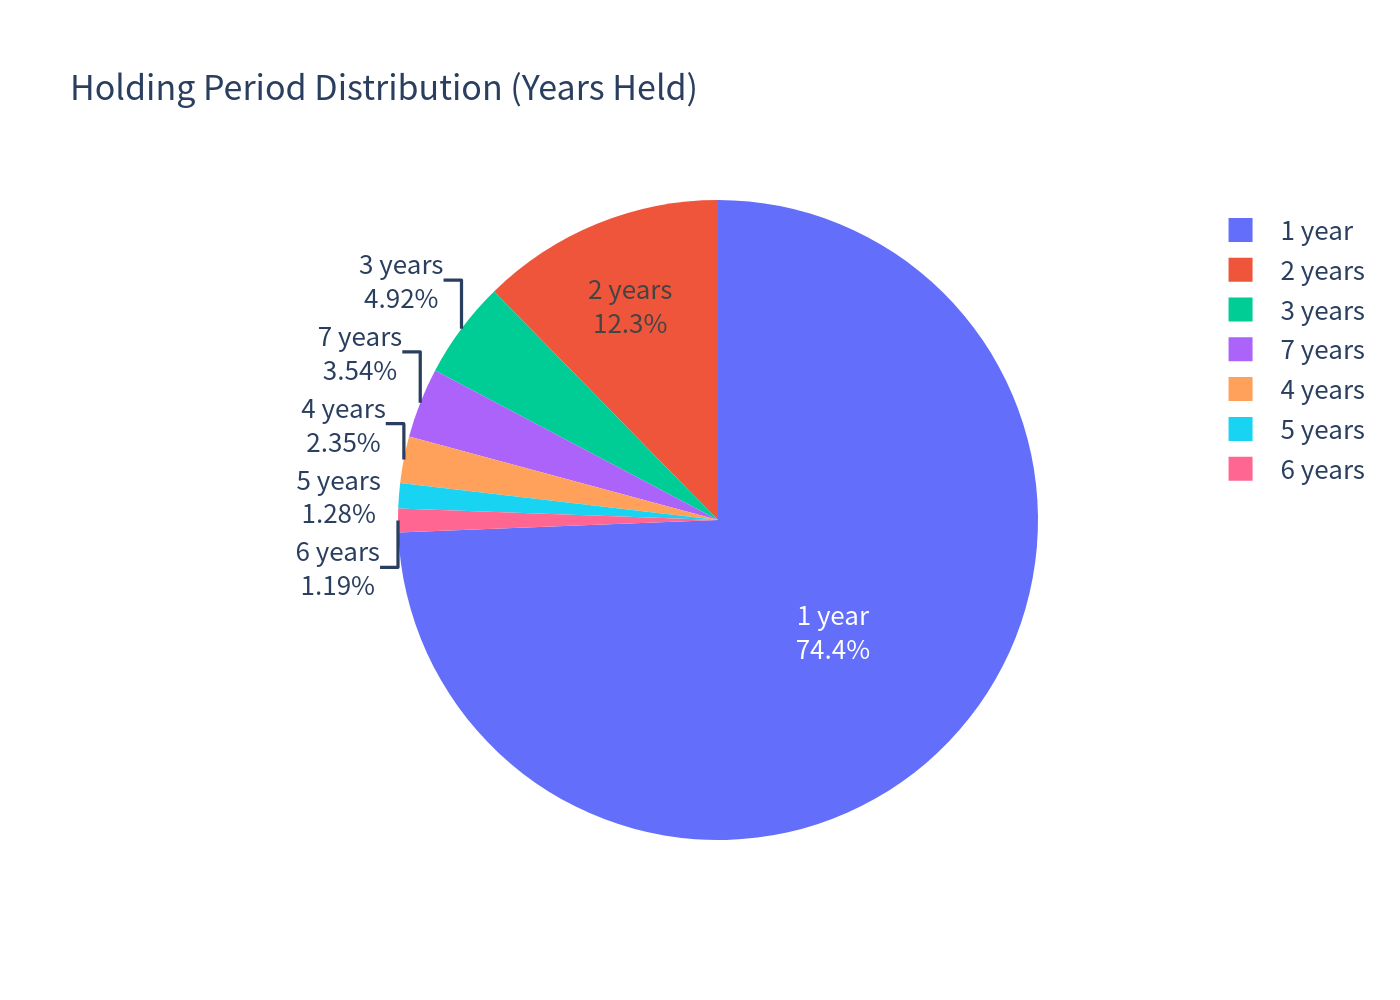
The note is a principal-protected, auto-callable "Jump" note. Because principal is protected, the strategy cannot produce a negative total return — the simulated loss probability is literally 0.00%. The trade-off is that returns are capped whenever the note auto-calls: the very best outcome is the first-year call premium of 12.50% (annualized), which the simulation hits in roughly three-quarters of paths.
Product at a Glance
| Issuer / Guarantor | Morgan Stanley Finance LLC / Morgan Stanley |
|---|---|
| Product type | Principal-protected auto-callable note ("Jump Note") |
| Underlier | Morgan Stanley Amplitude Index (single proprietary index)* |
| Term | ≈ 7 years (maturity November 1, 2033) |
| Periodic coupons | None — the note pays no interest |
| Auto-call premium | ≈ 12.50% per annum (simple, stepped) |
| Auto-call trigger | Index ≥ 101% of its initial level on an annual determination date |
| Upside participation | 100%, uncapped (at maturity only) |
| Downside | Principal protected — payment at maturity is never below the $1,000 stated principal |
* The Morgan Stanley Amplitude Index is a proprietary, non-publicly-quoted index with no accessible price history. For this analysis the S&P 500 index is used as a broad-market proxy for the underlier. All figures below are therefore proxy-based and should be read as illustrative.
How it works (plain language)
- You pay $1,000 for a 7-year note that pays no interest along the way.
-
Once a year (years 1–6), the issuer checks the index level:
- If the index is at or above 101% of where it started, the note is automatically redeemed and you receive a fixed premium that grows with time — about $1,125 after year 1, $1,250 after year 2, … up to $1,750 after year 6 (a flat ≈12.50% per year, not compounded).
- If the index is below 101%, the note keeps running.
-
If the note is never auto-called, it matures after 7 years:
- If the index finished higher than it started, you receive your $1,000 plus 100% of the index gain.
- If the index finished flat or lower, you simply get your $1,000 back.
In short: your downside is capped at zero, but early-redemption upside is capped at the stepped 12.5%-per-year premium.
Key Simulation Statistics
| Metric | Structured Product | Underlying (S&P 500 proxy, total return) |
|---|---|---|
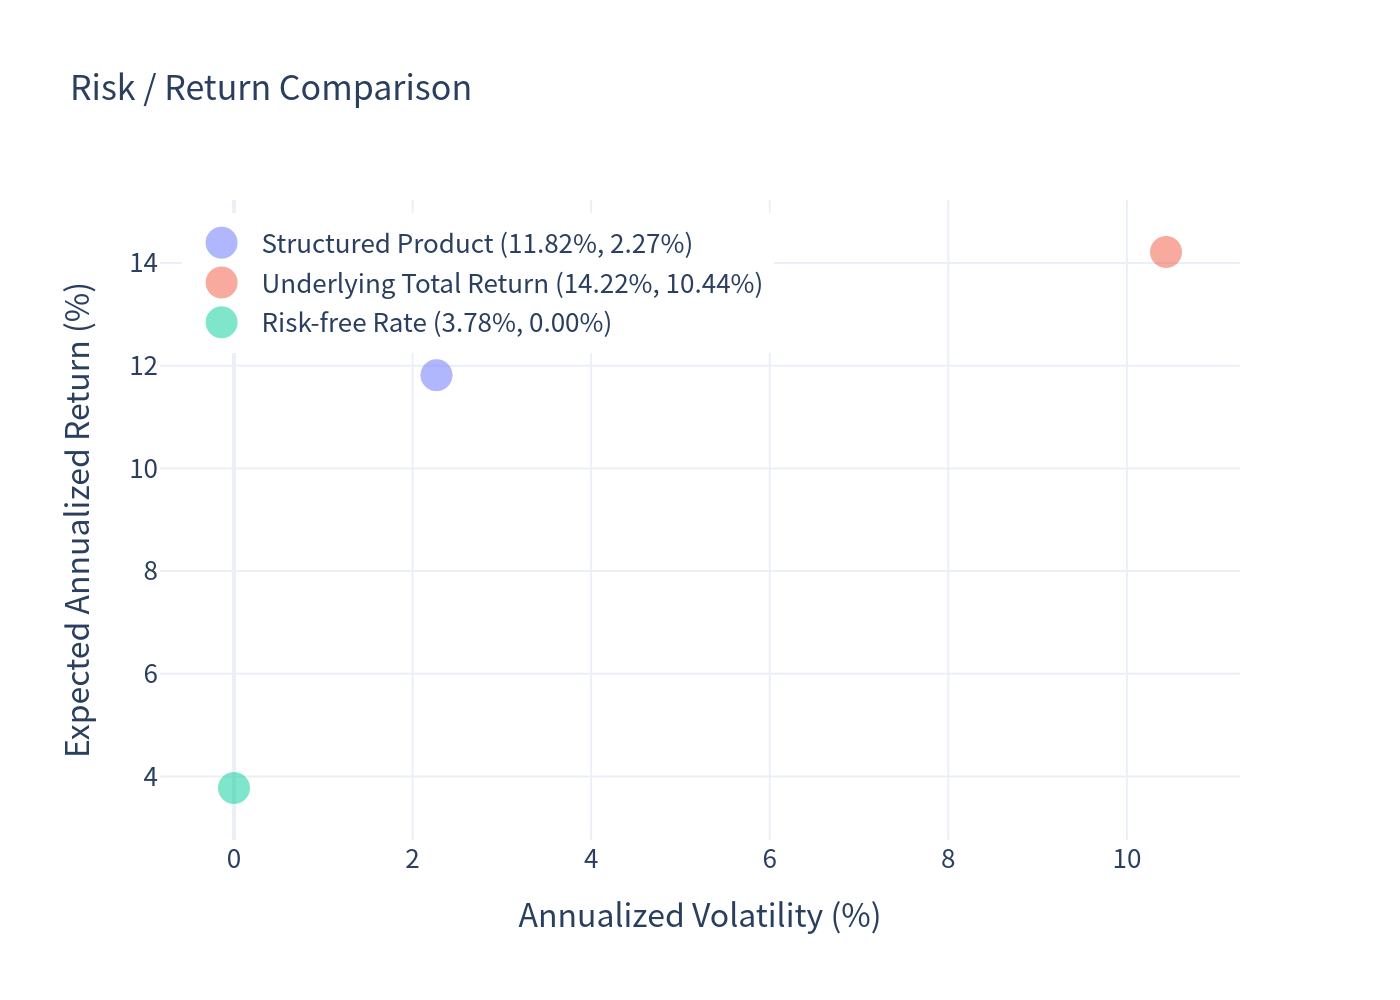
| Expected annualized return | 11.82% | 14.22% |
| Expected annualized volatility | 2.27% | 10.44% |
| Probability of loss | 0.00% | 2.29% |
| 99% confidence VaR (1 year) | 0.00% | −4.45% |
Additional observations
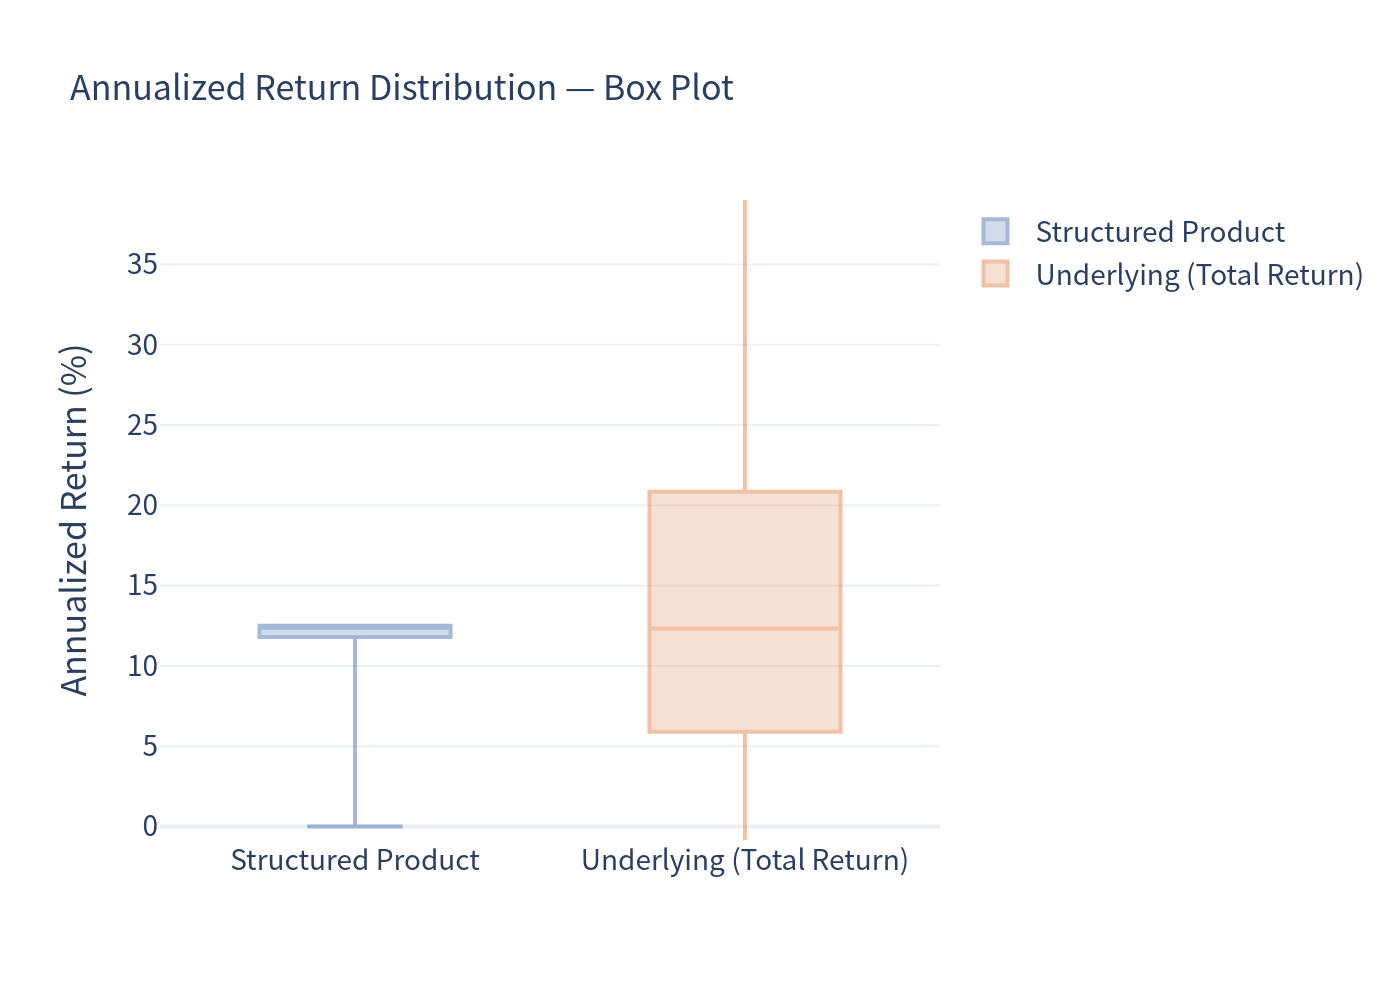
- Median annualized return: 12.50% (the first-year call premium).
- Probability the note beats the price-only underlying: 53.38%; vs the total-return underlying (dividends added): 48.78%.
- Probability of a zero total return (held to maturity with the index ≤ starting level): 2.71%.
- Because holding periods are short on average, annualized figures should be read together with the expected total return of 17.20% over ≈1.6 years — for the many paths that call in year 1, the annualized and total return are identical (12.50%).
Charts
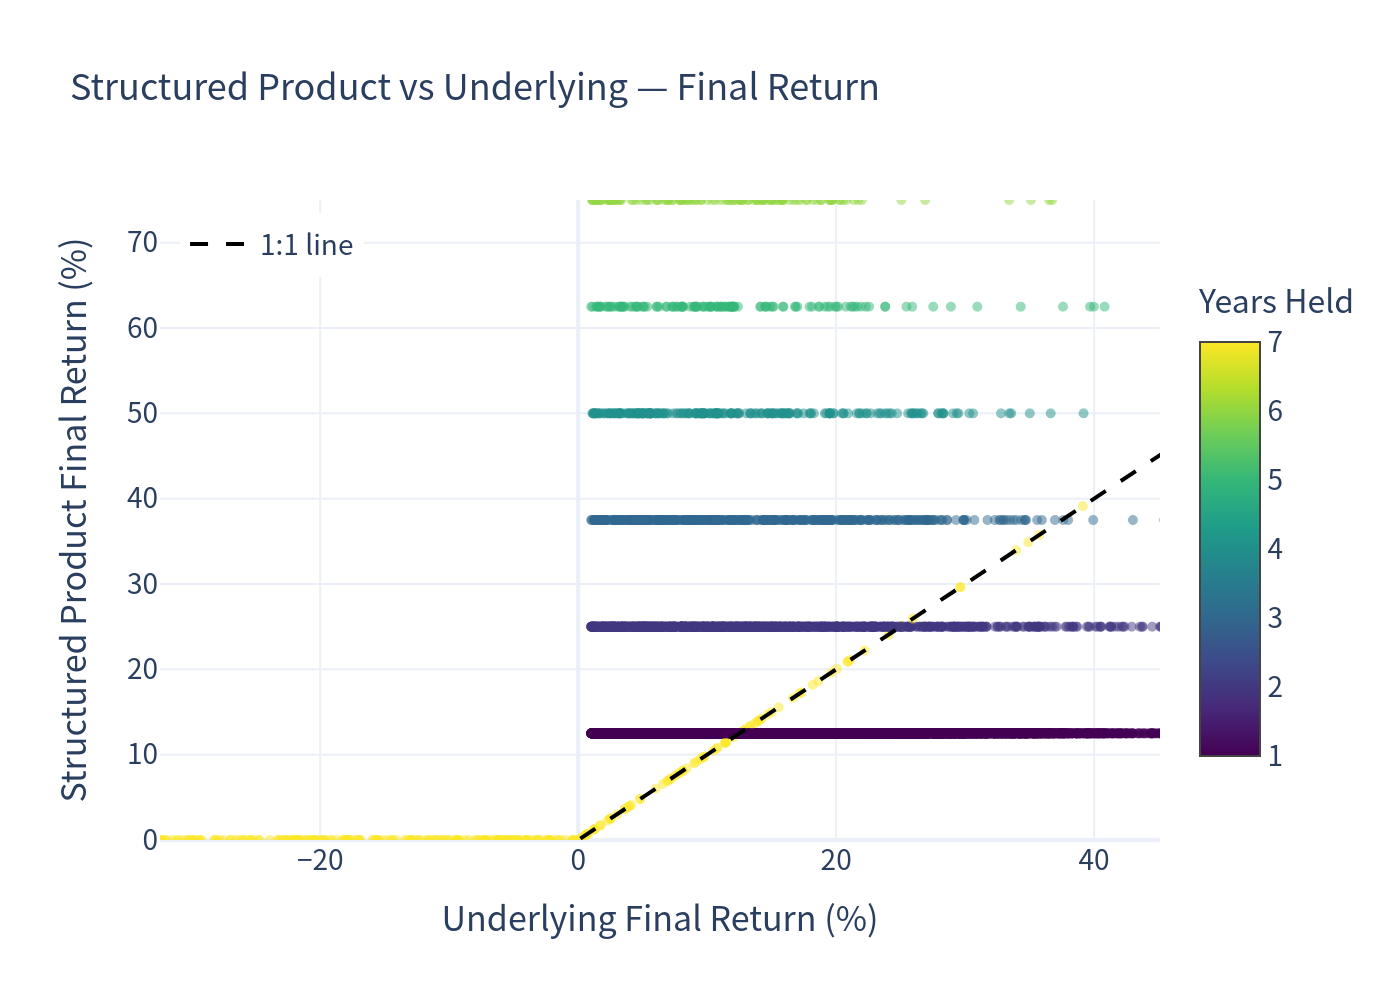
Final-return scatter — product vs underlier
Each point is one simulation. The product's return is floored at 0% (protection) and, for early redemptions, sits on flat horizontal "steps" (12.5%, 25%, …), while the underlying spreads widely.
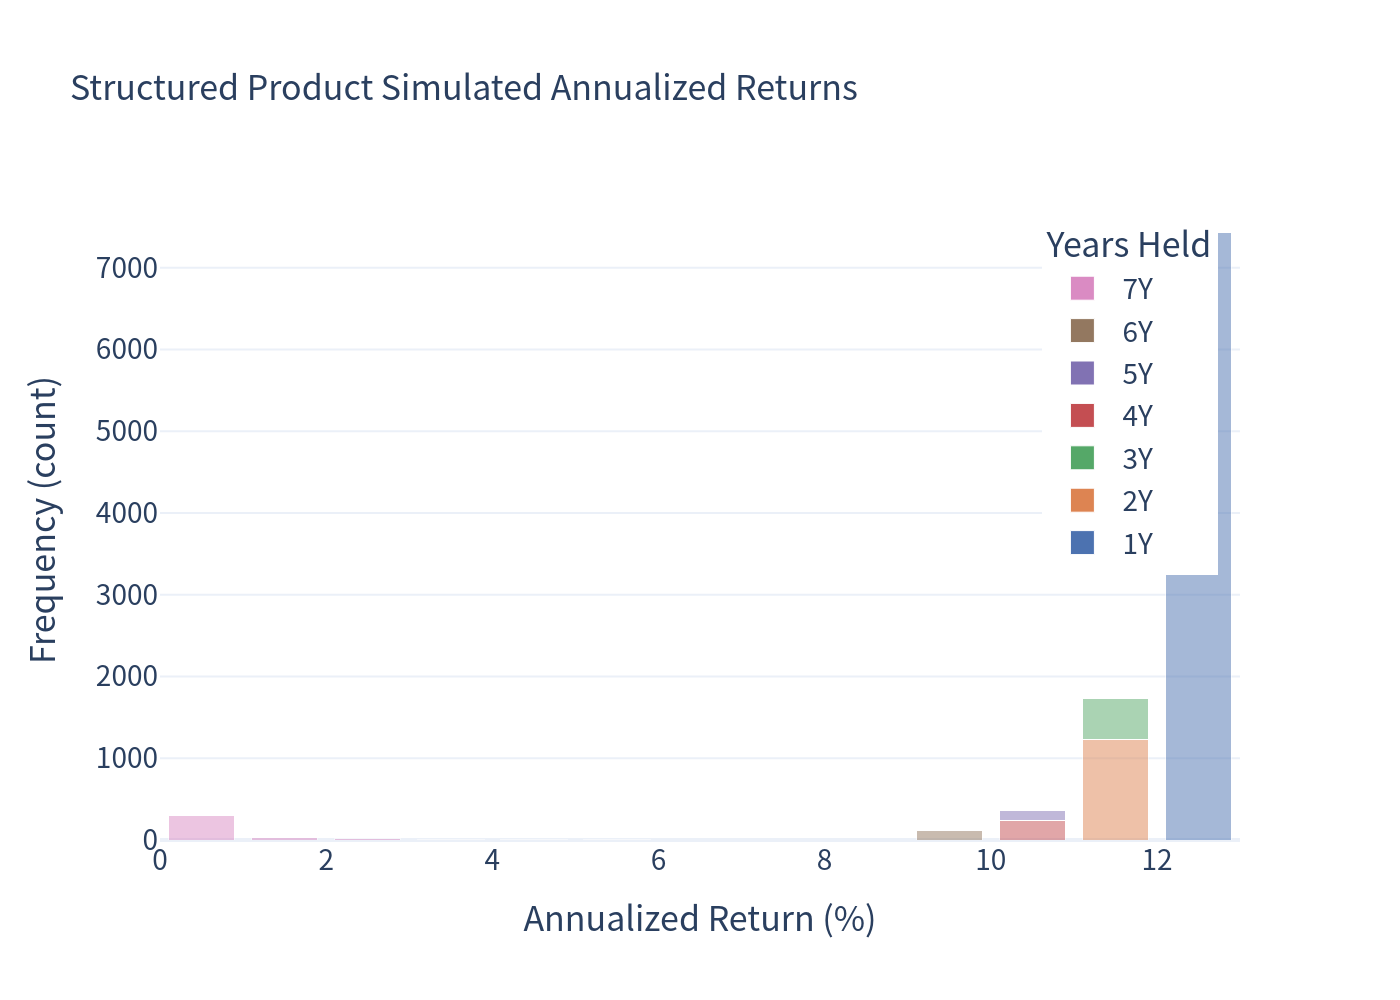
Simulated annualized returns — structured product
The distribution is tightly clustered: the vast majority of paths land on the 12.50% first-year call, with a small mass at 0% (no call, index ends flat/lower).
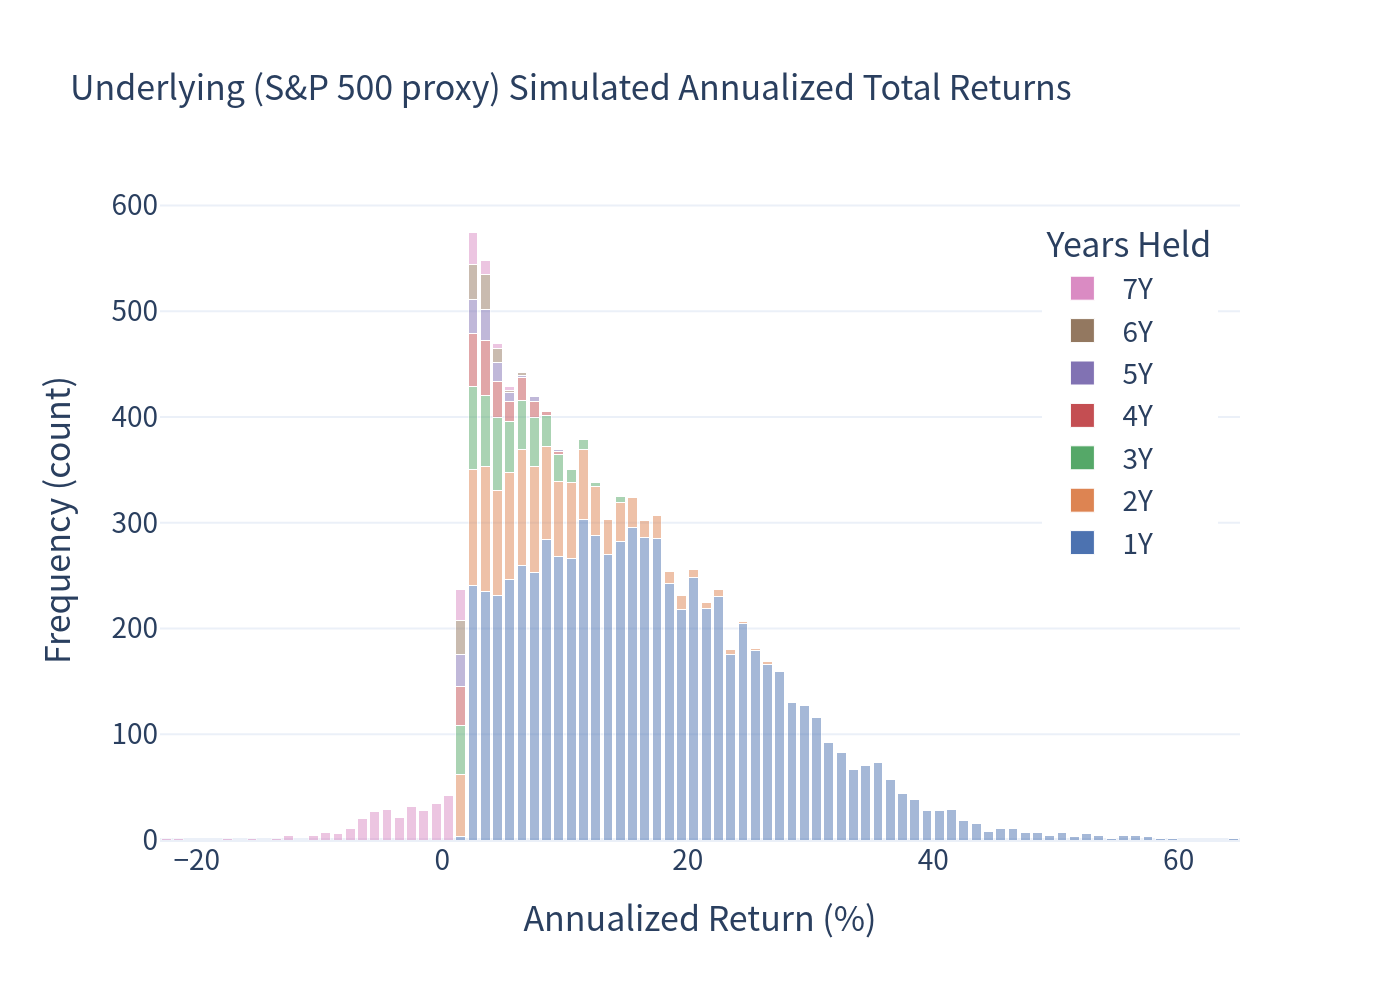
Simulated annualized returns — underlying (total return)
A wide, roughly bell-shaped distribution centred in the low-teens, with a meaningful negative tail that the structured product does not share.
Scenario probabilities — structured product
Risk / return comparison
The product sits far to the left (very low volatility) and just below the underlying's expected return — the classic shape of a principal-protected, capped-upside structure.
Annualized-return box plot
Holding-period distribution
Investment Commentary
Potential strengths
- Capital protection: the note returns at least the $1,000 principal at maturity, so total-return outcomes are bounded below at zero — a genuine feature in a drawdown scenario.
- Attractive fixed step-up in flat-to-modestly-up markets: any index level ≥ 101% of the start triggers a 12.50%-per-annum payoff, even if the index has barely moved.
- Uncapped upside if held to maturity: unlike many autocallables, a strong 7-year run is not capped by the maturity payoff (100% participation).
- Very low return volatility (2.27% annualized in simulation) relative to the ≈10% of the underlying.
Considerations / trade-offs
- Return is capped when the market rallies early: the best annualized outcome is 12.50%, and the note is very likely (≈74% of paths) to call after just one year — so a sustained bull market is largely missed and reinvestment risk is high.
- Opportunity cost in strong markets: the simulated expected annualized return (11.82%) sits below the underlying's total return (14.22%); the product wins on a risk-adjusted basis but not on raw expectation.
- No income: the note pays no coupons, so there is no cash flow for up to 7 years if it never calls.
- Flat-market outcome is 0% (≈2.71% of paths): if the index ends at or below its start and never crosses 101%, you earn nothing over the full term.