Structured Product Evaluator | info@tokenengine.ai
Morgan Stanley SX5E Market-Linked Notes due October 3, 2030 — Simulation Report
Headline Simulation Results
Based on a 4-year, month-by-month Monte Carlo simulation (10,000 paths) of the EURO STOXX 50® Index (SX5E):
| Metric | Structured Product | Underlying (Total Return) |
|---|---|---|
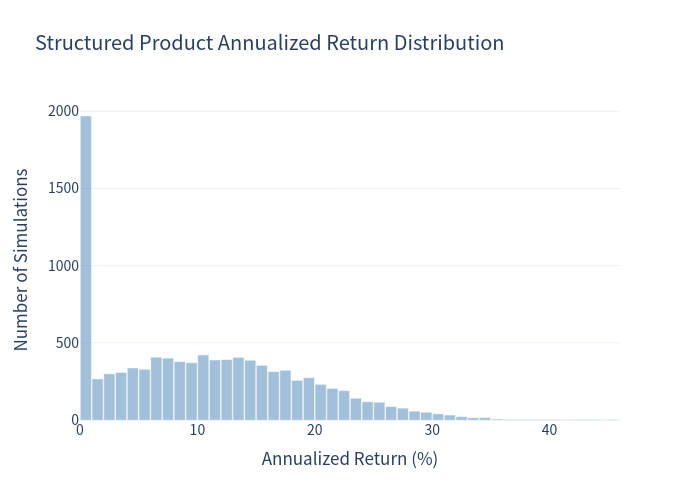
| Expected annualized return | 10.42% | 11.05% |
| Expected annualized volatility | 8.31% | 9.23% |
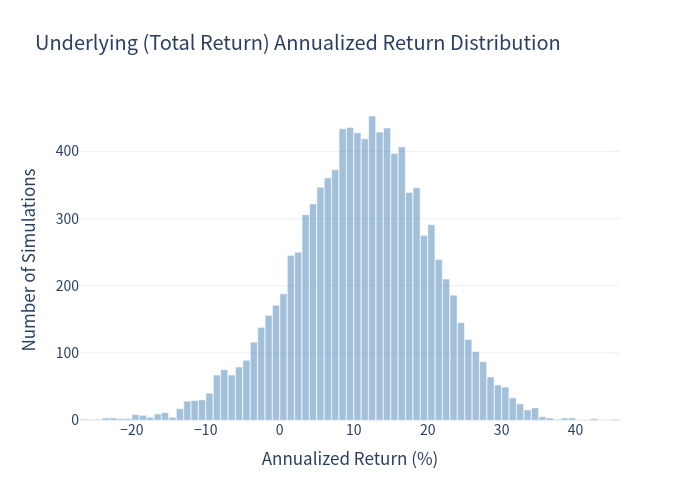
| Probability of negative return | 0.00% | 11.57% |
| 99% confidence VaR (1 year) | 0.00% | −11.93% |
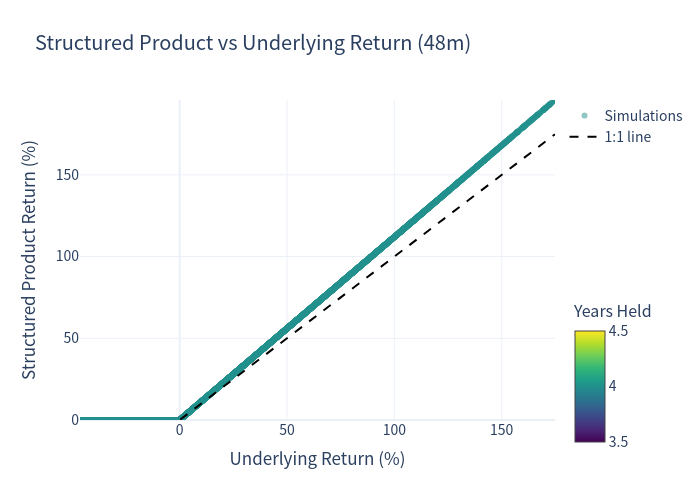
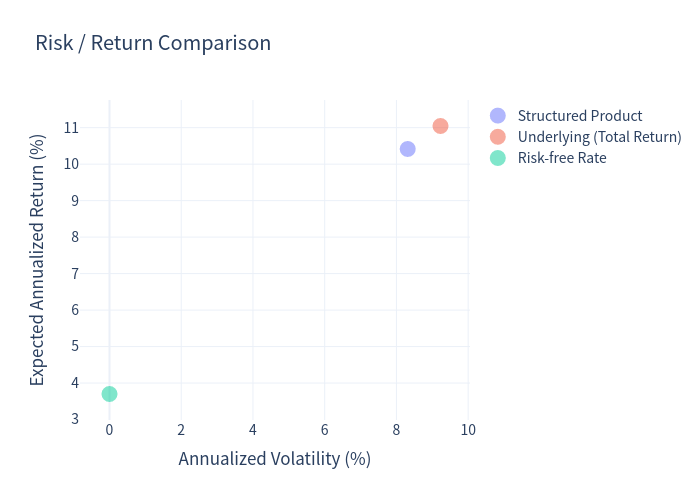
- Expected annualized return: 10.42% — driven by 112% participation in the index's upside.
- Probability of negative returns: 0.00% — the notes are 100% principal protected, so an investor never receives less than the Stated Principal Amount.
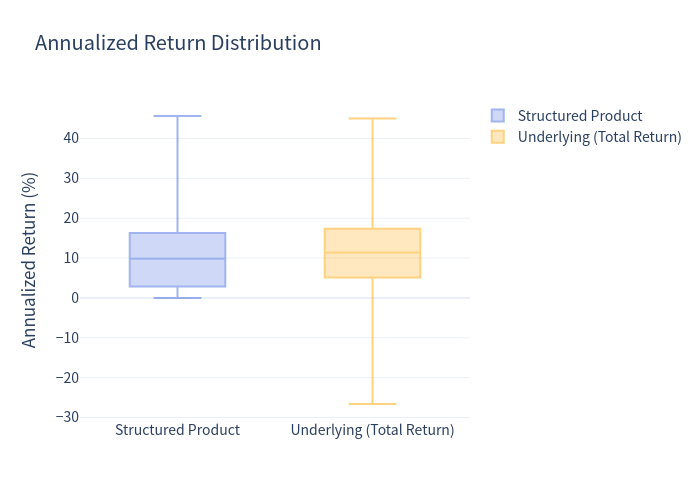
- 99% confidence VaR (1 year): 0.00% — even in the worst 1% of scenarios there is no loss of principal; the downside outcome is simply a 0% return.
Because the note always matures after 48 months (a single observation date), the holding period is fixed at 4 years; annualized and total-return figures are directly comparable. (Note: the product's 0.00% 1-year VaR assumes the note is held to maturity, where principal protection applies; an investor selling before maturity could realise a market value below par.)
What the Product Is and How It Works (Layman's Explanation)
This is a principal-protected equity-linked note linked to the performance of the EURO STOXX 50® Index over roughly four years:
- At maturity the investor receives the Stated Principal Amount ($1,000 per note) back regardless of how the index performs — even if the index falls 50% or 100%.
- If the index rises over the term, the investor additionally receives 112% of the index's percentage gain.
- If the index is flat or falls, the investor simply receives the principal back — no interest, no loss.
- There are no coupons (the notes pay no interest), no early-redemption/autocall feature, and no upside cap.
In short: full downside protection in exchange for giving up dividends and any interim interest, with leveraged participation on the upside.
Key Statistics
| Metric | Structured Product | Underlying (Price) | Underlying (Total Return, +2.51% div.) |
|---|---|---|---|
| Expected annualized return | 10.42% | 8.54% | 11.05% |
| Expected annualized volatility | 8.31% | 9.23% | 9.23% |
| Probability of negative return | 0.00% | 17.20% | 11.57% |
| 99% VaR (1y, 1st percentile) | 0.00% | −14.44% | −11.93% |
| Expected total return over 4 years | 53.83% | 44.74% | — |
Risk-free rate (1-year average T-bill): 3.70%.
Scenario probabilities (structured product)
Charts
Simulation Outcomes vs Underlying
Annualized Return Distributions
Scenario Probabilities
Risk / Return Comparison
Return Distribution Box Plot
Investment Commentary
Pros
- Capital protection: The note returns at least the Stated Principal Amount at maturity, eliminating downside market risk to principal (subject to the issuer's credit risk).
- Leveraged upside: A 112% participation rate lets investors capture slightly more than the index's gain, with no cap on the upside.
- Favourable risk-adjusted profile: The note delivers a comparable expected annualized return (10.42%, marginally below the underlying's 11.05% total return) with materially lower volatility (8.31% vs 9.23%) and a strongly compressed downside (0.00% vs 11.57% probability of loss) — a better return-per-unit-of-risk.
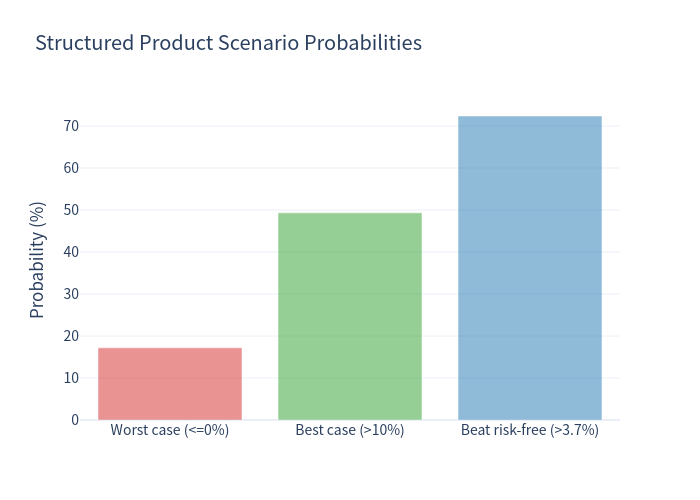
- High probability of beating cash: In ~72% of simulations the note out-earns the 3.70% risk-free rate, and it has a ~49% chance of delivering more than a 10% annualized return.
Cons / Trade-offs
- No income: The notes pay no coupons, so investors forgo any running yield.
- Dividends excluded: The payoff is based on the price index only; the ~2.51% annual dividend yield of the underlying is not passed through, which is the main reason the index's total return slightly edges out the note's return in expectation.
- Opportunity cost in flat/down markets: In ~17% of scenarios the index fails to rise and the investor merely gets principal back, underperforming a simple risk-free deposit.
- Credit and valuation risk: Payments depend on the issuer's creditworthiness, the notes are not exchange-listed, and the estimated value ($964.70) is below the issue price.
Summary
A 4-year, 100% principal-protected note on the EURO STOXX 50® Index offering 112% upside participation with no coupon and no cap. The simulated expected annualized return is 10.42% with a 0.00% probability of principal loss and a 0.00% 1-year 99% VaR, providing leveraged equity upside with effectively no downside risk to principal.