Step-Up Jump Notes with Auto-Callable Feature due November 1, 2033
Based on the Performance of the Morgan Stanley Amplitude Index™
Headline Simulation Results
| Metric | Result |
|---|---|
| Expected annualized return | 14.56% |
| Probability of a negative return | 0.00% |
| 99% confidence VaR (1-year) | 0.00% |
| Expected holding period | ≈ 1.63 years (≈ 19.6 months) |
| Expected total return over the realized holding period | 21.39% |
Basic Product Information
| Item | Detail |
|---|---|
| Issuer / Guarantor | Morgan Stanley Finance LLC / Morgan Stanley (full guarantee) |
| Underlier | Morgan Stanley Amplitude Index™ (a single, proprietary Morgan Stanley index) |
| Principal amount | $1,000 per note (issue price $1,000) |
| Term | ≈ 7 years (issue Oct 30, 2026 → maturity Nov 1, 2033) |
| Coupon | None — the notes pay no interest |
| Early redemption | Annual autocall, years 1–6 |
| Downside | Principal protected (floor = 100% of principal) |
| Upside | 100% participation at maturity (uncapped); autocall payment caps returns in years 1–6 |
How it works (in plain terms)
You buy a 7-year note for $1,000. There are no interest payments. Instead:
- Annual "call" check. On each anniversary (years 1 through 6), if the index is at or above a threshold that starts at 100.75% of its starting level and steps up by 0.75% each year, the note is automatically redeemed and pays you a fixed, pre-set amount that grows each year — about 15.50% per year on a simple basis ($1,155 in year 1, $1,310 in year 2, … up to $1,930 in year 6). After that, the note is done.
- If it is never called. At maturity you get your $1,000 back plus 100% of any rise in the index. If the index is flat or down, you simply get your $1,000 back.
So the note trades away large upside (in strong rallies it is called early for a modest fixed amount) in exchange for full protection of principal and a very attractive fixed rate when the index is even slightly positive at a check date.
Key Statistics
| Metric | Structured Product | Underlying (total return*) |
|---|---|---|
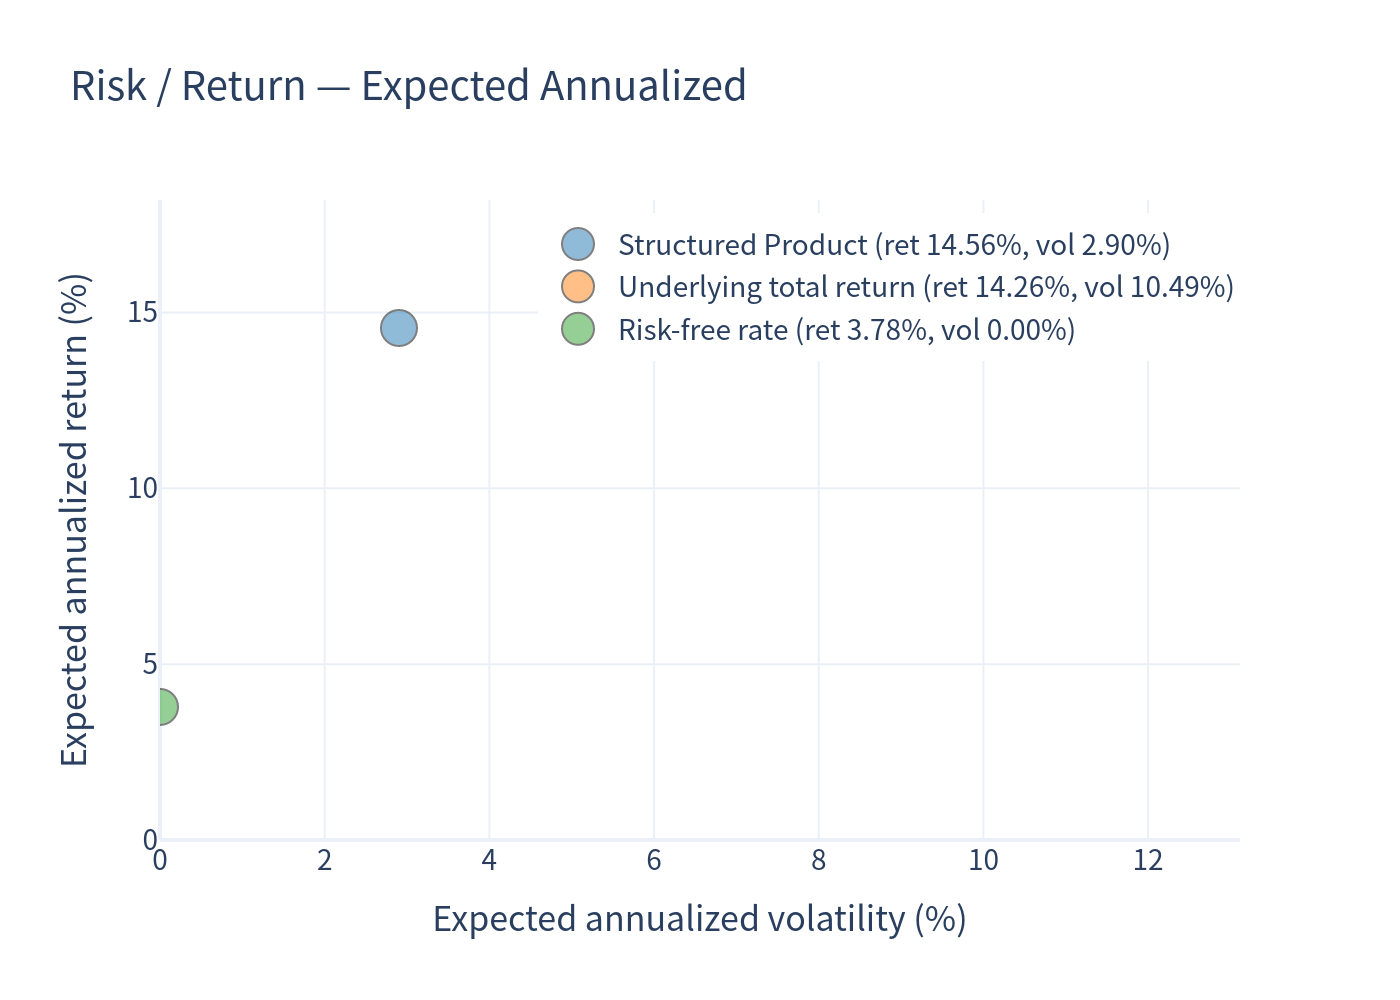
| Expected annualized return | 14.56% | 14.26% |
| Expected annualized volatility | 2.90% | 10.49% |
| Probability of loss | 0.00% | 2.21% |
| 99% confidence VaR (1-year) | 0.00% | −4.34% |
| Expected holding period | 1.63 years | — |
The structured product delivers a higher expected return at roughly one-quarter of the volatility of the underlying over the simulated horizon, with no simulated loss of principal. This asymmetry is the core appeal of the structure — but it is a direct consequence of the autocall feature capping upside and of assuming a positive forward equity drift.
Charts
1. Simulation outcomes — product vs underlying
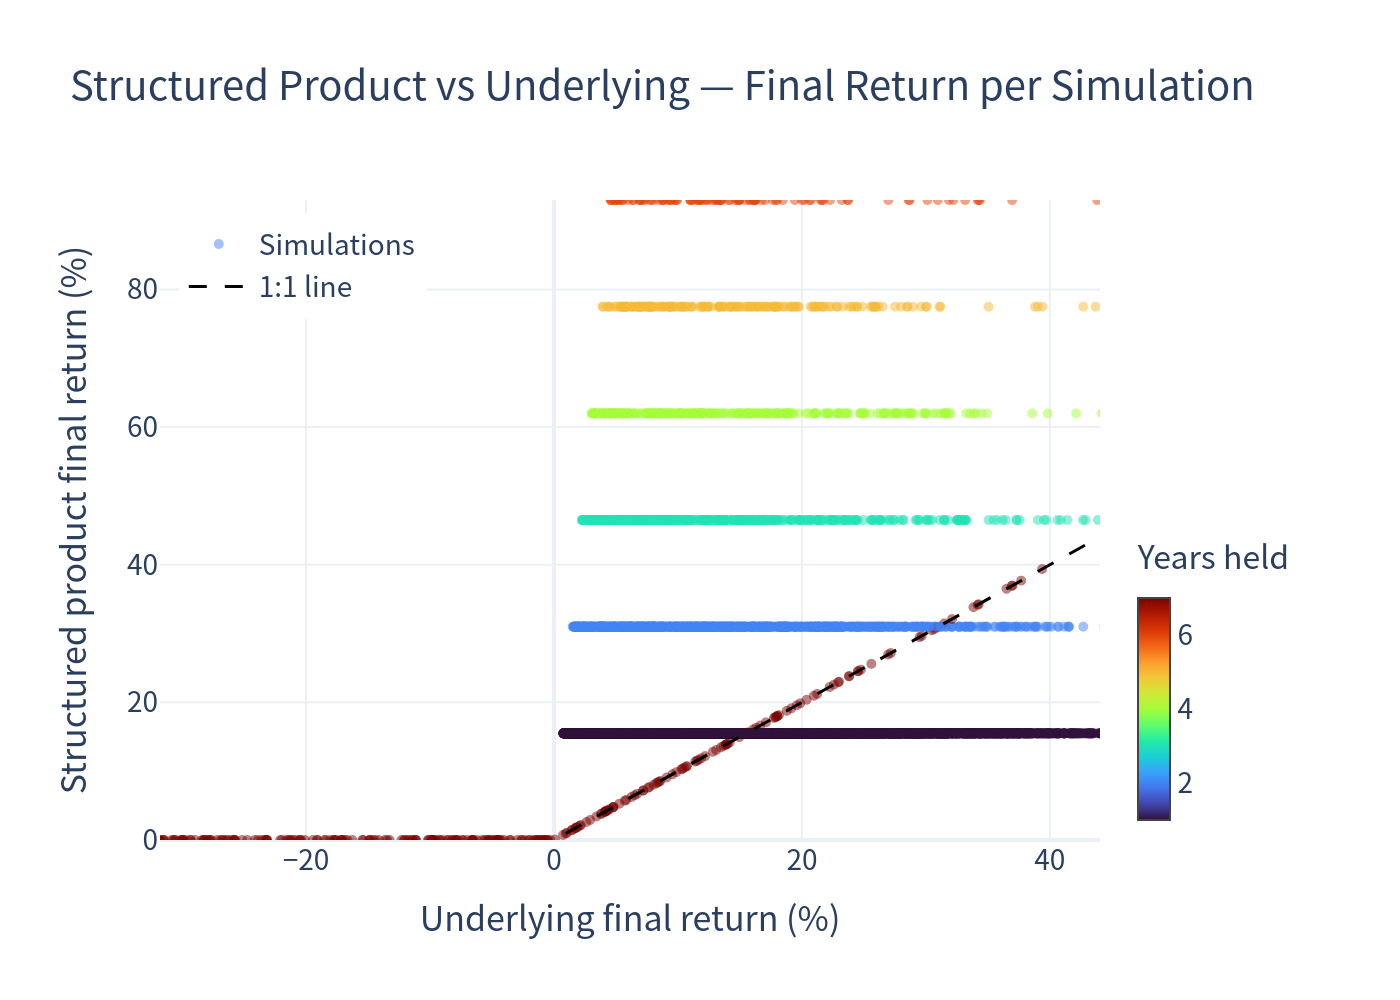
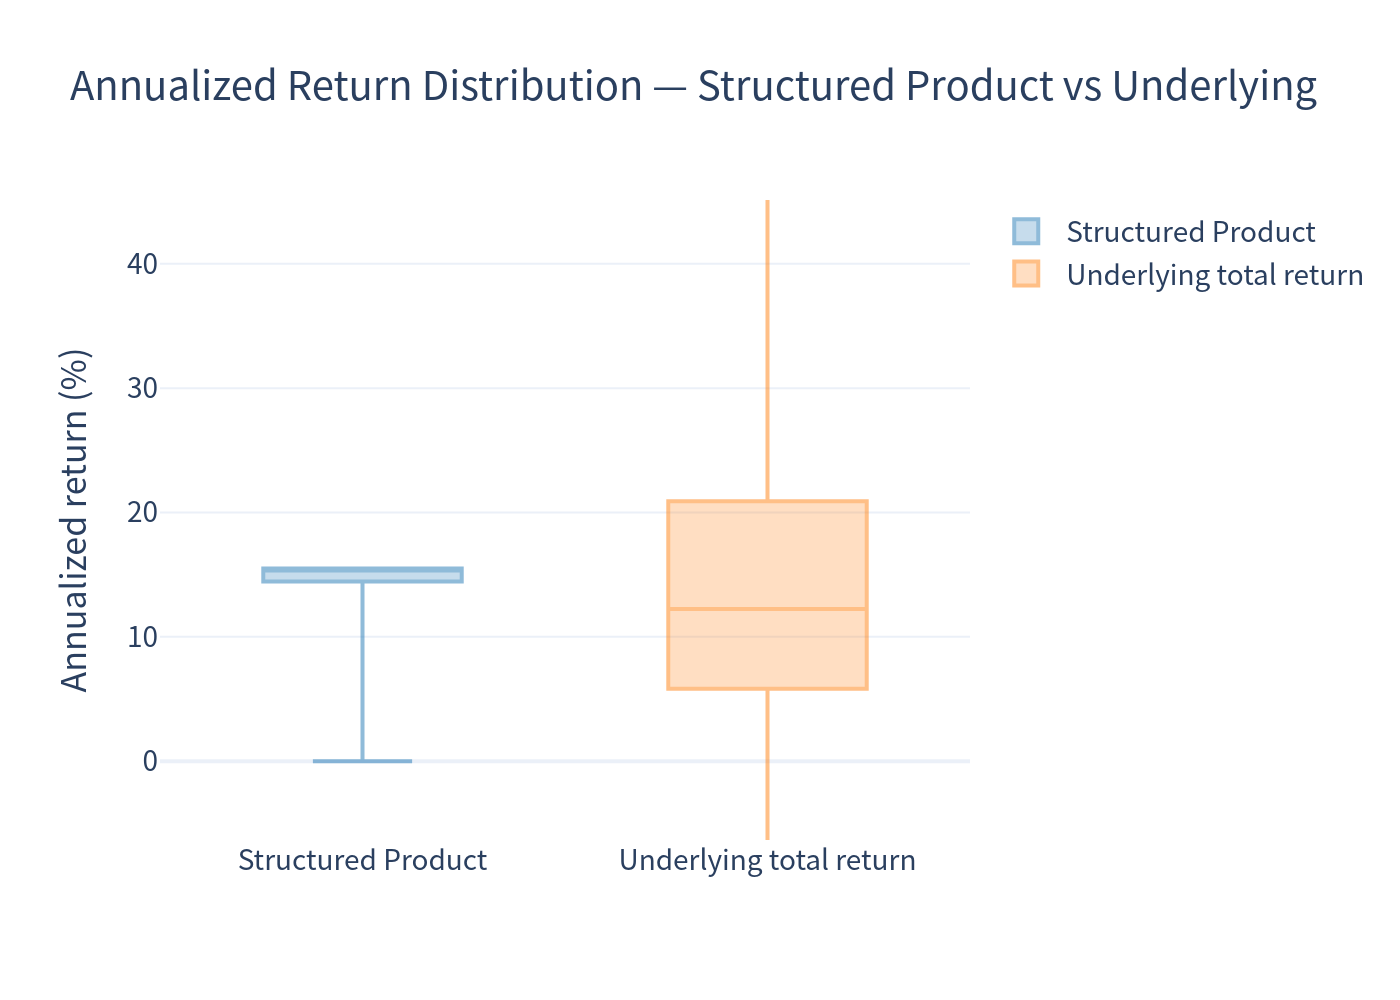
Each point is one simulation. Points sit on a flat band at 0% product return (the maturity floor when the index finishes at or below its start) and on horizontal bands at 15.50 / 31.00 / 46.50 / 62.00 / 77.50 / 93.00 (the six autocall payments). For any underlying outcome above a call threshold the product return is capped at the corresponding step-up payment — this is the "give-up" versus the 1:1 line.
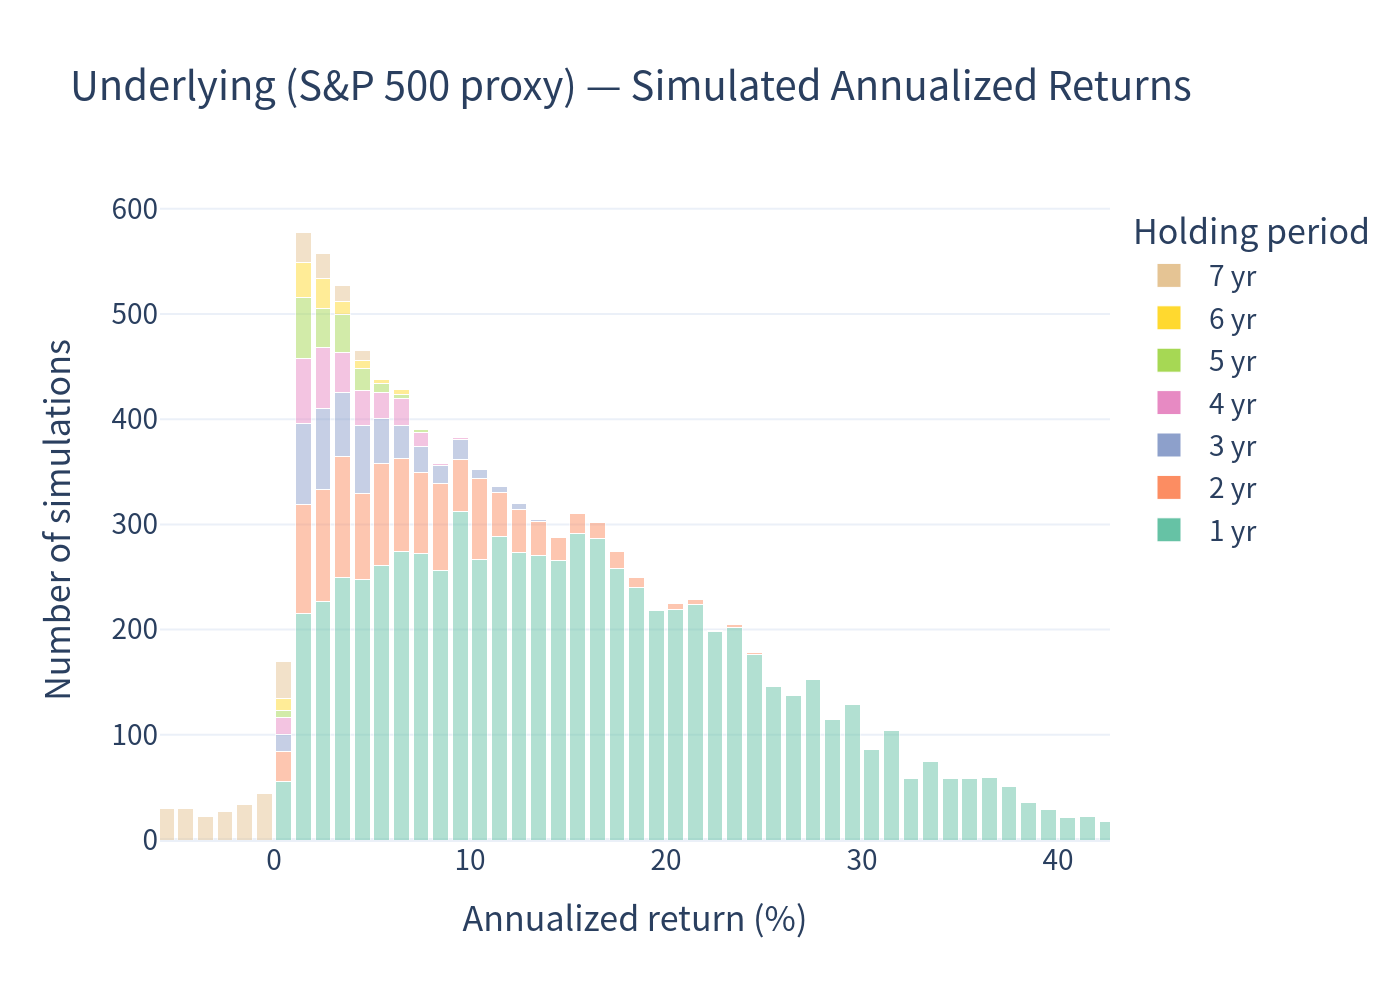
2. Underlying (S&P 500 proxy) — annualized return distribution
3. Structured product — annualized return distribution
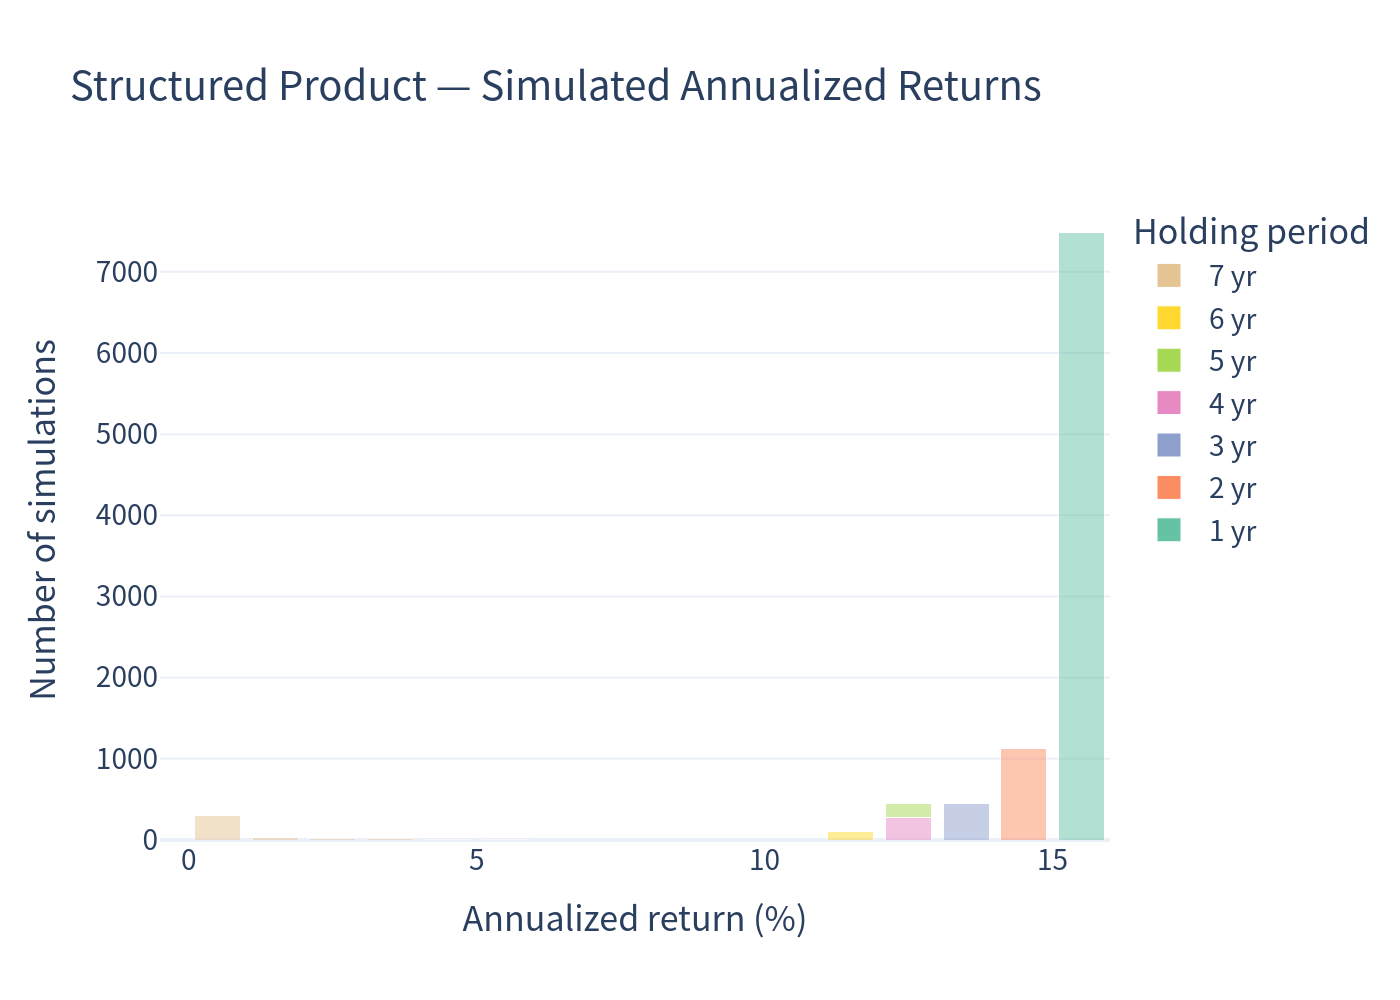
The product's distribution is entirely non-negative, with a dominant cluster around 15.50% (year-1 autocalls, 74.91% of paths) and a small mass at 0% (principal-only maturity, 2.65% of paths).
4. Scenario probabilities
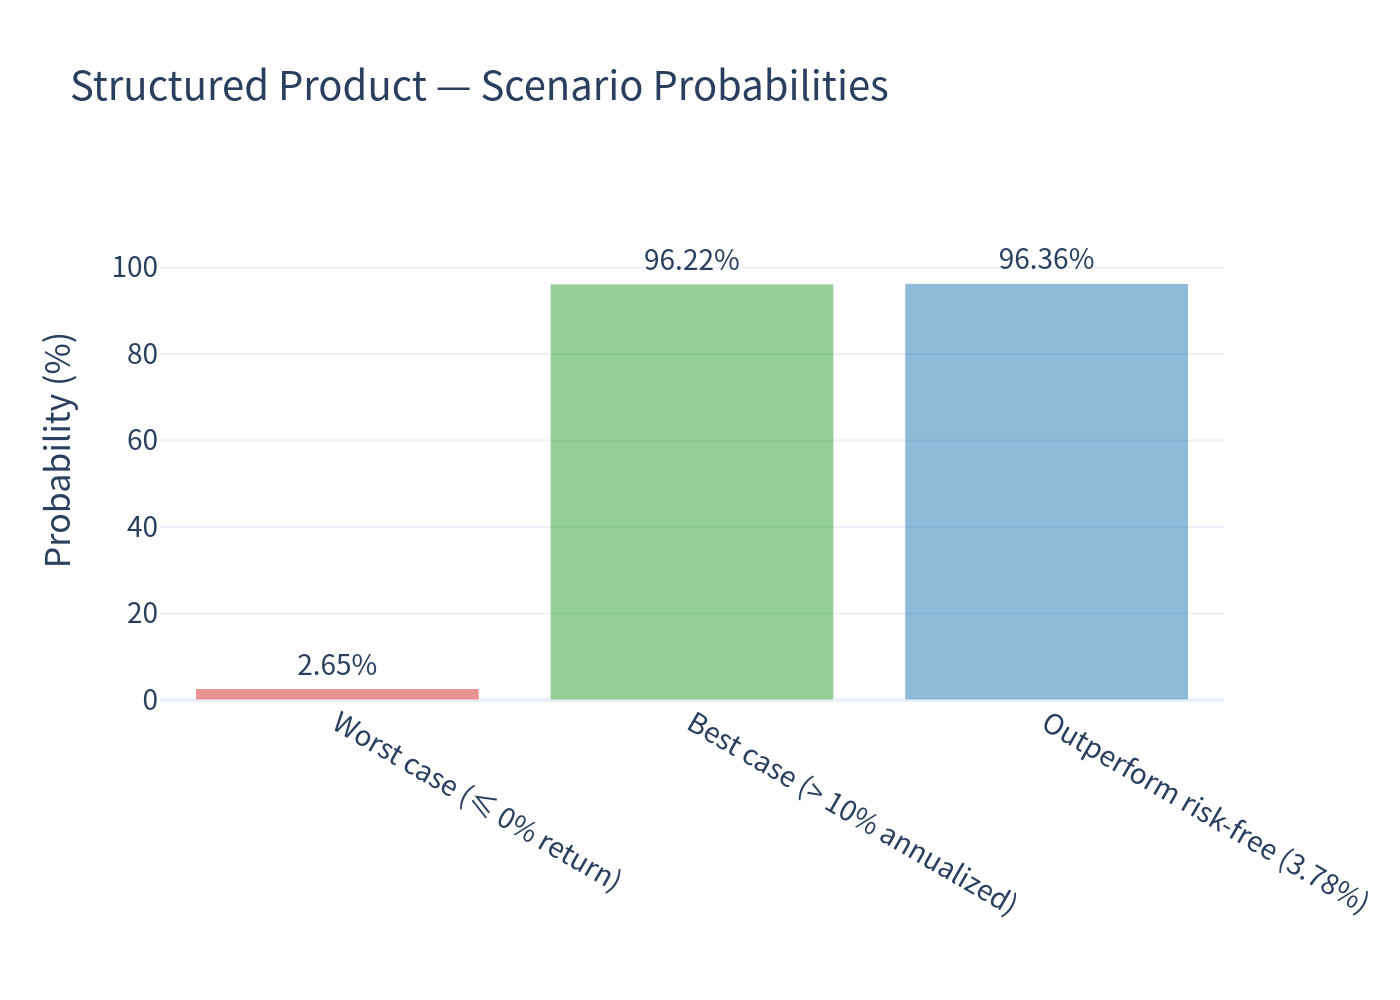
- Worst case (≤ 0% return): 2.65% — the note matures with the index at or below its start; principal is returned.
- Best case (> 10% annualized): 96.22%
- Outperforms the risk-free rate (3.78%): 96.36%
5. Risk / return positioning
6. Annualized return distribution — box plot comparison
7. Holding-period distribution
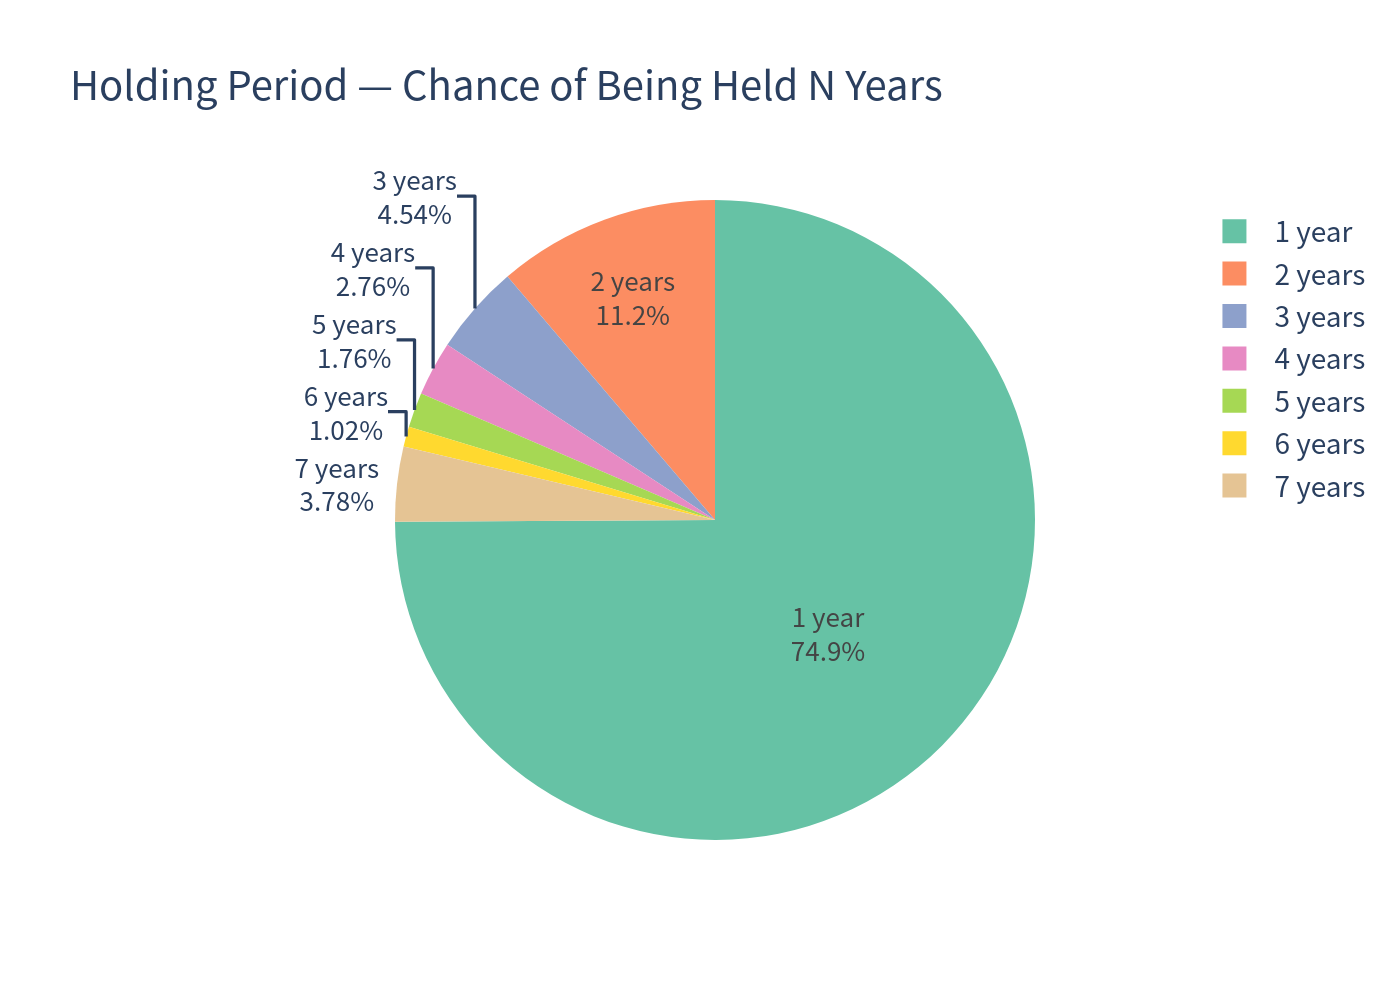
Because 74.91% of paths autocall at the very first determination date, the expected holding period is only ~1.63 years — meaning most investors' capital is returned quickly, but the upside over a full multi-year rally is forgone.
Outcome Distribution
| Outcome | Probability | Product return (index points) |
|---|---|---|
| Autocall — year 1 | 74.91% | 115.50 |
| Autocall — year 2 | 11.23% | 131.00 |
| Autocall — year 3 | 4.54% | 146.50 |
| Autocall — year 4 | 2.76% | 162.00 |
| Autocall — year 5 | 1.76% | 177.50 |
| Autocall — year 6 | 1.02% | 193.00 |
| Matured (index ≤ start) | 2.65% | 100.00 |
| Matured (index > start) | 1.13% | 100 + upside |
Investment Commentary
Points in favor of the structure
- Principal protection. The note's worst simulated outcome is return of principal (0% return); there is no scenario in which the investor loses nominal capital at maturity.
- Favourable risk-adjusted profile. Over the simulated horizon the product shows a higher expected return than the underlying (14.56% vs 14.26% total return) with about a quarter of the volatility (2.90% vs 10.49%).
- Attractive fixed accrual. When called, the note pays a simple 15.50% per year — well above the ≈ 3.78% risk-free rate — so 96.36% of simulated paths beat cash.
- High probability of a quick, positive cash exit. ~75% of paths are called after the first year, returning capital plus a 15.50% gain.
Points of caution
- Upside is capped in years 1–6. Any strong, early index rally is "called away" for the fixed step-up payment; the 1:1 line shows the substantial return given up in those scenarios.
- Maturity upside is diluted by the long 7-year wait. If the note survives all six call dates it only pays off well if the index finishes meaningfully above its start after seven years; the 1.13% of paths that mature with a positive index return produce low annualized figures.
- Opportunity cost when the index is flat/down. 2.65% of paths return only principal (0%), which is below the risk-free rate.
- Issuer/credit risk. All payments depend on Morgan Stanley's ability to pay; the notes are unsecured obligations.
- Valuation / cost drag. The estimated value of the notes on the pricing date (~$874.80 per $1,000) is below the issue price, reflecting embedded structuring, hedging and distribution costs borne by the investor.
Notes on Methodology and Assumptions (summary)
- Underlying simulated over an 84-month horizon with 10,000 Monte-Carlo paths (GJR-GARCH / Student-t).
- The Morgan Stanley Amplitude Index is proprietary with no public price history; the S&P 500 index (^GSPC) is used as a proxy for the underlying and benchmark, with dividends approximated at ≈ 0.98%.
- Risk-free rate = 1-year average 1-year US Treasury yield = 3.78%.
- Figures are simulation estimates, not forecasts; actual results will differ.