info@tokenengine.ai
Structured Product Evaluation
Headline Simulation Results
| Metric | Result |
|---|---|
| Expected annualized return | 11.32% |
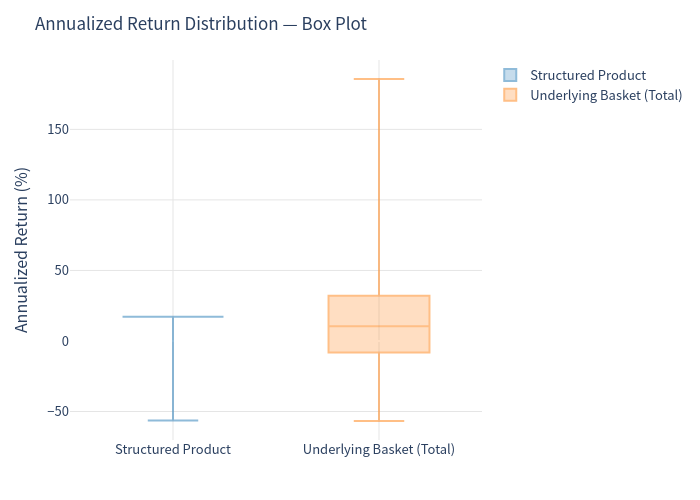
| Expected total return over realized holding period | 8.71% (median 17.20%) |
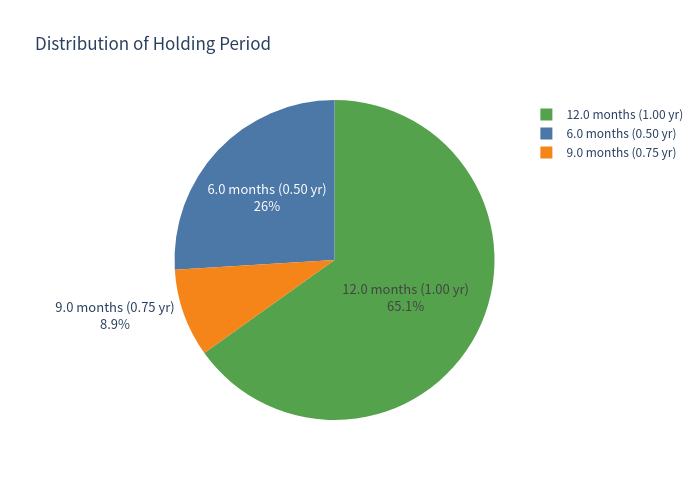
| Expected holding period | 10.17 months (approx. 0.85 yr) |
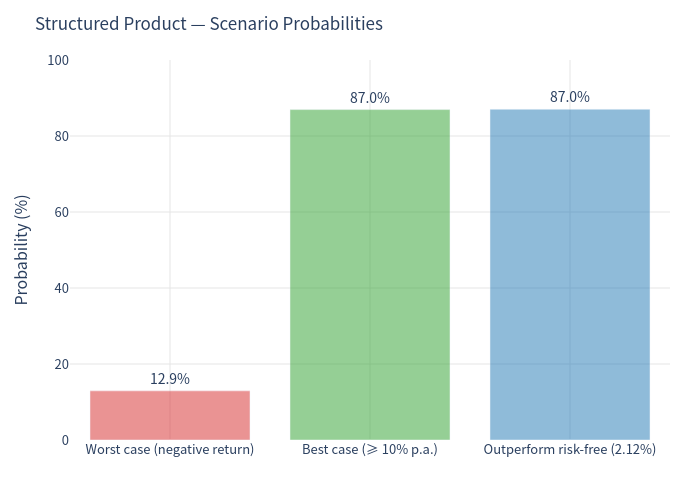
| Probability of a negative return | 12.93% |
| 99% confidence VaR (1-year) | -41.47% |
| Probability of outperforming the risk-free rate (2.12%) | 87.04% |
| Probability of achieving the maximum outcome (par + all 4 coupons = 17.2%) | 52.05% |
Product at a Glance
- Issuer: Leonteq Securities AG (Guernsey Branch), rated Fitch BBB-. Currency: EUR (no FX exposure – all underlyings quote in EUR).
- Denomination / Issue price: EUR 1,000 / 100%. Tenor: ~1 year (Issue 04/11/2026 → Redemption 04/11/2027).
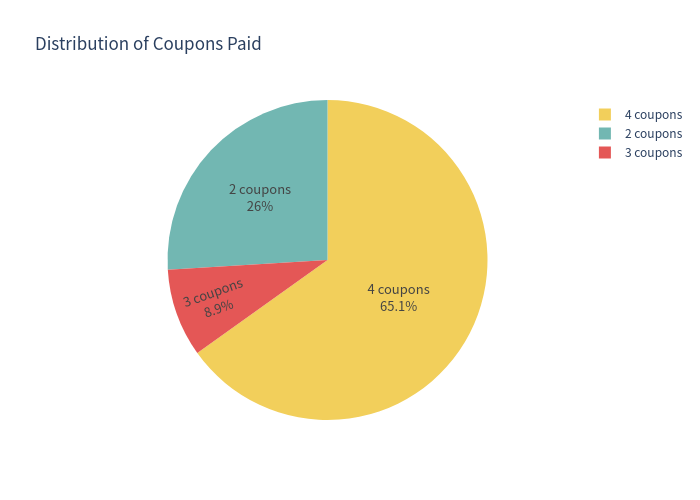
- Coupon: 17.20% p.a., paid as four quarterly coupons of EUR 43.00 (4.30% of notional each) on 05/02, 06/05, 05/08, 04/11/2027 – regardless of market performance.
- Underlyings (worst-of): Airbus SE (AIR.PA), Bayer AG (BAYN.DE), thyssenkrupp AG (TKA.DE).
- Barrier: 55% of starting level, continuously observed. Strike: 100%.
- Issuer callable: on 29/04/2027 and 29/07/2027 (returns par + coupon).
- Upside: capped at par; no equity participation.
How it works (in plain terms)
The product pays a high 17.20% annual coupon no matter what the three shares do. In exchange, you take on worst-of downside risk:
- No share ever trades at or below 55% of its start → you get 100% of your money back at maturity (plus all coupons).
- A share touches 55% at some point, but the worst-performing share still finishes at or above 100% → you still get 100% back (plus coupons).
- A share touches 55% AND the worst share finishes below 100% → you receive that worst-performing share's value, i.e. you lose part of your capital in line with the worst share's decline.
In addition, the issuer may call the product early (at ~6 or ~9 months) and return your par plus the coupon; a call is more likely when the shares are performing well, which caps your upside.
Key Statistics (Annualized)
| Expected Return | Volatility | Prob. of Loss | 99% VaR (1y) | |
|---|---|---|---|---|
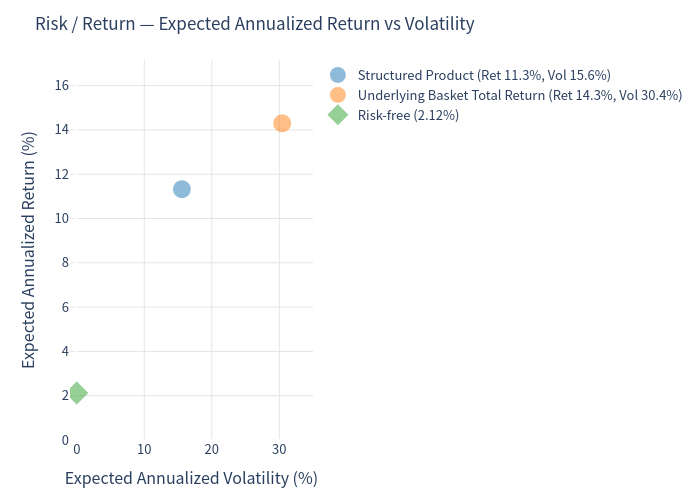
| Structured Product | 11.32% | 15.57% | 12.93% | -41.47% |
| Underlying Basket (Total Return, incl. 1.00% dividend) | 14.30% | 30.43% | 36.00% | -39.59% |
| Risk-free rate (1y EUR) | 2.12% | - | - | - |
The product offers a better risk-adjusted profile than the basket: a return/volatility ratio (Sharpe, vs 2.12% risk-free) of 0.59 versus 0.40 for the basket, with roughly half the volatility (15.6% vs 30.4%) and about a third of the loss frequency (12.9% vs 36.0%). In exchange, the tail (99% VaR) is as severe as the basket (-41.5% vs -39.6%), because in a breach losses track the single worst share.
Charts
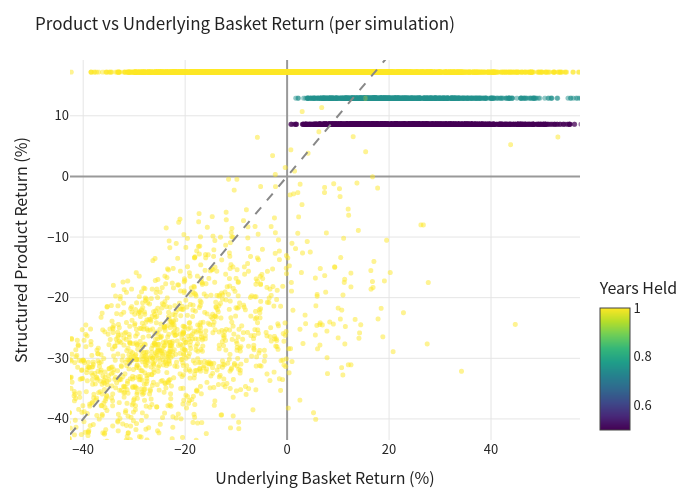
Simulated outcomes – product vs underlying (colored by holding period)
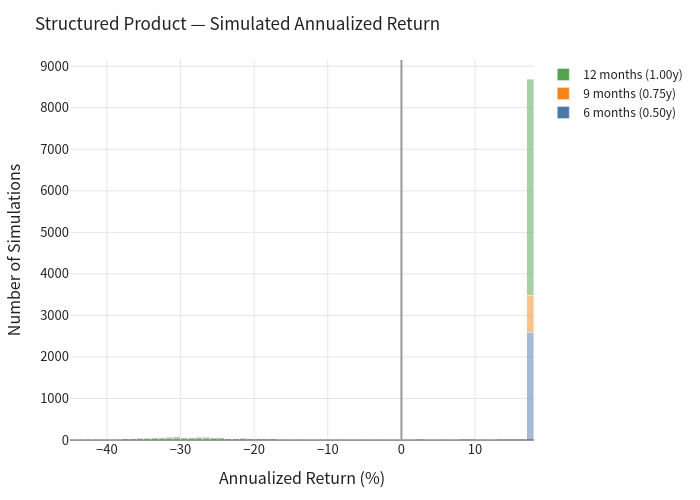
Structured product – distribution of annualized returns (stacked by holding period)
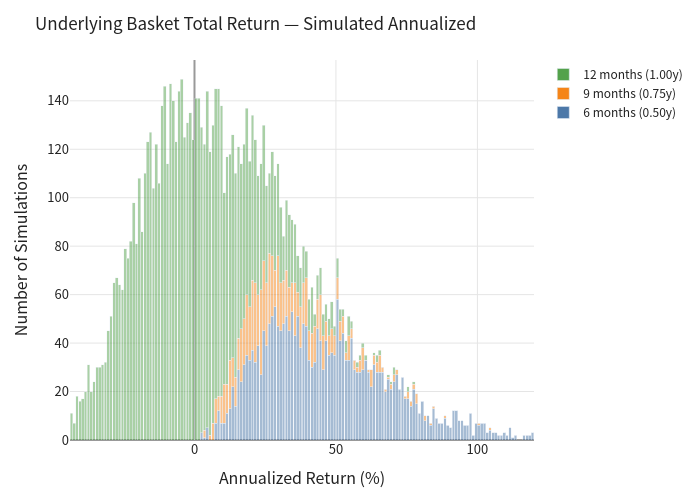
Underlying basket – distribution of annualized total returns
Scenario probabilities
Risk / return positioning (return vs volatility)
Annualized return distribution – box plot
Holding-period distribution (the product is frequently called early)
Number of coupons paid
Investment Commentary
Strengths
- High headline income: 17.20% p.a. is far above the ~2.12% EUR risk-free rate. About 87% of simulations return full principal (par) plus the applicable coupon – whether held to maturity or called early – and roughly 52% reach the maximum outcome of par plus all four coupons.
- Deep, protective barrier: at 55%, the worst-of must fall more than 45% and still be below par at maturity before any capital is lost – a high hurdle that keeps the loss probability to ~13% versus ~36% for holding the basket outright.
- Much lower volatility (approx. 15.6% vs approx. 30.4%) and a superior return-per-unit-of-risk than the underlying basket.
- Frequent early redemption (~35% of paths) returns capital plus coupon within 6–9 months, so realized cash can come back quickly.
Risks / trade-offs
- Worst-of tail concentration: downside is driven by the single weakest of Airbus, Bayer and thyssenkrupp; consequently the 1% worst-case (-41.5%) is comparable to – and slightly worse than – the diversified basket (-39.6%).
- Barrier-recovery scenario is rare: a dip through 55% with a full recovery back above par is very uncommon, so most barrier breaches translate into a capital loss rather than a free pass.
- Upside is capped at par: investors forgo any rally in the three shares beyond the coupons.
- Callable / reinvestment risk: the issuer is likely to call in benign markets, ending the deal early and forcing reinvestment at potentially lower rates.
- Issuer credit risk (Leonteq, BBB-) and idiosyncratic event risk in Bayer / thyssenkrupp (elevated single-name volatility).