Structured Product Evaluation Report
7.70% p.a. Multi Barrier Reverse Convertible (Callable, Quanto CHF) on ZKB Gold ETF & ZKB Silver ETF
Headline Simulation Results
Based on 20,000 Monte-Carlo scenarios of the two underlyings over the full 18-month life of the note:
| Metric | Result |
|---|---|
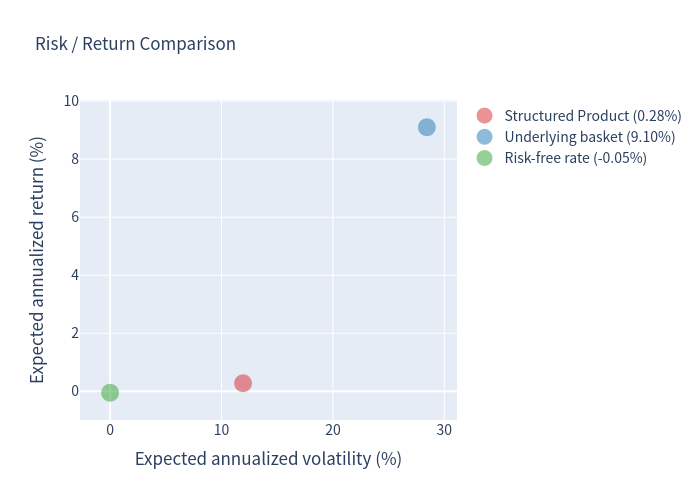
| Expected annualized return | +0.28% |
| Expected total return over realized holding period | -2.60% |
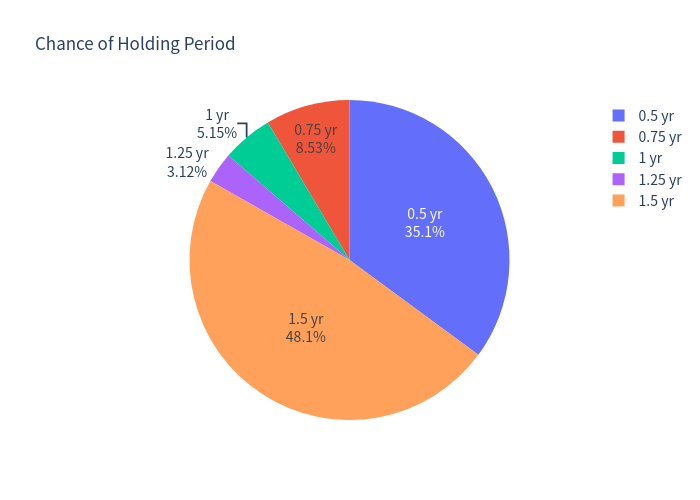
| Expected holding period | ~1.05 years (≈12.6 months) |
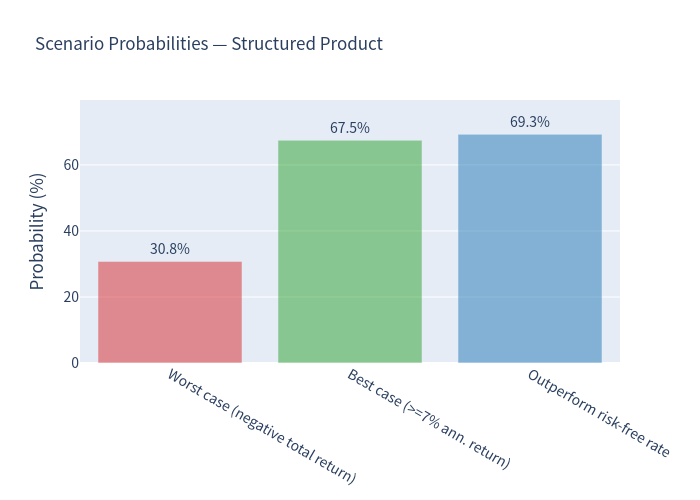
| Probability of a negative return | 30.78% |
| 99% confidence VaR (1-year) | -34.01% |
| Probability of being called early | 51.9% |
| Probability of a barrier (kick-in) event | 38.7% |
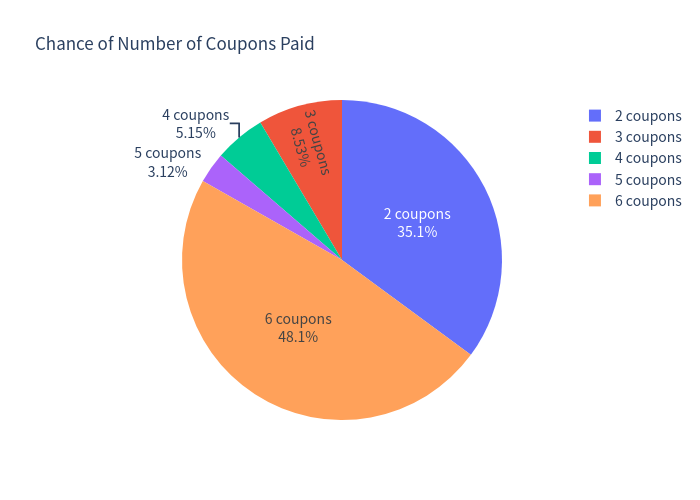
| Average number of coupons received | 4.2 of 6 |
The product aims to pay a 7.70% p.a. coupon (≈1.93% per quarter) on a worst-of pair of precious-metal ETFs. Its expected return is roughly flat: the attractive coupon is largely offset by the market risk of the embedded short put, so an investor should view this mainly as a yield / income trade with a capped upside, not as a growth instrument.
Basic Product Information
| Item | Term |
|---|---|
| Product type | Yield-Enhancement Reverse Convertible (SSPA 1230), Callable |
| Underlyings | ZKB Gold ETF-A (USD) and ZKB Silver ETF AA (USD) — worst-of |
| Coupon | 7.70% p.a., paid quarterly (six payments of CHF 96.25 on the CHF 5,000 denomination) |
| Barrier (kick-in) | 70% of initial, continuously observed on the worst-of |
| Strike / par | 100% |
| Upside | Capped at par (no participation in gains) |
| Currency | Quanto CHF (USD/CHF FX risk neutralised) |
| Early redemption | Issuer callable quarterly from month 6 |
| Collateral | Triparty Collateral Management (TCM) |
How it works (plain English)
- You are paid the coupon in cash every quarter, unconditionally (as long as the note is alive) — even if the metals fall.
- At maturity (or if called early) you normally get your 100% back. Full repayment applies when neither metal ever touches 70% of its starting level during the whole term (observed continuously).
- The catch: if either metal ever trades at or below 70% of its start, the shield is removed. Then, at maturity, if the worse performer is back at or above its start you still get 100%; but if the worse performer ends below its start, you are delivered that worse-performing ETF and lose its percentage decline (the coupons remain yours). The worst simulated outcome was a final redemption of about 19% of par.
- The issuer can call the note early on each quarterly observation date. Because calling makes most sense when the metals are performing (the barrier is safe), the note is likely to be retired early and your return then simply equals the coupon earned up to that point.
Key Statistics
| Metric | Structured Product | Underlying Basket (equal-weight) |
|---|---|---|
| Expected annualized return | +0.28% | +9.10% * |
| Expected annualized volatility | 11.94% | 28.44% |
| Probability of loss | 30.78% | 41.78% |
| 99% confidence VaR (1 year) | -34.01% | -35.20% |
| CHF risk-free rate (1-yr avg) | -0.05% | -0.05% |
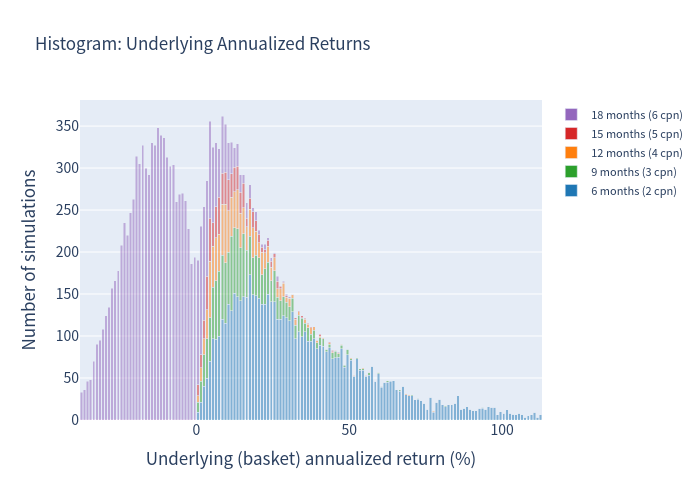
* The underlying figure is measured over the same horizon as the product in each scenario (as required for a like-for-like comparison). Because the note is called early exactly when the metals have risen, most short-horizon observations are positive and annualizing them overstates the basket's representative return. Held for the full 18 months (buy-and-hold), the equal-weight basket instead returns -0.98% annualized (total -0.17%).
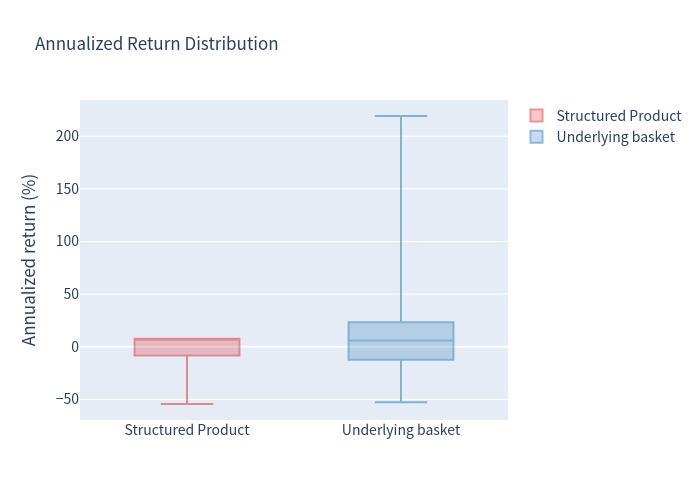
- The product is far less volatile than the raw basket (11.94% vs 28.44% annualized) and cuts the tail risk (99% VaR -34.01% vs -35.20%).
- The coupon is unconditional, so 69.3% of scenarios beat the risk-free rate.
Charts
Simulation Outcomes (product vs underlying, colored by holding period)
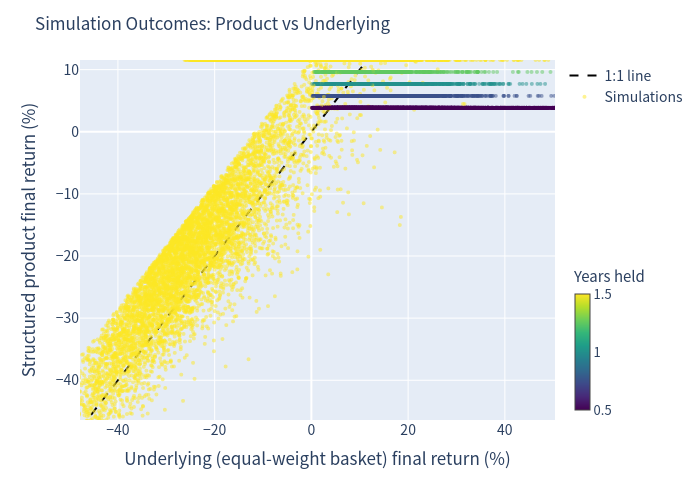
Each point is one simulation. Points on the 1:1 line can only reach the capped product return; early horizontal clustering near +7% reflects the coupon-plus-par payoff of called notes.
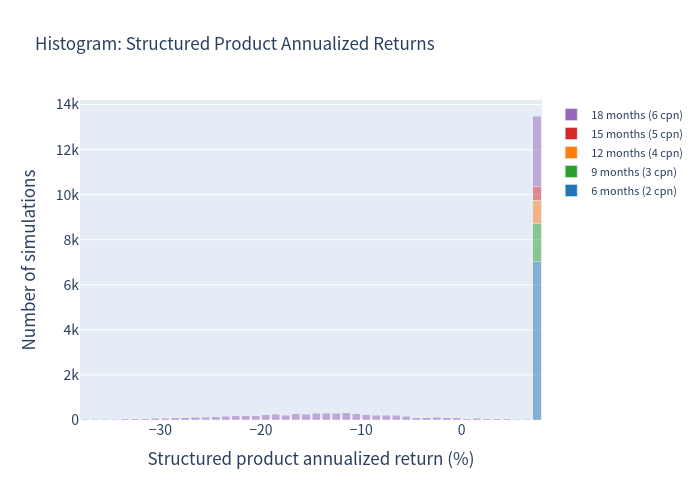
Annualized Return Distribution — Structured Product
Annualized Return Distribution — Underlying Basket
Scenario Probabilities
Risk / Return Comparison
Annualized Return Box Plot
Probability of Holding Period
Probability of Number of Coupons Paid
Investment Commentary
Points in favour
- High, unconditional income: the 7.70% p.a. coupon is paid quarterly regardless of the barrier, providing a steady cash yield that is well above the (near-zero) CHF risk-free rate.
- Conditional 30% downside cushion: a barrier at 70% (observed continuously) means the investor keeps capital whenever both metals avoid a 30% drawdown, even if they end the term lower.
- Worst-of diversification: the trade references two metals with high correlation; the barrier and worst-of test the weaker of the two.
- Lower risk profile than the metal basket: simulated annualized volatility (11.94%) and tail loss (99% VaR -34.01%) are materially lower than holding the two ETFs outright.
- Quanto CHF removes USD/CHF currency risk, and the note is collateralised (TCM).
Points to be aware of
- Return is capped at par — there is no participation if gold and/or silver rally strongly; upside is forfeited.
- Expected return is essentially flat (+0.28% annualized; -2.60% total over the realized holding period). Under the zero-drift (commodity risk-premium) assumption, the coupon roughly compensates for the put risk rather than delivering a positive risk premium.
- Callable structure: the issuer is expected to redeem early (about 52% of simulations) precisely when the metals are performing, so gains are truncated at the coupon.
- Worst-of makes the barrier fragile: silver's simulated volatility is very high (~32% p.a.), so the 70% barrier is the dominant driver of losses; a single metal's drawdown is enough to expose the investor.
- Real downside risk remains: ~30.8% of scenarios end with a loss, and the 99% VaR shows a potential one-year loss of about 34%.
This report is a quantitative evaluation of the term-sheet economics and is not investment advice or a suitability assessment.